FD vs debt mutual funds is a common question for investors who want to manage their money without taking direct exposure to the stock market. Both options can play a role in the conservative part of a portfolio, but they work differently.
A fixed deposit (FD) offers a contracted interest rate for a chosen tenure, subject to the institution’s terms. A debt mutual fund invests in fixed-income securities, and its returns depend on the income and market value of those investments.
So, which option is right for you? The answer depends on your financial goals, investment horizon, liquidity needs, risk tolerance and tax situation.
Table of Contents
- What Is a Fixed Deposit?
- What Is a Debt Mutual Fund?
- FD vs Debt Mutual Funds: 6 Key Differences
- Can You Lose Money in a Debt Mutual Fund?
- Taxation, Liquidity and Safety
- Which Option May Suit Your Needs?
- Frequently Asked Questions
1. What Is a Fixed Deposit?
A fixed deposit is an investment in which you deposit money with a bank or eligible financial institution for a specified period at an agreed interest rate.
For example, if you invest ₹10 lakh in an FD at an illustrative interest rate of 7% per annum for three years, the applicable interest and maturity amount can generally be calculated in advance, subject to the FD’s terms and compounding method.
This predictability makes FDs useful for people who prefer knowing their expected returns.
However, premature withdrawal may result in a penalty or reduced interest. Also, the safety of an FD depends on the institution and applicable protections.
Eligible bank deposits are insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC) up to ₹5 lakh per depositor per bank, including principal and interest, subject to applicable rules.
Learn more through the official DICGC website.
2. What Is a Debt Mutual Fund?
A debt mutual fund pools money from investors and invests it in fixed-income instruments such as government securities, corporate bonds, treasury bills, certificates of deposit and money-market instruments.
Unlike an FD, a debt mutual fund does not offer a guaranteed rate of return or promise that your invested capital will remain unchanged.
Different categories of debt funds have different risk profiles. For example, liquid funds generally invest in short-term instruments, while longer-duration funds may be more sensitive to changes in interest rates.
Before investing, understand the scheme’s portfolio, investment strategy, credit quality, duration and associated risks.
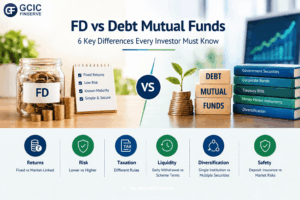
3. FD vs Debt Mutual Funds: 6 Key Differences
The following comparison explains how these two investment options differ.
| Factor | Fixed Deposit | Debt Mutual Fund |
|---|---|---|
| Returns | Contracted interest rate for the tenure | Market-linked returns; not guaranteed |
| Capital value | Generally predictable under the deposit terms | NAV can rise or fall |
| Risk | Institution and deposit-related risks | Interest-rate, credit and liquidity risks |
| Liquidity | Premature withdrawal may have conditions or penalties | Redemption subject to scheme terms and applicable timelines |
| Taxation | Interest generally taxable according to applicable rules | Tax depends on fund classification, acquisition date and applicable tax law |
| Diversification | Exposure to the depositing institution | Can spread investments across multiple securities and issuers |
Neither option is automatically better for every investor. The right choice depends on what you expect the money to achieve.
4. Returns: Fixed Interest vs Market-Linked Performance
One of the main differences in FD vs debt mutual funds is how returns are determined.
With an FD, the applicable interest rate is generally agreed upon when you make the deposit. This makes it easier to estimate the maturity amount.
Debt mutual fund returns are different. They depend on interest income from the underlying securities, changes in their market prices, expenses and other portfolio factors.
For example, when market interest rates fall, existing fixed-rate bonds may become more valuable, potentially increasing a debt fund’s NAV. When interest rates rise, bond prices may fall, reducing the NAV.
Therefore, debt mutual funds can deliver positive or negative returns over a particular period. Higher returns are never guaranteed.
5. Can You Lose Money in a Debt Mutual Fund?
Yes. Debt mutual funds are not risk-free, and their NAV can decline.
Three important risks to understand are:
- Interest-rate risk: Bond prices generally fall when market interest rates rise, all else being equal.
- Credit risk: A bond issuer may experience financial difficulties or fail to meet its payment obligations.
- Liquidity risk: Some securities may be difficult to sell quickly at a reasonable price, especially during stressed market conditions.
These risks vary between schemes. A liquid fund, a short-duration fund and a credit-risk-oriented fund may have very different portfolios and risk characteristics.
Read the scheme’s current Scheme Information Document (SID), portfolio disclosures and risk information before investing.
For more information, visit AMFI India, the Association of Mutual Funds in India.
6. Taxation, Liquidity and Safety
Taxation
FD interest is generally taxable according to the applicable income-tax rules. Tax deducted at source (TDS) may apply where relevant.
Debt mutual fund taxation depends on factors such as the fund’s classification, the date of acquisition and the prevailing tax provisions. Do not assume that debt mutual funds automatically provide a tax advantage over FDs.
Check the latest rules and consider your individual tax situation before making a decision. You can consult the Income Tax Department’s official website.
Liquidity
FDs may allow premature withdrawal, but the applicable conditions, penalties and interest adjustments depend on the institution and deposit terms.
Debt mutual funds generally allow redemptions according to the scheme’s terms. However, exit loads, applicable settlement timelines and restrictions may apply to certain schemes.
Remember that the ability to redeem an investment does not guarantee that you will receive your original invested amount.
Safety
An FD offers greater predictability regarding its contracted interest rate and maturity terms, but it is not automatically risk-free. Deposit insurance applies only within the applicable eligibility and coverage limits.
A debt mutual fund carries market and portfolio risks, and its NAV can fluctuate.
Before choosing either option, assess the risks you can reasonably accept and when you will need the money.
Diversification: An Important Advantage of Debt Mutual Funds
Diversification is another consideration when comparing FDs and debt mutual funds.
If you place your money in one FD, your deposit exposure is concentrated in that institution. A debt mutual fund may invest across several securities, issuers and maturity profiles.
This can help diversify certain risks, but it does not eliminate the possibility of losses. A fund may still be affected by interest-rate movements, credit events or liquidity problems.
Diversification should therefore be considered alongside portfolio quality, investment costs and the scheme’s objectives.
Which Option May Suit Your Needs?
Your investment decision should begin with the purpose of the money.
An FD may be worth considering if:
- You prefer a known interest rate for a specified tenure.
- You want to plan for a future expense with predictable maturity terms.
- You prefer a straightforward deposit product.
- You understand the withdrawal conditions and institution-related risks.
A debt mutual fund may be worth considering if:
- You want exposure to a diversified portfolio of debt securities.
- You understand that NAV can fluctuate.
- You want to explore different debt fund categories and maturity profiles.
- You can select a scheme whose risk characteristics match your investment horizon and objectives.
Before investing in a debt mutual fund, review its credit quality, portfolio concentration, duration, expense ratio and exit load. Do not select a long-duration fund simply because you want to park money for a few weeks or months.
Neither option is suitable for every financial goal, and your overall asset allocation also matters.
FD vs Debt Mutual Funds: Frequently Asked Questions
1. Is a debt mutual fund the same as an FD?
No. An FD is a deposit with an agreed interest rate and tenure, while a debt mutual fund invests in a portfolio of fixed-income securities. Its NAV can fluctuate.
2. Are debt mutual funds risk-free?
No. Debt mutual funds carry interest-rate, credit and liquidity risks. The extent of these risks depends on the scheme’s investments and strategy.
3. Can debt mutual funds give higher returns than FDs?
They can outperform FDs over some periods, but this is not guaranteed. Debt fund returns are market-linked, and investors may experience losses.
4. Which is safer: an FD or a debt mutual fund?
They involve different risks. An FD offers greater predictability of contracted interest and maturity terms, while a debt mutual fund has market-linked NAV and portfolio risks. Eligible bank deposits also have limited DICGC insurance protection, subject to applicable rules.
5. Should I move all my FDs into debt mutual funds?
Not necessarily. Consider your financial goals, investment horizon, liquidity requirements, risk tolerance, tax position and existing investments before making any changes.
6. Which option is better for short-term savings?
The answer depends on when you need the money, how much certainty you require and the risks you can accept. Compare the specific FD terms and the characteristics of any debt fund under consideration rather than assuming that one option is always better.
GCIC Finserve’s Perspective for Delhi NCR Investors
For investors in South Delhi and across Delhi NCR, choosing between an FD and a debt mutual fund should begin with a clear understanding of financial goals, liquidity needs and risk tolerance.
At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), we focus on helping investors understand mutual fund options and how they may fit into their broader financial plans.
If you need help understanding mutual fund categories and their associated risks, connect with GCIC Finserve to learn more.
Final Word
FD vs debt mutual funds is not about finding one universal winner. It is about matching an investment to the purpose of your money.
An FD offers a contracted interest rate and predictable maturity terms, subject to its conditions. A debt mutual fund provides exposure to a portfolio of debt securities, with market-linked returns and the possibility of NAV fluctuations.
Before investing, ask yourself three questions: When will I need the money? How much uncertainty can I accept? And how does this investment fit into my overall financial plan?
Make the objective clear first, and then evaluate the product.
Disclaimer: This article is for educational and informational purposes only and does not constitute investment, tax, legal or financial advice. Mutual fund investments are subject to market risks, including possible loss of principal. Returns are not guaranteed, and past performance does not assure future results. Fixed deposits are subject to the terms of the respective institution and applicable regulations; deposit insurance is subject to eligibility and prescribed limits. Tax laws may change. Please assess your financial goals and risk profile and consult an appropriately qualified professional before making investment decisions.