How should business owners invest surplus cash? It is a different question from the one a salaried investor might ask. A business owner in Delhi, Gurugram, or Noida may have ₹25 lakh, ₹1 crore, or even ₹5 crore sitting in a bank account. It can look like idle money that should be invested immediately. However, not all cash in a business account is genuinely surplus.
Some money is needed for salaries, inventory, supplier payments, taxes, loan repayments, or business expansion. Only after these requirements are considered can a business owner assess how much money may be available for investment.
For Delhi NCR entrepreneurs, the objective is to understand the business’s cash requirements, protect liquidity, and evaluate investment options according to the purpose and time horizon of the funds.
What Is Surplus Cash?
Surplus cash is money that a business does not reasonably expect to need for its normal operations or known financial commitments over the relevant period.
Consider a manufacturer with ₹3 crore in its bank account. The business estimates that it needs ₹80 lakh for working capital, ₹40 lakh for salaries and operating expenses, ₹30 lakh for taxes, and ₹50 lakh for new machinery.
After accounting for these requirements, approximately ₹1 crore remains as potential surplus cash.
This is only an illustrative calculation. Actual requirements may change with customer collections, supplier terms, business conditions, debt repayments, and unexpected expenses.
The important point is that a large bank balance does not automatically mean a large investable surplus. Business owners should first understand which funds are committed and which may genuinely be available for investment.
Business Cash vs Personal Wealth
Business finances and personal finances serve different purposes.
Business cash supports working capital, salaries, inventory, supplier payments, taxes, debt obligations, and planned capital expenditure.
Personal wealth may include personal bank deposits, mutual funds, shares, bonds, real estate, gold, and other investments held by the owner.
Keeping these finances separate helps business owners understand their financial position more clearly. It also reduces the risk of investing money that the business may need at short notice.
Before moving company funds into personal investments, owners should understand the legal, accounting, tax, and ownership implications with their chartered accountant and other qualified professionals.
Step 1: Calculate How Much Cash the Business Actually Needs
The first step in deciding how should business owners invest surplus cash is to calculate the amount that can potentially be invested without compromising business operations.
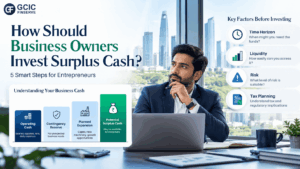
A practical starting point is to divide available cash into three categories.
1. Operating cash
This covers routine expenses such as salaries, rent, supplier payments, utilities, and other immediate commitments. It generally needs to remain readily accessible.
2. Contingency cash
This is a reserve for unexpected expenses, delayed customer payments, temporary revenue declines, or other business disruptions. The appropriate amount depends on the company’s circumstances.
3. Potential surplus cash
This is the amount left after accounting for operating requirements, contingency reserves, taxes, debt obligations, and planned expenditure. Its investment suitability depends on when the money might be needed.
The right balance varies by business. A manufacturer with long receivable cycles may need a larger cash buffer than a professional-services firm with predictable collections. A seasonal business may also need to retain additional liquidity before its peak period.
Do not invest working capital simply because it appears idle. Money received today may already be required for supplier payments over the next few months.
Step 2: Match Surplus Cash to Your Time Horizon
Once potential surplus has been identified, the next question is when the money might be required.
Different investment products have different liquidity characteristics, risks, costs, and tax implications. The following categories are general educational examples, not personalised investment recommendations.
- Short-term requirements—up to 12 months: Business owners may examine options focused on liquidity and capital preservation, such as suitable bank deposits or other short-duration instruments. Terms, early-withdrawal conditions, and risks should be checked.
- Medium-term requirements — 1 to 3 years: Suitable options may include deposits or selected debt-oriented investments, depending on the required access to funds, credit risk, interest-rate risk, and tolerance for fluctuations.
- Longer-term requirements — 3 to 5 years or more: Diversified equity-oriented investments may be considered where the investment horizon and risk profile can accommodate market volatility and potential losses.
- Long-term wealth planning: Eligible investors may also explore portfolio management services (PMS), alternative investment funds (AIFs), or other investment structures after reviewing their features, eligibility requirements, liquidity restrictions, fees, and risks.
These time ranges are broad illustrations, not fixed suitability rules. Even long-term investments can lose value, and some products may be difficult to exit when funds are needed.
Step 3: Understand the Available Investment Options
There is no single investment product that suits every business owner. Understanding the main features and limitations of different options can help make the evaluation more structured.
Fixed Deposits
Fixed deposits may be considered when the amount, expected holding period, and access requirements are relatively clear. Interest terms generally depend on the institution, deposit type, and tenure.
Business owners should examine the institution’s financial position, premature-withdrawal conditions, applicable deposit-insurance limits, taxation, and concentration of deposits. A stated interest rate should not be confused with a guarantee against every possible risk.
Debt Mutual Funds
Debt mutual funds invest in debt and money-market instruments. Their portfolios can differ in maturity, credit quality, interest-rate sensitivity, and liquidity.
Unlike a bank deposit with contractual terms, a debt mutual fund’s net asset value can fluctuate. Investors should review the scheme’s portfolio, risk factors, expenses, and redemption conditions before considering an investment.
Corporate Bonds
Corporate bonds are debt instruments issued by companies. Their risks may include default, credit-rating changes, interest-rate movements, and limited secondary-market liquidity.
A higher stated yield does not necessarily mean a better investment. Issuer financials, repayment terms, maturity, credit quality, and the ability to exit the investment should all be evaluated.
Equity Mutual Funds
Equity mutual funds invest primarily in shares and can experience substantial market fluctuations.
They may be relevant for genuinely long-term investment objectives, subject to the investor’s risk profile and financial position. Money required for next year’s factory expansion or supplier payments should not be exposed to equity-market volatility merely in pursuit of higher returns.
Portfolio Management Services (PMS)
PMS involves portfolio management under a specific service arrangement and applicable regulatory requirements. Portfolio construction, investment approach, fees, reporting, and risks can differ across providers and strategies.
PMS is not automatically better than mutual funds. Investors should examine the applicable eligibility requirements, service agreement, investment strategy, costs, and potential losses before making a decision.
Alternative Investment Funds (AIFs)
AIFs cover different investment strategies and asset classes, which may include private equity, venture capital, and private credit.
Depending on the fund, these investments may involve longer holding periods, limited liquidity, complex structures, and significant risks. Applicable eligibility requirements, minimum investment amounts, fees, and fund-specific terms should be verified in the relevant offering documents and regulations.
Gold and Other Assets
Gold and other assets may form part of a broader personal wealth portfolio, depending on an investor’s circumstances and objectives. Their role should be assessed alongside existing business interests, property holdings, and other investments rather than in isolation.
Step 4: Review Concentration and Liquidity Risks
Business owners can already have substantial financial exposure to a single business, industry, or geographical market.
For example, an owner of a manufacturing company may have most of their wealth tied to that company. Investing a large part of the family’s remaining portfolio in the same industry could increase concentration risk.
Diversification should therefore be considered across the broader financial position, including business ownership, real estate, deposits, shares, mutual funds, and other assets.
Liquidity is equally important. An investment that is difficult to sell may be unsuitable for funds that could be required unexpectedly.
Before investing, business owners should consider:
- How much of their wealth depends on the performance of their business.
- Whether their investments are concentrated in similar industries or asset classes.
- How quickly invested money may need to be accessed.
- Whether a potential loss could affect business operations or family financial goals.
- Whether the costs and risks of an investment are appropriate for its intended purpose.
The aim is to understand the combined financial picture rather than evaluate every investment account separately.
Step 5: Coordinate Investment and Tax Planning
The decision to retain surplus funds within a company or distribute them for personal investment can have tax, accounting, legal, and ownership implications.
The appropriate approach depends on the business structure, the nature of the funds, applicable tax rules, and the owner’s financial circumstances.
Before transferring significant sums or making long-term commitments, coordinate with your chartered accountant and qualified tax or legal professionals. Review the relevant documentation and consider how the proposed transaction could affect the company’s cash flow and financial obligations.
Tax treatment can differ across investment products and may change over time. Decisions should be based on the rules applicable to the particular investor and transaction rather than general assumptions about tax efficiency.
A Practical Example: Investing ₹5 Crore of Business Cash
Consider a hypothetical business owner with ₹5 crore in available cash.
After reviewing the company’s requirements, the owner identifies:
- ₹1.5 crore for working capital.
- ₹50 lakh for taxes and near-term obligations.
- ₹1 crore for a planned manufacturing line.
- ₹50 lakh as a contingency reserve.
This leaves approximately ₹1.5 crore as potential surplus cash.
That figure is a starting point, not an automatic investment amount. The owner must still consider future cash-flow requirements, business risks, the time horizon, the overall financial position, and the legal and tax implications of investing the funds.
Only after these factors have been assessed can suitable options be evaluated.
This illustrates the difference between investing money that happens to be in a bank account and making a considered decision about genuinely available surplus.
Common Mistakes Business Owners Should Avoid
1. Treating the entire bank balance as surplus: Some of the money may already be committed to operations, taxes, debt, or expansion.
2. Chasing the highest advertised return: A higher potential return can involve additional credit, market, liquidity, or other risks.
3. Assuming fixed deposits eliminate every risk: Deposit terms, institutional exposure, insurance limits, early-withdrawal conditions, and taxation still matter.
4. Investing short-term money in volatile products: Funds required for near-term business commitments should be evaluated differently from long-term wealth.
5. Ignoring the owner’s existing exposure: A business owner may already have substantial wealth tied to one company, industry, or property market.
6. Overlooking costs and taxes: Product charges, transaction costs, taxation, and withdrawal conditions can affect the overall outcome.
7. Mixing company and personal finances without professional review: Transfers and distributions should be considered in the context of the business’s legal and tax structure.
How GCIC Finserve Supports Investment Awareness in Delhi NCR
GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705) and an APMI-registered PMS Distributor (APRN-08140). Its distribution-related activities are subject to the applicable registrations and requirements.
For business owners in South Delhi, Gurugram, Noida, and the wider Delhi NCR region, understanding the differences between mutual funds, fixed deposits, bonds, PMS, and AIFs can be an important part of evaluating investment options.
You can explore the GCIC Finserve website and its mutual fund information to learn more about the available categories.
Before making a decision, assess your business’s liquidity requirements, investment horizon, financial position, and risk tolerance. Product selection should follow this assessment, not replace it.
For official regulatory information, refer to the Securities and Exchange Board of India (SEBI) and the applicable scheme or product documentation.
FAQ
1. How should business owners invest surplus cash?
Start by identifying operating requirements, contingency reserves, taxes, debt obligations, and planned expenditure. Then assess the remaining amount against the time horizon, liquidity requirements, risk tolerance, and existing financial exposure before evaluating investment options.
2. Should business owners invest surplus cash in fixed deposits?
Fixed deposits may be considered for certain liquidity and capital-preservation requirements, subject to the institution’s terms and applicable risks. The appropriate amount depends on the business’s cash-flow needs, deposit conditions, taxation, and overall financial position.
3. How much emergency cash should a business keep?
There is no universal amount suitable for every business. The required reserve depends on operating expenses, receivable and payable cycles, revenue stability, debt obligations, seasonality, and access to financing.
4. Can business owners invest surplus cash in equity mutual funds?
Equity mutual funds may be considered for longer-term objectives where the investor can tolerate market fluctuations and potential losses. Funds required for operations or near-term capital expenditure should be assessed separately.
5. Is PMS suitable for business owners?
PMS may be considered by eligible investors after reviewing the service arrangement, applicable eligibility requirements, strategy, fees, risks, and liquidity. It is not automatically more suitable than mutual funds or other investment options.
6. Can business owners invest surplus cash in AIFs?
Some business owners may be eligible to consider AIFs, depending on the applicable rules and the particular fund. These investments can involve complex strategies, significant risks, and limited liquidity. Relevant offering documents and eligibility requirements should be reviewed carefully.
7. Should a business owner invest all surplus cash at once?
Not necessarily. The decision depends on the investment objective, cash-flow outlook, market exposure, and time horizon. Some investors may consider investing over time, but no single approach is appropriate for every situation.
8. Should surplus cash remain in the company or be invested personally?
This depends on the business structure, cash requirements, tax treatment, ownership considerations, and the owner’s personal financial position. Consult a qualified chartered accountant and relevant legal or tax professionals before moving significant amounts.
Final Takeaway
For business owners, surplus cash is money that remains available after the business’s financial requirements have been considered.
The process is straightforward in principle: understand cash flow, protect operating liquidity, identify potential surplus, establish the time horizon, and then evaluate investment options according to their risks and costs.
For entrepreneurs in Delhi NCR, the goal is not simply to pursue higher returns. It is to make informed financial decisions while preserving the ability of the business to meet its commitments and pursue future opportunities.
Disclaimer: This article is for educational and informational purposes only and should not be construed as investment, financial, tax, accounting, or legal advice, a personalised recommendation, or a solicitation to invest. Investment decisions should be based on individual objectives, financial circumstances, risk tolerance, liquidity needs, and applicable product documentation. Mutual Fund investments are subject to market risks; read all scheme-related documents carefully before investing. Market-linked investments can lose value, and past performance does not guarantee future returns. Fixed deposits and other products also have terms and risks that should be reviewed. Tax laws and regulations may change. Consult qualified professionals where appropriate. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705) and an APMI-registered PMS Distributor (APRN-08140); activities are subject to applicable registrations and requirements.