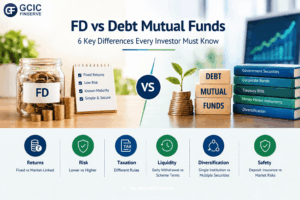
FD vs Debt Mutual Funds: 6 Key Differences Every Delhi NCR Investor Must Know

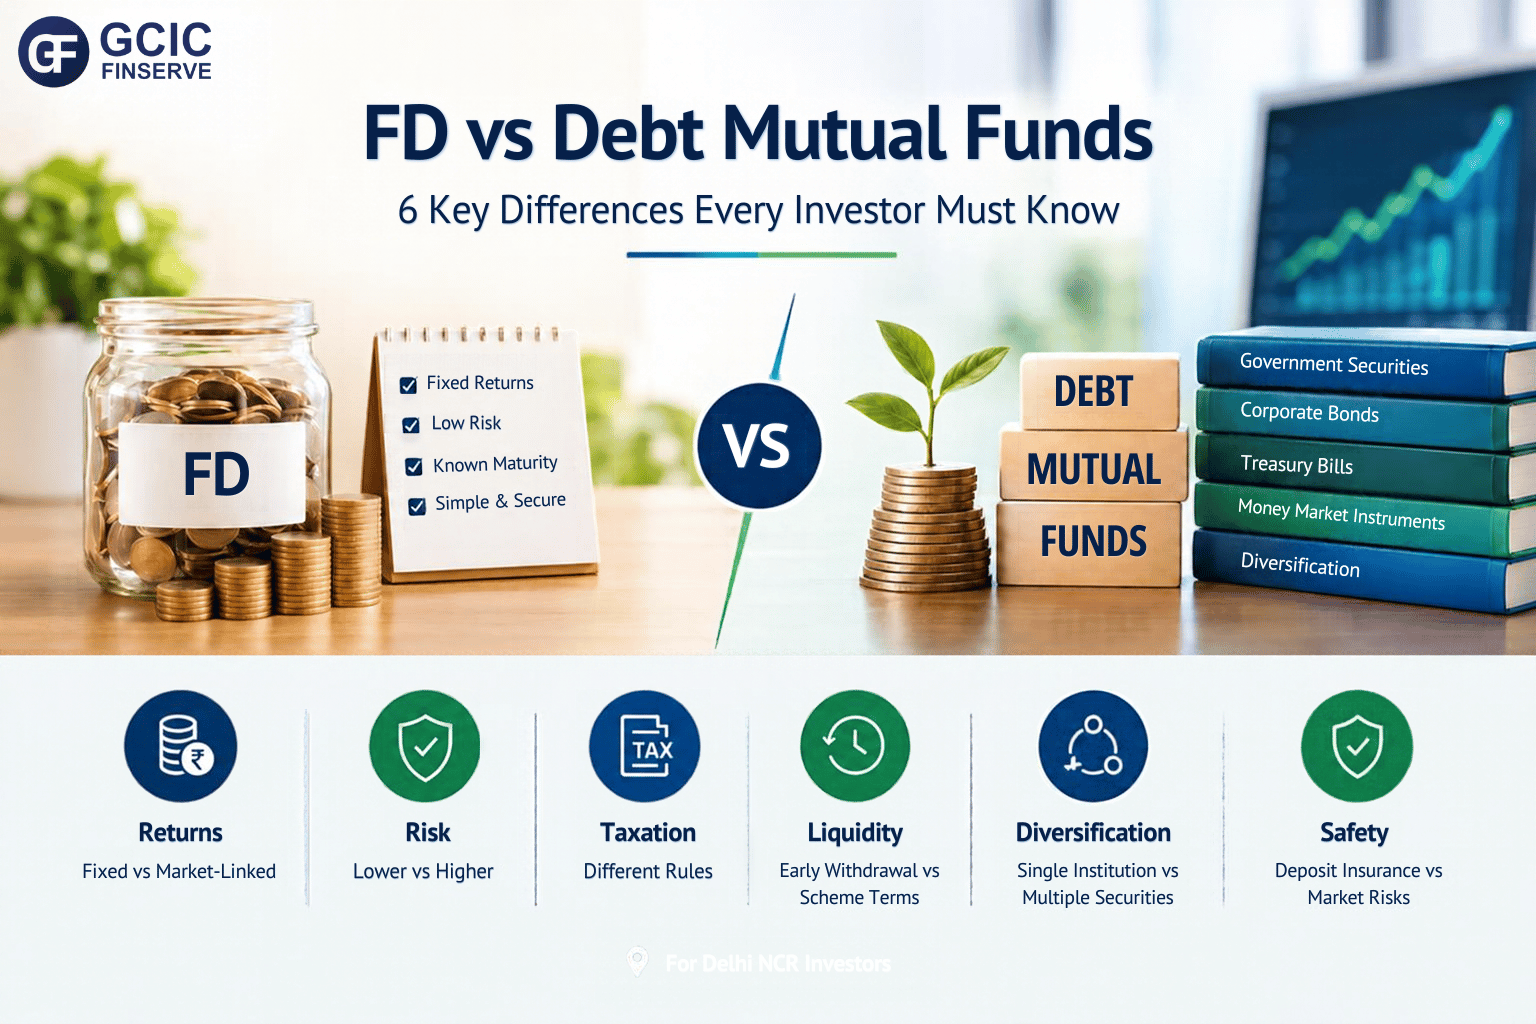
FD vs debt mutual funds comparison highlighting returns, risk, taxation, liquidity, and diversification.
Compare fixed deposits and debt mutual funds to understand their returns, risks, and suitability.

FD vs debt mutual funds is a common question for investors who want to manage their money without taking direct exposure to the stock market. Both options can play a role in the conservative part of a portfolio, but they work differently.

A fixed deposit (FD) offers a contracted interest rate for a chosen tenure, subject to the institution’s terms. A debt mutual fund invests in fixed-income securities, and its returns depend on the income and market value of those investments.

So, which option is right for you? The answer depends on your financial goals, investment horizon, liquidity needs, risk tolerance and tax situation.

Table of Contents

  1. What Is a Fixed Deposit?
  2. What Is a Debt Mutual Fund?
  3. FD vs Debt Mutual Funds: 6 Key Differences
  4. Can You Lose Money in a Debt Mutual Fund?
  5. Taxation, Liquidity and Safety
  6. Which Option May Suit Your Needs?
  7. Frequently Asked Questions

1. What Is a Fixed Deposit?

A fixed deposit is an investment in which you deposit money with a bank or eligible financial institution for a specified period at an agreed interest rate.

For example, if you invest ₹10 lakh in an FD at an illustrative interest rate of 7% per annum for three years, the applicable interest and maturity amount can generally be calculated in advance, subject to the FD’s terms and compounding method.

This predictability makes FDs useful for people who prefer knowing their expected returns.

However, premature withdrawal may result in a penalty or reduced interest. Also, the safety of an FD depends on the institution and applicable protections.

Eligible bank deposits are insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC) up to ₹5 lakh per depositor per bank, including principal and interest, subject to applicable rules.

Learn more through the official DICGC website.

2. What Is a Debt Mutual Fund?

A debt mutual fund pools money from investors and invests it in fixed-income instruments such as government securities, corporate bonds, treasury bills, certificates of deposit and money-market instruments.

Unlike an FD, a debt mutual fund does not offer a guaranteed rate of return or promise that your invested capital will remain unchanged.

Different categories of debt funds have different risk profiles. For example, liquid funds generally invest in short-term instruments, while longer-duration funds may be more sensitive to changes in interest rates.

Before investing, understand the scheme’s portfolio, investment strategy, credit quality, duration and associated risks.

3. FD vs Debt Mutual Funds: 6 Key Differences

The following comparison explains how these two investment options differ.

Factor Fixed Deposit Debt Mutual Fund
Returns Contracted interest rate for the tenure Market-linked returns; not guaranteed
Capital value Generally predictable under the deposit terms NAV can rise or fall
Risk Institution and deposit-related risks Interest-rate, credit and liquidity risks
Liquidity Premature withdrawal may have conditions or penalties Redemption subject to scheme terms and applicable timelines
Taxation Interest generally taxable according to applicable rules Tax depends on fund classification, acquisition date and applicable tax law
Diversification Exposure to the depositing institution Can spread investments across multiple securities and issuers

Neither option is automatically better for every investor. The right choice depends on what you expect the money to achieve.

4. Returns: Fixed Interest vs Market-Linked Performance

One of the main differences in FD vs debt mutual funds is how returns are determined.

With an FD, the applicable interest rate is generally agreed upon when you make the deposit. This makes it easier to estimate the maturity amount.

Debt mutual fund returns are different. They depend on interest income from the underlying securities, changes in their market prices, expenses and other portfolio factors.

For example, when market interest rates fall, existing fixed-rate bonds may become more valuable, potentially increasing a debt fund’s NAV. When interest rates rise, bond prices may fall, reducing the NAV.

Therefore, debt mutual funds can deliver positive or negative returns over a particular period. Higher returns are never guaranteed.

5. Can You Lose Money in a Debt Mutual Fund?

Yes. Debt mutual funds are not risk-free, and their NAV can decline.

Three important risks to understand are:

  • Interest-rate risk: Bond prices generally fall when market interest rates rise, all else being equal.
  • Credit risk: A bond issuer may experience financial difficulties or fail to meet its payment obligations.
  • Liquidity risk: Some securities may be difficult to sell quickly at a reasonable price, especially during stressed market conditions.

These risks vary between schemes. A liquid fund, a short-duration fund and a credit-risk-oriented fund may have very different portfolios and risk characteristics.

Read the scheme’s current Scheme Information Document (SID), portfolio disclosures and risk information before investing.

For more information, visit AMFI India, the Association of Mutual Funds in India.

6. Taxation, Liquidity and Safety

Taxation

FD interest is generally taxable according to the applicable income-tax rules. Tax deducted at source (TDS) may apply where relevant.

Debt mutual fund taxation depends on factors such as the fund’s classification, the date of acquisition and the prevailing tax provisions. Do not assume that debt mutual funds automatically provide a tax advantage over FDs.

Check the latest rules and consider your individual tax situation before making a decision. You can consult the Income Tax Department’s official website.

Liquidity

FDs may allow premature withdrawal, but the applicable conditions, penalties and interest adjustments depend on the institution and deposit terms.

Debt mutual funds generally allow redemptions according to the scheme’s terms. However, exit loads, applicable settlement timelines and restrictions may apply to certain schemes.

Remember that the ability to redeem an investment does not guarantee that you will receive your original invested amount.

Safety

An FD offers greater predictability regarding its contracted interest rate and maturity terms, but it is not automatically risk-free. Deposit insurance applies only within the applicable eligibility and coverage limits.

A debt mutual fund carries market and portfolio risks, and its NAV can fluctuate.

Before choosing either option, assess the risks you can reasonably accept and when you will need the money.

Diversification: An Important Advantage of Debt Mutual Funds

Diversification is another consideration when comparing FDs and debt mutual funds.

If you place your money in one FD, your deposit exposure is concentrated in that institution. A debt mutual fund may invest across several securities, issuers and maturity profiles.

This can help diversify certain risks, but it does not eliminate the possibility of losses. A fund may still be affected by interest-rate movements, credit events or liquidity problems.

Diversification should therefore be considered alongside portfolio quality, investment costs and the scheme’s objectives.

Which Option May Suit Your Needs?

Your investment decision should begin with the purpose of the money.

An FD may be worth considering if:

  • You prefer a known interest rate for a specified tenure.
  • You want to plan for a future expense with predictable maturity terms.
  • You prefer a straightforward deposit product.
  • You understand the withdrawal conditions and institution-related risks.

A debt mutual fund may be worth considering if:

  • You want exposure to a diversified portfolio of debt securities.
  • You understand that NAV can fluctuate.
  • You want to explore different debt fund categories and maturity profiles.
  • You can select a scheme whose risk characteristics match your investment horizon and objectives.

Before investing in a debt mutual fund, review its credit quality, portfolio concentration, duration, expense ratio and exit load. Do not select a long-duration fund simply because you want to park money for a few weeks or months.

Neither option is suitable for every financial goal, and your overall asset allocation also matters.

FD vs Debt Mutual Funds: Frequently Asked Questions

1. Is a debt mutual fund the same as an FD?

No. An FD is a deposit with an agreed interest rate and tenure, while a debt mutual fund invests in a portfolio of fixed-income securities. Its NAV can fluctuate.

2. Are debt mutual funds risk-free?

No. Debt mutual funds carry interest-rate, credit and liquidity risks. The extent of these risks depends on the scheme’s investments and strategy.

3. Can debt mutual funds give higher returns than FDs?

They can outperform FDs over some periods, but this is not guaranteed. Debt fund returns are market-linked, and investors may experience losses.

4. Which is safer: an FD or a debt mutual fund?

They involve different risks. An FD offers greater predictability of contracted interest and maturity terms, while a debt mutual fund has market-linked NAV and portfolio risks. Eligible bank deposits also have limited DICGC insurance protection, subject to applicable rules.

5. Should I move all my FDs into debt mutual funds?

Not necessarily. Consider your financial goals, investment horizon, liquidity requirements, risk tolerance, tax position and existing investments before making any changes.

6. Which option is better for short-term savings?

The answer depends on when you need the money, how much certainty you require and the risks you can accept. Compare the specific FD terms and the characteristics of any debt fund under consideration rather than assuming that one option is always better.

GCIC Finserve’s Perspective for Delhi NCR Investors

For investors in South Delhi and across Delhi NCR, choosing between an FD and a debt mutual fund should begin with a clear understanding of financial goals, liquidity needs and risk tolerance.

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), we focus on helping investors understand mutual fund options and how they may fit into their broader financial plans.

If you need help understanding mutual fund categories and their associated risks, connect with GCIC Finserve to learn more.

Final Word

FD vs debt mutual funds is not about finding one universal winner. It is about matching an investment to the purpose of your money.

An FD offers a contracted interest rate and predictable maturity terms, subject to its conditions. A debt mutual fund provides exposure to a portfolio of debt securities, with market-linked returns and the possibility of NAV fluctuations.

Before investing, ask yourself three questions: When will I need the money? How much uncertainty can I accept? And how does this investment fit into my overall financial plan?

Make the objective clear first, and then evaluate the product.

Disclaimer: This article is for educational and informational purposes only and does not constitute investment, tax, legal or financial advice. Mutual fund investments are subject to market risks, including possible loss of principal. Returns are not guaranteed, and past performance does not assure future results. Fixed deposits are subject to the terms of the respective institution and applicable regulations; deposit insurance is subject to eligibility and prescribed limits. Tax laws may change. Please assess your financial goals and risk profile and consult an appropriately qualified professional before making investment decisions.
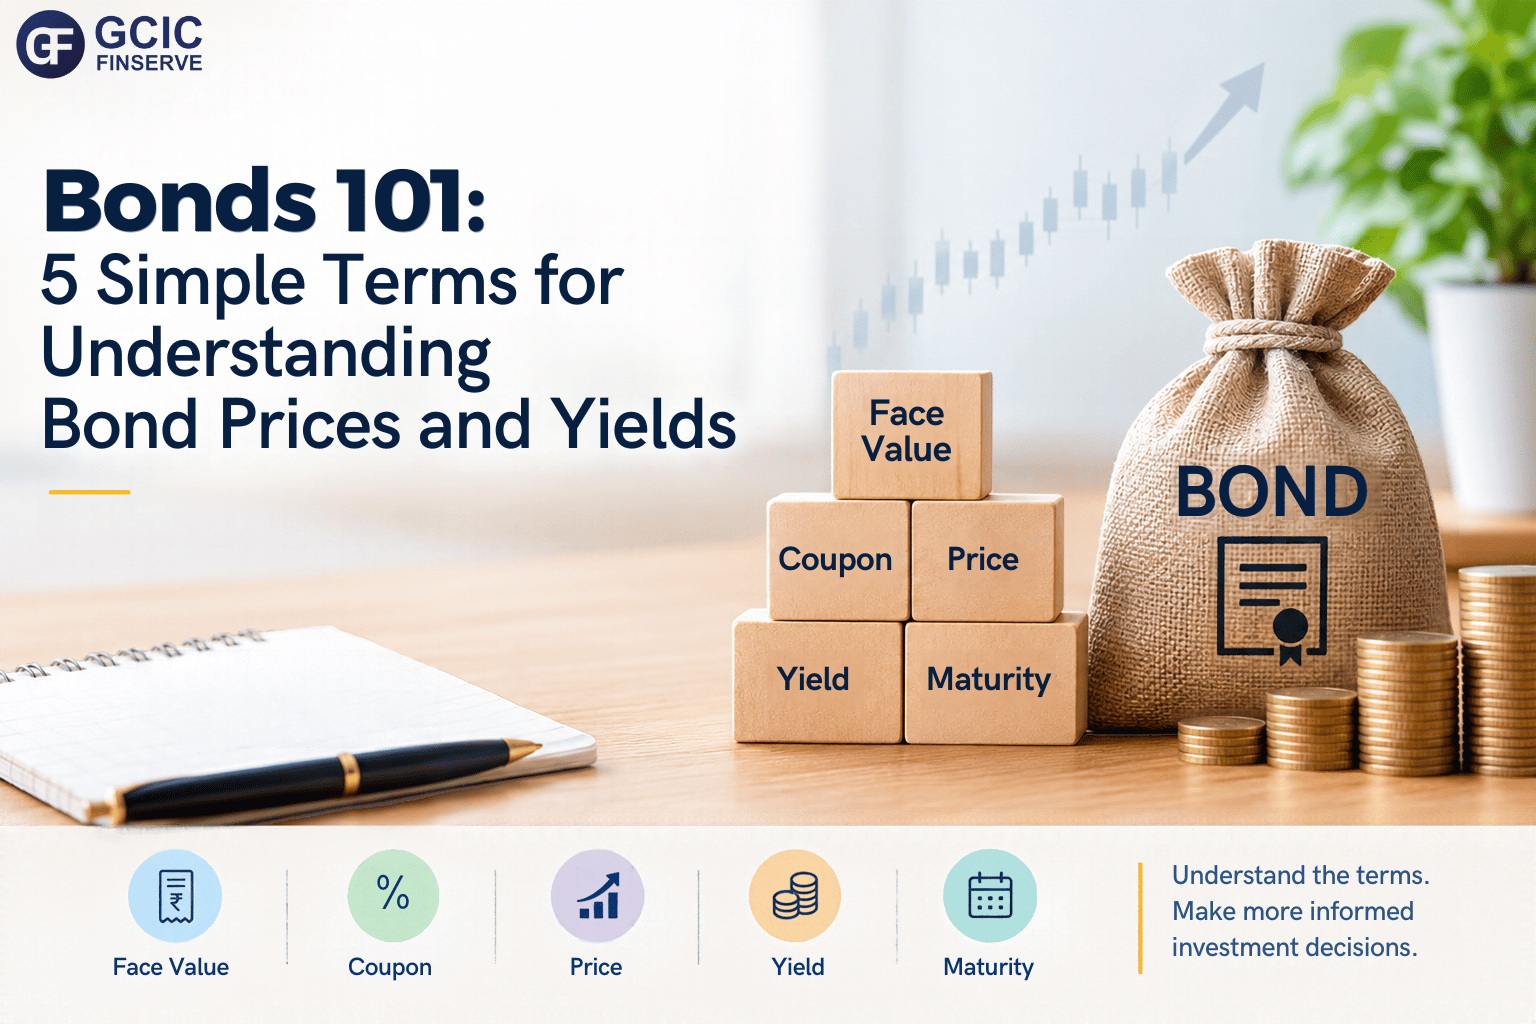
Bonds 101: 5 Simple Terms for Understanding Bond Prices and Yields

Understanding bond prices and yields for investors
A simple visual guide to understanding bond prices and yields.

Understanding bond prices and yields can feel complicated when you first see a bond listing with terms such as 8% coupon, 7.5% yield, ₹1,000 face value, 2031 maturity, or a market price of ₹980 or ₹1,020.

But the basic idea is simple.

A bond is essentially a loan. You lend money to a government, company, or other issuer, and in return, the issuer promises to pay interest and repay the principal according to the terms of the bond.

To understand most bond listings, you need to know five basic terms:

Face value, coupon, price, yield, and maturity.

Once these concepts become clear, understanding bond prices and yields becomes much easier.

A Simple Example: Lending ₹1,000

Imagine a company issues a bond with a face value of ₹1,000.

It promises to pay you 8% interest every year and repay the ₹1,000 principal after five years, subject to the issuer meeting its obligations.

In simple terms:

  • You invest: ₹1,000
  • Annual coupon: 8%
  • Annual interest: ₹80
  • Maturity: 5 years
  • Principal repayment: ₹1,000 at maturity, subject to the issuer’s obligations

This is the basic structure of a bond.

However, there is an important difference between bonds and fixed deposits: bonds can trade in the market, so their market price can move above or below their face value.

That’s where understanding bond prices and yields becomes important.

What Is Face Value?

Face value is the amount stated on the bond.

For example, if a bond has a face value of ₹1,000, that is the reference amount used to calculate its coupon payments. Subject to the bond’s terms and the issuer meeting its obligations, the face value is normally the amount repaid when the bond matures.

However, the face value is not necessarily the price you pay.

A ₹1,000 face-value bond could trade at:

  • ₹950
  • ₹1,000
  • ₹1,050

The face value remains ₹1,000, while the market price changes based on factors such as interest rates, demand, credit risk and liquidity.

What Is a Coupon?

The coupon is the interest rate specified by the bond.

Suppose a bond has:

  • Face value: ₹1,000
  • Coupon rate: 8%

The annual coupon payment would generally be:

₹1,000 × 8% = ₹80

An important point is that the coupon is calculated on the face value, not necessarily on the price you paid.

For example, if you purchase the same bond for ₹950, you would still generally receive ₹80 in annual coupon payments, subject to the bond’s terms.

If you purchase it for ₹1,050, the coupon would still generally be ₹80.

So why does the market price matter?

Because your purchase price affects the yield you receive relative to your investment.

Understanding Bond Prices and Yields: Why Do Bond Prices Move?

This is one of the most important concepts for bond investors.

Bond prices and market interest rates generally move in opposite directions.

When interest rates rise

Suppose your existing bond pays an 8% coupon.

Now imagine new bonds with similar risk start offering higher rates.

Your existing 8% bond becomes relatively less attractive. Its market price may therefore fall so that its effective yield becomes more competitive.

When interest rates fall

Now imagine new bonds with similar risk offer lower rates.

Your existing 8% bond may become more attractive because it offers a higher fixed coupon than newly issued bonds.

Its market price may therefore rise.

The simple rule

When market interest rates rise, existing bond prices generally fall.

When market interest rates fall, existing bond prices generally rise.

This relationship is central to understanding bond prices and yields.

The actual price movement depends on several factors, including the bond’s maturity, duration, credit quality, liquidity, and prevailing market conditions.

What Is Yield and Yield to Maturity?

The coupon rate and yield are not necessarily the same thing.

Suppose our ₹1,000 face-value bond pays ₹80 per year.

If you buy it for ₹950, your simple current yield based on the annual coupon would be:

₹80 ÷ ₹950 × 100 = 8.42%

If you buy the same bond for ₹1,050:

₹80 ÷ ₹1,050 × 100 = 7.62%

So, although the coupon remains 8%, the yield based on your purchase price changes.

What Is Yield to Maturity?

Yield to Maturity (YTM) is a more comprehensive measure.

It estimates the annualised return you may earn if you purchase the bond at its current market price and hold it until maturity, taking into account:

  • Coupon payments
  • Purchase price
  • Time remaining until maturity
  • Amount expected to be repaid at maturity

For example, buying a bond below its face value may result in both coupon income and a potential gain if the bond is repaid at face value at maturity, assuming the issuer meets its obligations.

This is why YTM can be more useful than coupon rate alone when comparing bonds.

However, YTM is based on assumptions and does not eliminate credit, liquidity, interest-rate, or reinvestment risks.

Credit Risk, Maturity, and Duration

A bond is still a form of lending, so it carries risk.

Credit Risk

Credit risk is the possibility that the issuer may not make interest or principal payments as promised.

Credit ratings such as AAA, AA, and other ratings can provide information about an issuer’s creditworthiness, but a rating is not a guarantee of repayment.

A bond offering a higher yield is therefore not automatically better.

A higher yield may reflect higher perceived risk, lower liquidity, or other characteristics of the bond.

Maturity

Maturity is the date when the bond’s principal is scheduled to be repaid, subject to the bond’s terms and the issuer meeting its obligations.

A bond maturing in 2031, for example, has a scheduled maturity date in 2031.

Generally, the longer you remain invested, the longer your money may be exposed to changes in interest rates and other market conditions.

Duration

Duration is a measure of a bond’s sensitivity to changes in interest rates.

In general, bonds with higher duration tend to experience larger price movements when interest rates change.

This is why two bonds with similar coupons can behave very differently when market interest rates move.

Bonds vs Fixed Deposits

Bonds and fixed deposits may appear similar because both can provide interest income, but they work differently.

Feature Bonds Fixed Deposits
Nature Market-linked debt security Deposit with a bank/financial institution
Interest Coupon as specified by the bond Rate fixed according to FD terms
Market price Can rise or fall Usually no market price fluctuation like a traded bond
Early exit May involve selling in the market Premature withdrawal depends on the institution’s terms
Credit risk Depends on the issuer Depends on the deposit-taking institution and applicable protection/framework
Liquidity Depends on market demand Depends on the FD’s terms and premature-withdrawal facility
Return consideration Coupon, purchase price and potential price movement matter Interest rate and applicable terms matter

Neither is automatically better.

The right choice depends on factors such as your financial goals, investment horizon, liquidity needs, risk tolerance and overall portfolio.

What to Check Before Buying a Bond

Don’t look only at the headline coupon rate.

Before considering a bond, review:

1. Issuer

Understand who is borrowing your money.

Look at the issuer’s financial position, business profile and available disclosures.

2. Credit Rating

Check the bond’s credit rating and understand what it indicates about credit risk.

Remember that ratings are opinions about creditworthiness, not guarantees.

3. Coupon

Understand how much interest the bond is scheduled to pay and how frequently payments are made.

4. Market Price

Check the actual price at which you would be purchasing the bond.

A bond with a high coupon may not necessarily provide a high effective return if it is trading at a significant premium.

5. Yield or YTM

Compare the yield or YTM rather than looking only at the coupon rate.

6. Maturity

Check how long your money may remain invested and when principal is scheduled to be repaid.

7. Liquidity

Check how actively the bond trades.

A bond may be difficult to sell quickly at a desirable price if there is limited market liquidity.

8. Risks and Terms

Read the bond’s documentation carefully, including applicable risks, payment terms, security, covenants and other conditions.

For official information on government securities and retail participation, investors can refer to RBI Retail Direct.

Understanding Bonds with GCIC Finserve

At GCIC Finserve, we believe investment decisions should begin with understanding the product, its risks, and how it fits into your overall financial goals.

For Delhi NCR investors, understanding the differences between bonds, fixed deposits, mutual funds, and other investment products can help create a more informed approach to financial planning.

If you want to understand how different investment options may fit your financial objectives and risk profile, connect with GCIC Finserve to discuss your requirements.

Frequently Asked Questions

Q1. Is an 8% coupon the same as an 8% return?

No.

An 8% coupon generally means the bond pays 8% of its face value as interest, subject to the bond’s terms. Your actual return can differ depending on the price you paid, coupon payments, holding period and the amount received at maturity or sale.

Q2. Why can a ₹1,000 bond trade at ₹950?

Because bonds trade in the market.

Changes in interest rates, demand and supply, credit risk, liquidity and other market factors can cause a bond’s market price to move above or below its ₹1,000 face value.

Q3. Why do bond prices fall when interest rates rise?

When new bonds offer higher interest rates, older bonds with lower fixed coupons may become less attractive.

Their market prices may therefore fall to make their effective yields more competitive.

Q4. Is a higher bond yield always better?

No.

A higher yield may come with higher credit risk, interest-rate risk, liquidity risk, or other risks.

Investors should consider risk and return together, rather than choosing a bond only because its yield is higher.

Q5. Can I lose money in a bond?

Yes.

You may experience a loss if you sell the bond at a lower market price than your purchase price.

There is also the possibility of loss if the issuer fails to meet its payment obligations.

Therefore, bonds should not automatically be considered risk-free investments.

Q6. What is the difference between a coupon and YTM?

The coupon is the interest rate specified by the bond and is generally calculated on its face value.

YTM estimates the annualised return based on the bond’s current purchase price, coupon payments, time to maturity, and repayment amount at maturity, subject to its assumptions.

Q7. Are bonds suitable for every investor?

Not necessarily.

The suitability of a bond depends on factors such as your financial goals, investment horizon, liquidity requirements, and risk profile.

It is important to understand the specific bond and its risks before investing.

Final Word

Understanding bond prices and yields becomes much easier once you remember five basic concepts:

  • Face Value — the amount stated on the bond
  • Coupon — the interest specified by the bond
  • Price — what you actually pay or receive when trading the bond
  • Yield — the return implied by the price and cash flows
  • Maturity — when the principal is scheduled to be repaid

The most important relationship to remember is:

Interest rates rise → existing bond prices generally fall

Interest rates fall → existing bond prices generally rise

Once you understand this relationship, along with credit risk, maturity, duration, and YTM, bond listings become much easier to evaluate.

The goal should not be to simply find the bond offering the highest rate. Instead, consider return, risk, liquidity, maturity, and how the investment fits into your overall financial plan.


Disclaimer: This article is for educational and informational purposes only and should not be considered investment advice or a recommendation to buy or sell any bond or financial product. Bond investments are subject to interest-rate risk, credit risk, liquidity risk and other applicable risks. Yields and returns are based on assumptions and may not represent actual realized returns. Investors should review the specific terms, issuer, credit rating, and risks of any investment before investing and consult a qualified financial professional where appropriate.


Are Indian Markets Too Expensive Right Now? 5 Honest Answers Every Delhi NCR Investor Should Know

Indian market valuation and investment planning for Delhi NCR investors
Understanding Indian market valuations, investment risks and long-term financial planning.

Are Indian markets too expensive right now? It is a question many investors ask when stock-market valuations appear high or the Nifty 50 is trading near elevated levels.

The concern is understandable. Nobody wants to invest a large amount just before a major market correction. At the same time, waiting indefinitely for markets to become “cheap” can also create its own challenges.

The more useful question is not simply whether Indian markets look expensive. It is whether current valuations are supported by earnings, business growth, economic conditions and your own investment horizon.

For investors in Delhi NCR and elsewhere, understanding this difference can help bring more perspective to market decisions.

What Does “Expensive” Mean in the Stock Market?

When investors describe a market as expensive, they are generally talking about valuation.

One commonly used measure is the Price-to-Earnings (P/E) ratio. It compares a company’s share price with its earnings per share.

For example, if a company earns ₹10 per share and its share price is ₹200, its P/E ratio is 20.

But valuation should not be viewed in isolation.

A company or market trading at a higher valuation may still have the potential to grow its earnings over time. Similarly, a low valuation does not automatically mean that an investment is attractive.

Therefore, when asking, “Are Indian markets too expensive right now?” investors should look beyond a single valuation number and consider earnings growth, economic conditions, business fundamentals, and their own financial objectives.

Investors can also review their broader financial assessment and investment planning before making decisions based on short-term market movements.

1. Are Indian Markets Too Expensive Right Now?

There is no single valuation measure that can conclusively tell investors whether the entire Indian market is “too expensive.”

Indian equities can trade at valuations above or below their historical averages at different points in the market cycle. Valuations can also differ significantly between sectors and individual companies.

For this reason, describing the entire market as either “cheap” or “expensive” can oversimplify a much more complicated situation.

A better approach is to consider questions such as:

  • Are corporate earnings growing?
  • Are current valuations supported by business fundamentals?
  • What are the broader economic conditions?
  • How much volatility can you tolerate?
  • When will you actually need the invested money?

Market valuation is therefore one factor to consider, not a standalone investment decision.

For official market information, investors can refer to NSE India and its publicly available market and research resources.

2. Why Waiting for a Correction Can Be Difficult

Suppose you believe the market is expensive and decide to wait for a correction.

The market may fall eventually. But it may also remain elevated or move higher before any meaningful correction occurs.

This creates a common dilemma.

If markets rise while you remain on the sidelines, you may later feel pressure to invest at an even higher level. If markets fall sharply after you invest, you may question whether waiting would have been better.

The important point is that short-term market movements are difficult to predict consistently.

Even when valuations appear stretched, investors cannot know exactly when a correction will occur or how deep it will be.

That is why investment decisions are generally better considered in the context of financial goals, time horizon, and risk tolerance rather than a single prediction about the next market move.

3. Can a Market Grow Into Its Valuation?

Yes, this can happen.

Consider a simplified example.

A company earns ₹10 per share and trades at ₹200, giving it a P/E of 20.

If the company’s earnings increase to ₹15 per share while its share price remains at ₹200, its P/E would fall to approximately 13.3.

The share price did not fall. Instead, the underlying earnings increased.

Real markets are much more complex because prices reflect expectations about future earnings, interest rates, economic conditions, and investor sentiment.

Nevertheless, the example demonstrates an important point:

Today’s valuation does not by itself determine tomorrow’s market return.

A market that appears expensive today can become more reasonably valued if earnings grow. Equally, valuations can remain elevated or become more stretched if investor expectations rise faster than underlying earnings.

4. What Should Long-Term Investors Focus On?

A short-term market participant may ask:

“What will the market do next?”

A long-term investor may need to ask a different question:

“What am I investing for, and how long can I remain invested?”

Equity markets can experience substantial declines over shorter periods. Investors may therefore experience periods of volatility, sometimes lasting for extended periods.

This is why an investment horizon matters.

Money required for a near-term financial commitment may need to be treated differently from money being invested for a long-term goal.

Instead of trying to predict every market high and low, long-term investors can focus on:

  • Financial goals
  • Investment horizon
  • Risk tolerance
  • Asset allocation
  • Diversification
  • Portfolio suitability
  • Ability to remain invested during market volatility

Historical market performance can provide context, but it does not guarantee future returns.

If you are reviewing your existing investment approach, you can also explore GCIC’s financial assessment to understand the broader factors that may need to be considered.

5. How Regular Investing Can Help Manage Timing Risk

Regular investing can be one way of reducing the pressure associated with trying to identify the “perfect” entry point.

When markets are higher, a fixed investment amount buys fewer units. When prices are lower, the same amount can buy more units.

This does not remove market risk and does not guarantee profits.

However, for investors whose financial goals and risk profile are suitable for regular investing, investing systematically can reduce dependence on making a single large timing decision.

The appropriate approach can vary from one investor to another, particularly when dealing with a significant lump sum.

For general investor education and mutual fund-related information, investors can also refer to AMFI.

What Should You Consider When Markets Look Expensive?

There is no universal answer.

If You Are Already Invested

A higher market valuation by itself may not necessarily mean that an investor should make a wholesale change to their portfolio.

It may be more useful to review whether the existing asset allocation remains aligned with the investor’s financial goals, investment horizon and risk profile.

If You Invest Regularly

Market valuations can be one factor to monitor, but stopping a long-term investment plan solely because markets appear expensive may not be appropriate for every investor.

The decision should be considered in the context of the investor’s objectives and overall financial plan.

If You Have a Large Lump Sum

Investing a large amount at one point exposes the investor to the market conditions prevailing at that time.

Depending on the investor’s circumstances, financial objectives, and risk profile, a phased approach may be considered instead of making a decision based entirely on a market-level valuation.

This is not a universal recommendation. The appropriate approach depends on individual circumstances.

If You Need the Money Soon

This may be the most important question.

If money is required for a near-term financial goal, the discussion should not be limited to whether Indian markets are expensive.

The more fundamental question is whether equity-market exposure is suitable for that particular goal and time horizon.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve Limited, we believe market valuation should be considered as part of a broader investment discussion rather than treated as the only factor.

For investors in Delhi NCR, investment decisions can be evaluated around financial goals, time horizon, risk profile, asset allocation, and the ability to remain invested through different market conditions.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve Limited provides mutual fund distribution services. Investors should evaluate the suitability of any investment based on their own circumstances and available product information.

You can contact GCIC Finserve to learn more about the services available and discuss your financial requirements.

For official market information, investors can refer to NSE India. For general mutual fund investor information, AMFI is another useful official industry resource.

FAQ

1. Are Indian markets too expensive right now?

Indian market valuations can appear elevated when compared with certain historical measures, but there is no single valuation metric that can conclusively determine whether the entire market is “too expensive.” Valuation should be considered alongside earnings, economic conditions, investment horizon and risk.

2. Should I stop my SIP because the market looks expensive?

Valuation alone may not be sufficient to decide whether to stop a long-term investment plan. Financial goals, investment horizon, risk tolerance and overall asset allocation should also be considered.

3. Is it better to wait for a market correction before investing?

A correction may provide lower prices, but there is no reliable way to know when a correction will occur, how large it will be or how long an investor may need to wait. Investment decisions should therefore not depend solely on predicting the next market correction.

4. Can expensive markets become reasonably valued without falling?

Yes. If corporate earnings grow while market prices remain relatively stable, valuation multiples can decline over time. However, future earnings growth is uncertain and should not be treated as a guaranteed outcome.

5. Do Indian markets always go up in the long run?

No. Equity markets can experience significant declines and prolonged periods of volatility. Historical performance should not be interpreted as a guarantee of future returns.

Final Word

Are Indian markets too expensive right now?

The honest answer is that valuation levels deserve attention, but the word “expensive” does not automatically mean “do not invest.”

For a long-term investor, the more useful questions are:

What is the goal?
How long can the money remain invested?
What level of risk can be accepted?
Is the portfolio appropriately diversified and aligned with the investor’s circumstances?

Market cycles will continue to change. Instead of attempting to predict every market high and low, investors can focus on the factors they can actually control: their goals, time horizon, risk tolerance and investment approach.

Disclaimer

This article is for educational purposes only and should not be considered investment advice or a recommendation. Past performance does not guarantee future returns. Investors should consider their financial goals, risk profile and investment horizon before investing. Mutual Fund investments are subject to market risks, read all scheme related documents carefully. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN: 272705).

Dollar vs INR: 7 Key Things Every Delhi NCR Investor Should Know in 2026

Dollar vs INR exchange rate and impact on Delhi NCR investors
Understanding how dollar vs INR movements can affect investors, imports and international investments.

Dollar vs INR has been impossible to miss lately. The Indian rupee has been trading around the ₹96-per-dollar level, with the rupee ending at ₹96.3150 against the US dollar on October 1, 2026.

But beyond the headline number, what does a weaker rupee actually mean for a Delhi NCR household or investor?

The impact goes far beyond foreign travel or shopping on international websites. Currency movements can affect oil prices, imported goods, overseas education costs, businesses and even the rupee value of investments held abroad.

Let’s understand dollar vs INR in simple terms.

What Does ₹96 to a Dollar Actually Mean?

When people say the dollar is at ₹96, it simply means you need approximately ₹96 to buy US$1.

For example, if the exchange rate was ₹85 earlier and moves to ₹96, the rupee has weakened against the dollar because you now need more rupees to purchase the same one dollar.

If the rate moves from ₹96 to ₹90, the rupee has strengthened.

The number itself is not automatically good or bad. What matters is why the exchange rate moved and how that movement affects your income, expenses, investments and financial goals.

For someone living in South Delhi, Gurgaon/Gurugram, Noida or elsewhere in Delhi NCR, the effect could show up through imported products, fuel costs, overseas education expenses or international investments.

Why Does Dollar vs INR Keep Moving?

The dollar vs INR exchange rate is influenced by demand and supply in the foreign-exchange market.

Several factors can influence this movement.

Oil Prices

India relies heavily on imported crude oil, and international oil transactions are largely denominated in US dollars.

When crude oil prices rise while the rupee weakens, the rupee cost of India’s energy imports can increase. This can put additional pressure on the currency and potentially affect inflation and transportation costs.

Recent market pressure on the rupee has also been associated with higher oil prices, global bond yields and foreign portfolio outflows.

US Interest Rates and Global Yields

US interest rates and global bond yields can influence international capital flows.

When dollar-denominated assets become relatively more attractive, some investors may move money towards those assets. Such flows can affect currencies including the Indian rupee.

Foreign Investment Flows

Money moving into or out of Indian financial markets can also influence demand for rupees and dollars.

Foreign investors are one part of the market, but they are not the only factor.

Inflation and Economic Conditions

Inflation, economic growth, trade flows, interest-rate differences and broader global economic conditions can all influence exchange rates.

This is why dollar vs INR cannot be explained by a single factor.

For official information on India’s monetary and foreign-exchange framework, investors can refer to the Reserve Bank of India.

How Foreign Investors Affect the Rupee

Imagine a foreign investor wants to buy ₹100 crore worth of Indian shares.

The investor generally needs to convert foreign currency into rupees to make the investment. This creates demand for rupees.

If the investor later sells those investments and converts the proceeds back into dollars, the flow moves in the opposite direction.

However, foreign investors are only one part of the foreign-exchange market. Indian importers, exporters, banks, companies, financial institutions and the Reserve Bank of India also participate in or influence the broader currency market.

So, a change in dollar vs INR should not automatically be attributed to foreign investors alone.

Why Should You Actually Care About Dollar vs INR?

You don’t need to travel abroad or own US stocks for the exchange rate to matter.

Everyday Expenses

India imports several goods, raw materials and energy products.

When imported items become more expensive in rupee terms, businesses may eventually pass some of those higher costs to consumers.

This does not mean every imported product will immediately become more expensive. The actual impact depends on the product, business costs, competition and other economic conditions.

Overseas Education

Consider a student planning to study in the United States.

A US$50,000 course would cost approximately:

  • At ₹85/USD: ₹42.5 lakh
  • At ₹96/USD: ₹48 lakh

The university fee has not changed.

The difference of approximately ₹5.5 lakh comes entirely from the exchange rate.

This is why families planning overseas education should consider currency movements as part of their financial planning.

International Travel

Flights, accommodation, tuition fees and other overseas expenses are ultimately affected by the exchange rate when you pay in a foreign currency.

A weaker rupee can therefore increase the rupee cost of expenses that are directly linked to foreign currencies.

A Weak Rupee Isn’t Always Bad

A weaker rupee does not affect every business in the same way.

Companies that earn a significant portion of their revenue in foreign currencies may benefit when those earnings are converted into rupees.

For example, suppose an Indian company earns US$10 million from overseas operations.

At ₹85/USD, that revenue converts to approximately ₹85 crore.

At ₹96/USD, the same US$10 million converts to approximately ₹96 crore, before considering other factors such as hedging, costs, taxes and the company’s operating expenses.

On the other hand, companies that depend heavily on imported raw materials, machinery or other inputs may face higher costs when the rupee weakens.

Therefore, rupee depreciation can affect businesses differently, depending on their business model and currency exposure.

Investors should therefore look beyond the exchange-rate headline and understand how a company’s revenues, costs and foreign-currency exposure work.

Has the Rupee Always Been This Weak?

The rupee’s long-term movement against the dollar has not been a straight line, but the annual average exchange rate has generally moved higher over the years.

According to OECD data published through FRED, the approximate annual averages were:

Year Average INR per USD
2021 ₹73.92
2022 ₹78.61
2023 ₹82.60
2024 ₹83.68
2025 ₹87.16

These are annual averages, not end-of-year exchange rates. FRED identifies the underlying source as OECD’s Main Economic Indicators.

The rupee subsequently moved around the ₹96-per-dollar level in late September and early October 2026, with ₹96.3150 recorded on October 1, 2026.

The important point is that historical currency movement does not tell us where the exchange rate will go next.

Exchange rates are influenced by many domestic and global factors and can move in either direction.

For investors interested in checking historical USD/INR data, the FRED series provides publicly available historical exchange-rate information.

What Does Dollar vs INR Mean for Your Investments?

Currency movements can become particularly important when you invest internationally.

Suppose you invest US$10,000 when the exchange rate is ₹85/USD.

Your investment costs approximately:

₹8.5 lakh

Now suppose the underlying investment does not change in dollar terms, but the rupee weakens to ₹96/USD.

The same US$10,000 would then be worth approximately:

₹9.6 lakh

The ₹1.1 lakh difference comes from the currency movement rather than investment performance.

However, the opposite can also happen.

If the rupee strengthens, the rupee value of the same foreign investment can decrease even if the investment’s foreign-currency value remains unchanged.

This is known as currency risk.

Therefore, international investing involves considering two separate factors:

  1. How the underlying investment performs.
  2. How the rupee moves against the foreign currency.

Currency movements can also affect Indian companies.

For example, an IT company earning significant dollar revenue may experience a different impact from a weaker rupee than a company that imports large quantities of raw materials.

Investors should therefore consider currency exposure as one part of understanding an investment—not as a standalone signal to buy or sell.

You can also explore GCIC Finserve’s investment solutions to understand the range of investment products available through the platform.

Should You Buy Dollars Because the Rupee Is Falling?

Not necessarily.

Seeing dollar vs INR near ₹96 and assuming that it will reach ₹100 can encourage investors to make decisions based purely on expectations about future currency movements.

That is effectively a bet on the direction of the exchange rate.

A more useful question is:

Do you actually have a financial need for dollar exposure?

For example, dollar exposure may be relevant if you are planning:

  • Overseas education
  • International travel
  • Future expenses in foreign currency
  • Long-term international investments
  • Diversification across geographical markets

Buying dollars purely because the rupee has recently fallen is a different decision and involves currency-market risk.

Investment decisions should instead consider financial goals, time horizon, risk profile, liquidity requirements and overall asset allocation.

How Can Delhi NCR Investors Think About Currency Risk?

For investors in South Delhi, Gurgaon/Gurugram, Noida and Ghaziabad, currency movements can become relevant in different ways.

A family planning a child’s education abroad may have a direct future dollar requirement.

A professional investing internationally may have foreign-currency exposure through an investment.

An investor holding Indian companies with substantial export revenues may be indirectly exposed to currency movements through the company’s business operations.

The same exchange-rate movement can therefore affect different people differently.

Instead of reacting to a headline such as “Dollar reaches ₹96,” investors can ask:

  • Do I have future expenses in dollars?
  • Do my investments have international exposure?
  • Are any of my investments exposed to foreign revenues or imported costs?
  • Does my overall portfolio have an appropriate level of diversification?
  • Has my financial goal or investment horizon changed?

A broader financial review can help put the exchange-rate movement into context. GCIC Finserve’s Financial Assessment page provides information about financial assessment and investment planning.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve Limited, we believe investors should look at dollar vs INR as one part of a much larger financial picture.

Currency movements should be considered alongside inflation, interest rates, oil prices, foreign investment flows, investment objectives, liquidity requirements and personal financial goals.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve focuses on helping investors understand available mutual fund options and associated risks.

The important distinction is that currency movement itself is not an investment signal.

For investors across Delhi NCR, the more useful question is:

“How could currency movements affect my own financial goals and investments?”

Understanding this can help investors focus on their financial objectives rather than reacting solely to short-term market headlines.

Frequently Asked Questions

Q1. Is ₹96 per dollar good or bad for India?

Neither in isolation. A weaker rupee can increase the rupee cost of imports while potentially benefiting some exporters and companies earning foreign-currency revenue. The overall economic impact depends on several factors.

Q2. Does a falling rupee mean the stock market will fall?

Not necessarily. Different companies can be affected differently by currency movements. Overall stock-market performance depends on many factors beyond the exchange rate.

Q3. Does a weaker rupee make my overseas investments more valuable?

It can increase their value when measured in rupees if the foreign investment itself remains unchanged. However, currency movements can work in either direction.

Q4. Should I invest in US stocks because the rupee is weakening?

Currency movement alone is not a sufficient reason to invest internationally. Investors should consider their financial goals, diversification requirements, risk profile, investment horizon and the risks of the specific investment.

Q5. Why does crude oil affect the dollar vs INR exchange rate?

India relies heavily on imported crude oil, and international oil transactions are largely denominated in US dollars. Higher oil prices can increase India’s dollar requirements, while a weaker rupee can make those imports more expensive in rupee terms.

Q6. Can the rupee strengthen again after falling?

Yes. Exchange rates can move in either direction and are influenced by domestic and global factors including oil prices, interest rates, capital flows, trade conditions and inflation. Past movement does not guarantee future direction.

Q7. Should I buy dollars as an investment?

Not automatically. Dollar exposure may have a legitimate purpose when linked to future foreign-currency expenses or an appropriate international allocation, but buying currency purely because its recent price has increased involves currency risk.

Final Word

The next time you see ₹96 to a dollar in the news, it is worth looking beyond the headline.

Dollar vs INR connects India’s economy with the rest of the world—from oil prices and imported goods to overseas education, international investments and the revenues of Indian companies.

You do not need to predict where the dollar will be next month.

What matters more is understanding why the exchange rate matters and where it may affect your own financial goals.

Understand your options. Know the risks. Make informed decisions.

Disclaimer

This article is intended solely for general investor awareness and educational purposes and should not be construed as investment advice, a recommendation, or a solicitation to buy or sell any security, mutual fund, investment product or currency. Mutual fund investments are subject to market risks, including the potential loss of capital, liquidity risk and market volatility. Please read all scheme-related documents and applicable product documents carefully before making an investment decision. Currency markets are influenced by several domestic and global factors and cannot be predicted with certainty. Investors should consider their financial objectives, risk profile, investment horizon and liquidity requirements before making investment decisions. This content should not be treated as tax, legal or regulatory advice. Where appropriate, consult a suitably qualified/registered professional.
GCIC Finserve Limited
AMFI-registered Mutual Fund Distributor (ARN-272705)

Investment products are subject to market risks. Please read all scheme-related documents and applicable product documents carefully before investing.

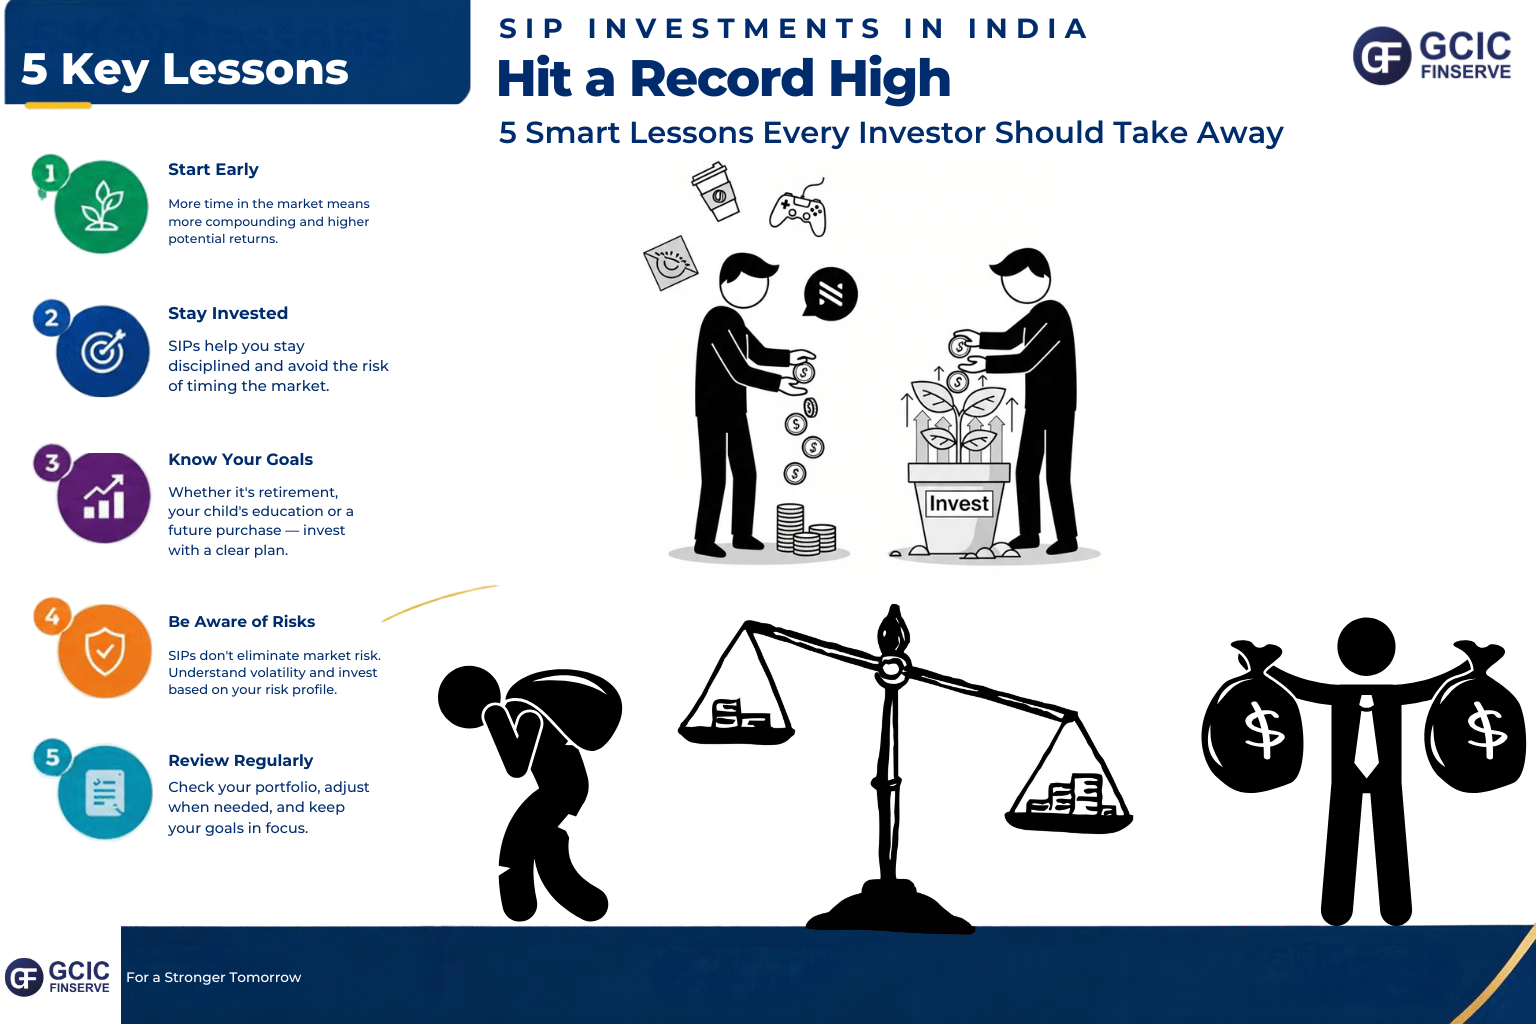
SIP Investments in India Hit a Record High: 5 Smart Lessons Every Delhi NCR Investor Should Take Away

SIP investments in India hit a record high with ₹32,297 crore monthly contribution in August 2026
India’s monthly SIP contribution reached a record ₹32,297 crore in August 2026, according to AMFI data.

SIP investments in India hit a record high of ₹32,297 crore in August 2026—the highest monthly SIP contribution ever recorded by AMFI. Ten years earlier, in August 2016, that number was just ₹3,497 crore. That’s a more than nine-fold jump in a decade. But behind this headline number is a much more interesting story for Delhi NCR investors: how Indians are quietly changing the way they think about money and what the cost of waiting to invest actually looks like.

Just How Big Is India’s SIP Boom?

The scale becomes clear when you place the numbers side by side. Monthly SIP contributions rose from ₹3,497 crore in August 2016 to ₹32,297 crore in August 2026. Outstanding SIP accounts reached 10.75 crore, with 10.02 crore actually contributing that month, and SIP assets under management touched ₹18.62 lakh crore. AMFI also recorded 66.40 lakh new SIP registrations in August alone, against 53.82 lakh SIPs that were discontinued or completed—a net addition of roughly 12.58 lakh accounts in just one month. SIP investments in India hitting a record high comes as part of a much larger increase in SIP participation over the past decade. 

The Bigger Mutual Fund Story Behind the Numbers

SIPs are just one part of a much larger transformation. India’s overall mutual fund industry AUM stood at ₹87.08 lakh crore at the end of August 2026, up roughly six-fold from ₹15.63 lakh crore in August 2016. Mutual fund folios have grown from 10.86 crore in August 2021 to 28.35 crore in August 2026—more than a two-and-a-half-fold increase in just five years, with roughly 21.62 crore of those folios in equity, hybrid, and solution-oriented schemes. For Delhi NCR households, this points to something bigger than a passing trend: organized, systematic investing is becoming the norm rather than the exception.

Why Has the SIP Become So Popular?

The appeal is part mathematics, part psychology. Ask someone to invest ₹12 lakh in one go, and it immediately raises hard questions—where will the money come from, is the market at the right level, and what if it falls right after? Ask instead, “Can you invest ₹10,000 a month?” and the decision suddenly feels manageable. According to AMFI, a SIP, is simply a method of investing a fixed amount periodically in a mutual fund scheme, helping investors stay disciplined without trying to time the market. It’s worth remembering: a SIP is a method of investing, not an investment product in itself—the underlying mutual fund is what actually carries the risk and return.

The Real FOMO Isn’t About Missing the Next Rally

The common fear is “the market went up; I should have invested earlier.” But that’s not the FOMO that matters most. Consider two people who both could have started investing ₹10,000 a month five years ago—one did, one kept waiting for the “right time.” Five years later, the person who started has something the other person can never buy back: five years of investment time. You can increase your SIP amount later, change your strategy later, or even recover from a bad investment choice later—but you cannot recover lost time.

What Does Starting Early Actually Do?

Here’s a simple illustration. Investing ₹10,000 every month for 20 years means a total contribution of ₹24 lakh, which at an illustrative 12% annualized return could grow to approximately ₹99 lakh. Wait five years, and investing the same ₹10,000 monthly for only 15 years brings the total contribution down to ₹18 lakh, with an illustrative corpus of around ₹50 lakh. (These are hypothetical illustrations, not guaranteed returns—actual outcomes depend on market performance, fund selection, costs, and taxes.) The investor who waited contributed just ₹6 lakh less, yet the eventual illustrative gap is far larger—because those extra five years of compounding matter more than the headline contribution amount.

The Other Side of the SIP Story

Record SIP contributions shouldn’t push anyone into investing blindly. When your colleague has an SIP, your friend has three mutual funds, and headlines talk about ₹32,297 crore flowing in every month, it’s easy to feel like you’re “behind”—but that’s FOMO, not a strategy. The fact that millions of Delhi NCR residents (and Indians nationwide) are investing through SIPs doesn’t tell you what to invest in, how much risk to take, or which mutual fund category actually suits your goal. It’s also worth remembering that an SIP doesn’t remove market risk—if you’re invested in equity mutual funds, your value can still fall when markets fall. A SIP simply means you keep investing on schedule; it doesn’t eliminate volatility.

3 Questions to Ask Before Starting a SIP

Before jumping in because “SIP investments in India hit a record high” made headlines, ask yourself:

  1. What am I actually investing for? Retirement, a child’s education, or a future purchase can each call for a different approach.
  2. How long can I realistically stay invested? Your time horizon should match the volatility you’re willing to sit through.
  3. How much can I invest without disrupting my monthly budget? A sustainable SIP beats an aggressive one you can’t maintain past a few months.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we see the SIP boom as a genuine shift in household financial behavior—but record flows should never replace a plan built around your own goals and risk profile. If you have a long-term goal and keep postponing simply because the timing never feels perfect, it’s worth understanding what that delay is actually costing you in lost compounding time. Connect with our team to understand which mutual fund categories might suit your goals. For the latest official SIP and mutual fund industry data, refer to AMFI India’s official reports.

FAQs

Q1. Are SIP investments in India really at a record high?

Yes—AMFI reported ₹32,297 crore in monthly SIP contributions in August 2026, the highest in its published series.

Q2. Does a record SIP contribution mean the stock market will rise? No. SIP flows reflect investor participation, not a reliable signal of future market direction.

Q3. Is it too late to start a SIP now that contributions are at record highs? 

There’s no universal answer—it depends on your goals, horizon, and risk tolerance. But waiting indefinitely for a “perfect” entry point can mean losing valuable compounding time.

Q4. Does starting a SIP early guarantee higher returns? 

No. Starting earlier gives your investment more time to potentially compound, but actual returns still depend on market performance and the underlying fund.

Final Word

SIP investments in India hitting a record high isn’t a signal to rush in—it’s a signal that Indian investors, including many across Delhi NCR, are increasingly treating investing as a recurring habit rather than a one-time event. You don’t need to feel FOMO because someone else started before you. But if investing genuinely fits your goals, understand what indefinite postponement is costing you. The market will offer many entry points over your lifetime—time is the one entry point you can’t revisit.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. The illustrations used are hypothetical. Please assess your own financial circumstances and, where appropriate, consult a qualified financial professional before investing. Data source: Association of Mutual Funds in India (AMFI), August 2026.

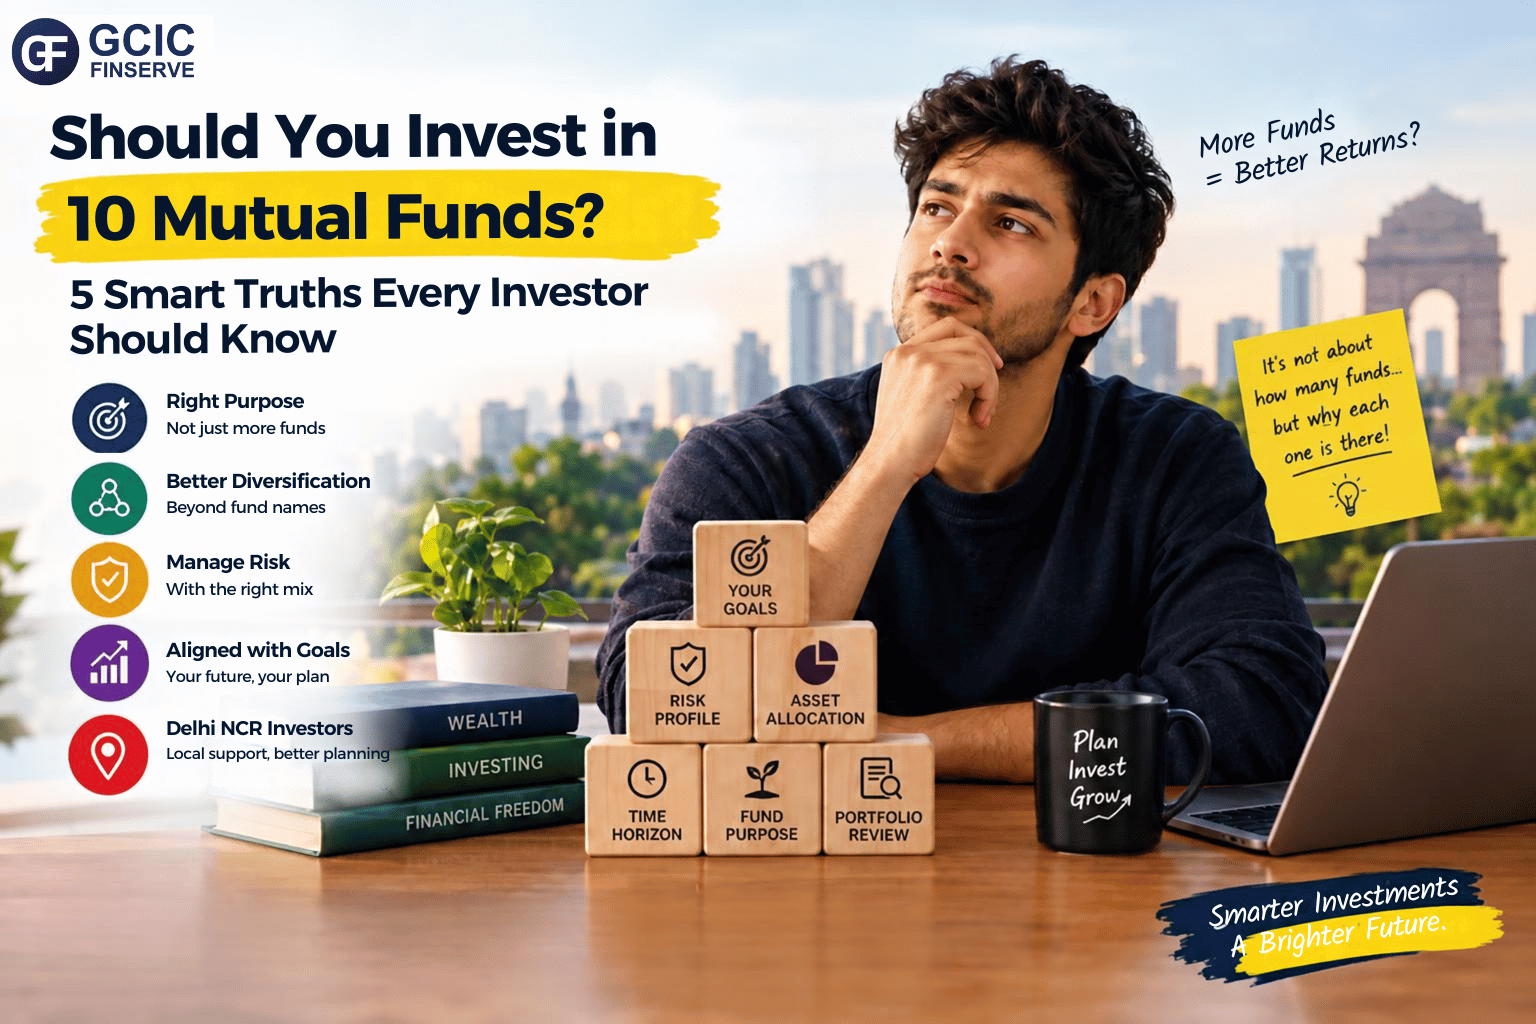
Should You Invest in 10 Mutual Funds? 5 Smart Truths Every Delhi NCR Investor Should Know

Should you invest in 10 mutual funds portfolio diversification
More mutual funds do not always mean better diversification.

Should you invest in 10 mutual funds to achieve proper diversification?
This is a common question among Delhi NCR investors who started with one or two SIPs and gradually added more funds.

One mid-cap fund here, one flexi-cap fund there, and another scheme recommended by a friend can eventually turn into a portfolio of ten or more mutual funds.

But owning ten mutual funds and being genuinely diversified are not necessarily the same thing.

The important question is not simply how many funds you own. It is whether each fund has a clear purpose and contributes meaningfully to your overall financial goals.

1. Why the Number of Funds Isn’t the Real Question

Diversification depends on what your investments actually hold, rather than the number of schemes in your portfolio.

For example, three large-cap mutual funds may invest in many of the same companies. Although the fund names and fund managers are different, their underlying holdings may overlap significantly.

This means a portfolio can appear diversified while still having considerable exposure to the same stocks or sectors.

Before adding another mutual fund, consider:

  • Underlying stock holdings
  • Overall asset allocation
  • Investment time horizon
  • Risk tolerance
  • The purpose of each fund
  • Your financial goals

Instead of focusing only on the number of schemes, understand how each investment fits into your complete portfolio.

2. How Mutual Fund Portfolios Quietly Become Overcrowded

Most investors do not intentionally decide to create a portfolio of ten mutual funds.

It often happens gradually. A fund generates strong recent returns, a new category becomes popular, or someone recommends another SIP. Over time, more schemes are added without reviewing the existing investments.

This can create two common challenges.

Fund Overlap

Different mutual funds may hold similar companies or sectors. This can reduce the diversification benefit you expected from owning multiple schemes.

Portfolio Complexity

When you own too many funds, it may become difficult to understand:

  • Where your money is invested
  • Which funds serve similar purposes
  • Whether your asset allocation remains suitable
  • Which investments need periodic review

A larger portfolio is not automatically a better portfolio. Clarity and suitability matter.

3. Should You Invest in 10 Mutual Funds?

There is no universal number of mutual funds that every investor should own.

The appropriate number depends on factors such as your investment amount, financial goals, risk profile, time horizon, and the role of each scheme.

An investor with multiple financial goals and a diversified asset allocation may have different requirements from someone who is starting their first SIP.

For many investors with relatively straightforward goals, adding funds only to increase the number of schemes may not provide meaningful benefits.

Before investing in another mutual fund, ask yourself:

What does this fund add to my existing portfolio that I do not already have?

If you cannot clearly explain its purpose, take time to review your existing investments before adding another scheme.

4. A Simple Test Before Adding Another Fund

Before deciding whether you should invest in 10 mutual funds or maintain a smaller portfolio, ask yourself these three questions.

1. Does the Fund Have a Different Purpose?

Does the new fund serve a different investment objective from your existing schemes?

Avoid adding a fund merely because it belongs to a different category or has recently delivered strong returns.

2. Does It Improve Diversification?

Review the fund’s underlying holdings and sector exposure. Different fund names do not necessarily mean different investments.

3. Would You Choose It Today?

Imagine that you were building your portfolio from scratch.

Would you still select this fund based on your current goals, risk profile, and investment strategy?

This question can help identify investments that remain in a portfolio simply because they were purchased in the past.

5. What If You Already Own 10 or More Funds?

If you already own ten or more mutual funds, do not rush to sell them only because the number appears high.

Instead, begin with a structured portfolio review.

Step 1: List All Your Funds

Prepare a list of your mutual funds, investment amounts, SIP contributions, and financial goals.

Step 2: Understand Each Fund’s Role

Identify whether each scheme is intended for long-term growth, a specific goal, diversification, or another purpose.

Step 3: Review Portfolio Overlap

Check whether multiple funds have similar holdings, sector exposure, or investment objectives.

Step 4: Review Your Asset Allocation

Understand your overall exposure to equity, debt, and other asset classes according to your financial needs and risk profile.

Step 5: Consider Consolidation Carefully

After reviewing the portfolio, you may identify opportunities to simplify your investments. Any decision to switch or redeem should consider factors such as taxes, exit loads, investment goals, and suitability.

The objective should not be reaching an arbitrary number of funds. The objective should be creating a portfolio that is understandable and aligned with your financial goals.

6. GCIC Finserve’s Approach for Delhi NCR Investors

At GCIC Finserve, we believe the right question is not simply, “Should you invest in 10 mutual funds?”

The more important question is:

Does every mutual fund in your portfolio have a clear reason to be there?

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve helps investors understand their portfolio structure, identify potential overlap, and review investment choices in the context of their financial goals.

Investors in South Delhi, Gurgaon, Noida, Ghaziabad, and other parts of Delhi NCR can consider reviewing their existing portfolio before adding another scheme.

You can explore our Financial Assessment page or visit our Contact Us page to learn more about the available services.

For investor education and mutual fund-related resources, visit AMFI India.

7. Frequently Asked Questions

Q1. Should you invest in 10 mutual funds?

It depends on your financial goals, risk profile, asset allocation, and the purpose of each fund. The number of schemes alone does not determine diversification.

Q2. How many mutual funds should I own?

There is no fixed number that applies to every investor. Choose investments based on your goals and whether each fund serves a distinct purpose.

Q3. Can different mutual funds hold the same stocks?

Yes. Different mutual funds can hold many of the same companies. This is known as portfolio overlap.

Q4. Should I sell my mutual funds if I own 10 or more?

Not automatically. Review each fund’s role, holdings, costs, tax implications, and suitability before making any decision.

Q5. How can I identify mutual fund overlap?

You can compare the underlying holdings, sector exposure, and investment objectives of your mutual funds. A portfolio review can help you understand similarities between schemes.

Final Word

The real question is not How many mutual funds should I own?

It is:

Does every fund in my portfolio have a clear reason to be there?

A portfolio with fewer funds may be easier to monitor, while a larger portfolio may be appropriate for certain investors and goals. What matters is whether your investments are suitable, understandable, and aligned with your financial plan.

Before adding your next mutual fund, review what you already own.

Disclaimer

This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Consider your financial goals, risk profile, and investment horizon before making investment decisions.
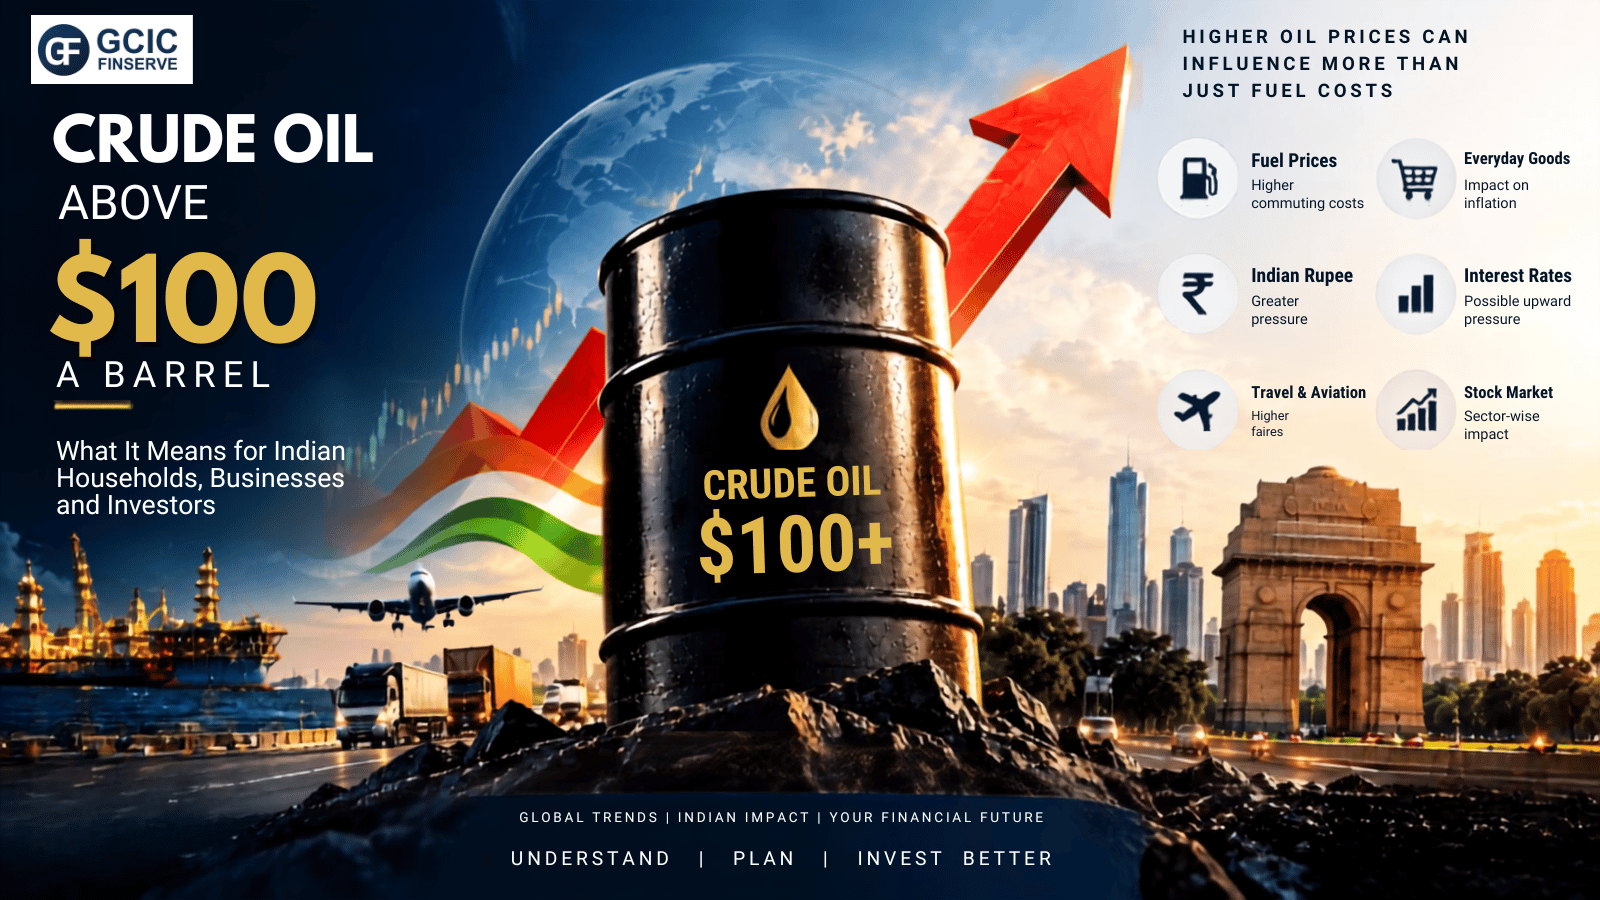
Crude Oil Above $100: 7 Powerful Effects on Indian Investors in 2026

Crude oil above $100 and its impact on Indian investors, inflation, fuel prices and the stock market
Crude oil above $100 can influence fuel costs, inflation, the Indian rupee, interest rates and different market sectors. Understanding these effects can help investors make informed decisions.

Crude oil above $100 a barrel is back in the financial headlines, and investors are once again watching what higher energy prices could mean for inflation, the rupee, interest rates, and the stock market.

For an everyday investor, however, the bigger question isn’t simply where crude oil is trading today. It is how sustained high oil prices can affect your household expenses, businesses, and investments.

Why Crude Oil Above $100 Matters to Indian Households

India relies heavily on imported crude oil. That means a sustained rise in international oil prices can have wider implications for the Indian economy.

When crude remains elevated for an extended period, the effects can travel through fuel costs, transportation, inflation, the rupee, and interest-rate expectations.

However, this does not automatically mean that the stock market will fall.

Markets respond to several factors at the same time, including corporate earnings, interest rates, global economic conditions, currency movements, and investor sentiment.

The important thing is understanding the potential chain reaction when oil prices remain high.

How Crude Oil Above $100 Reaches Your Wallet

Petrol, Diesel, and Daily Commuting

Fuel is one of the most visible connections between crude prices and everyday life.

If international crude prices remain elevated, fuel-related costs can come under pressure. This can affect not only personal vehicle expenses but also taxis, delivery services, and other forms of transportation.

For households across Delhi NCR, even relatively small increases in recurring expenses can add up over time.

Transportation and Everyday Goods

Before a product reaches a store in Gurugram, Noida, South Delhi, or another part of Delhi NCR, it may pass through several stages of transportation.

Higher energy and logistics costs can increase business expenses. Companies may absorb some of these costs or pass a portion on to consumers.

This is one way higher oil prices can contribute to broader inflationary pressure.

Flights and Travel

Airlines are particularly sensitive to fuel costs because aviation fuel is a major operating expense.

If crude oil remains elevated for an extended period, airlines may face higher costs, which can influence profitability and, depending on market conditions, travel prices.

The Inflation and Interest Rate Connection

This is where the crude-oil story becomes particularly important for investors.

Higher oil prices can increase transportation and production costs across different parts of the economy. If businesses pass these costs on to consumers, inflationary pressure can increase.

Persistent inflation can influence expectations around interest rates.

Higher interest rates can affect:

  • Home-loan EMIs
  • Business borrowing costs
  • Consumer spending
  • Corporate investment
  • Bond and fixed-income returns
  • Equity valuations

So the chain can look something like this:

Higher crude prices → higher input costs → inflationary pressure → interest-rate expectations → impact on businesses and markets

The actual outcome can vary depending on the broader economic environment.

Which Sectors Feel Crude Oil Above $100 the Most?

Not every business is affected in the same way.

Some sectors are more directly exposed to higher energy and transportation costs.

Sectors that may face greater pressure

  • Airlines
  • Logistics and transportation
  • Paint companies
  • Certain chemical companies
  • Energy-intensive manufacturers
  • Some automobile-related businesses

At the same time, some companies may have stronger pricing power or other factors that help offset higher costs.

Oil producers can also respond differently to higher crude prices than oil-consuming businesses.

This is why “crude oil above $100 = stock market fall” is too simplistic.

The real question is

Which companies are affected, and how significantly?

What Crude Oil Above $100 Means for Mutual Fund Investors

If you invest through mutual funds rather than directly buying individual stocks, you may wonder why crude oil matters to your portfolio.

The reason is simple: mutual funds may hold companies across sectors such as:

  • Banking
  • Technology
  • Consumer goods
  • Automobiles
  • Energy
  • Manufacturing
  • Infrastructure

Higher oil prices can affect these businesses differently.

Therefore, instead of reacting to a single market headline, investors should look at their actual portfolio, investment horizon, asset allocation and financial goals.

A portfolio review can often provide more useful information than reacting to one day’s movement in crude prices.

The Rupee Angle

Crude oil is traded internationally in US dollars.

When global oil prices rise, India’s import bill can increase. If the rupee is also under pressure against the US dollar, imported oil can become even more expensive in rupee terms.

This can create additional pressure on inflation and India’s external finances.

The broader chain can therefore look like

Crude oil above $100 → higher import costs → currency pressure → inflation concerns → interest-rate expectations → potential impact on businesses and markets

This is not a fixed formula, and several other economic factors influence each stage.

What Should Investors Actually Do?

The first response should be understanding, not panic.

A single headline about crude oil above $100 is rarely a sufficient reason to completely change a long-term investment strategy.

Instead, ask yourself:

  • Has my investment horizon changed?
  • Is my asset allocation still appropriate?
  • Am I overly concentrated in one sector?
  • Have my financial goals changed?
  • Do I have sufficient liquidity for near-term needs?
  • Have the fundamentals of the investments I own changed?

If the answer to these questions is no, reacting purely to an oil-price headline may not improve your investment outcome.

Domestic fuel prices are influenced by multiple factors beyond international crude, including taxes and other components of the pricing structure. For official petroleum-sector data and information, investors can refer to the Petroleum Planning & Analysis Cell (PPAC), Government of India.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, we believe financial information should go beyond explaining what happened in the markets.

Investors also need to understand why it matters to their financial goals.

Whether the headline is about crude oil, interest rates, inflation, or a market correction, a long-term financial plan should be built around your goals, risk profile, investment horizon, and overall financial situation rather than short-term market noise.

If you’re an investor in South Delhi, Gurugram, Noida, or the wider Delhi NCR region, reviewing your portfolio periodically can help you understand whether your investments continue to match your financial objectives.

Connect with GCIC Finserve to discuss your financial planning and investment requirements.

FAQs

1. Does crude oil above $100 mean the Indian stock market will fall?

No. Crude oil is one of many factors that influence the stock market. Earnings, interest rates, global economic conditions, currency movements, and investor sentiment also play important roles.

2. How does crude oil above $100 affect petrol prices in India?

Higher international crude prices can increase input costs, but domestic fuel prices also depend on factors such as taxes, refining costs, and other components. Therefore, the relationship is not necessarily one-to-one.

3. Should I change my mutual fund portfolio because crude oil is above $100?

Not automatically. Review your investment goals, risk profile, asset allocation, and the actual holdings of your funds before making significant changes.

4. Which sectors are most affected by high crude oil prices?

Airlines, logistics, transportation, and some chemical, paint, and manufacturing companies can face greater cost pressure. The impact varies by company and its ability to manage or pass on higher costs.

5. Can high crude oil prices affect the Indian rupee?

Yes. Higher oil prices can increase India’s import bill and demand for US dollars, potentially putting pressure on the rupee, although currency movements depend on many other factors as well. Recent market commentary has linked elevated oil prices with pressure on the rupee.

Final Word

Crude oil above $100 isn’t just a global financial headline.

For Indian households and investors, sustained high oil prices can potentially influence fuel costs, inflation, currency movements, interest-rate expectations, corporate profitability, and market sentiment.

But the objective shouldn’t be to predict every movement in the price of oil.

It should be to understand what actually matters for your financial plan.

Plan your investments around your goals—not around the day’s headline.

Disclaimer

This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Investors should consider their financial goals, risk profile and investment horizon and consult an appropriately qualified/registered financial professional where required.

Ronald Read Investor Story: The Janitor Who Built an $8 Million Fortune

Ronald Read investor story about a janitor who built an $8 million fortune through disciplined investing
The Ronald Read investor story highlights the power of disciplined investing, patience and long-term wealth creation.

The Ronald Read investor story is a powerful reminder that building substantial wealth isn’t always about earning a high income. Discipline, consistent saving, sensible investing, and time can also play an important role in long-term wealth creation.

Ronald Read worked as a gas station attendant and later worked as a part-time janitor at J.C. Penney in Brattleboro, Vermont. When he passed away in 2014 at age 92, his estate was reportedly worth around $8 million.

What made his story remarkable was not simply the amount of wealth he accumulated, but the quiet and disciplined way in which he built it.

Who Was Ronald Read?

Read came from modest beginnings, served in World War II, and lived a relatively simple life.

Over several decades, he saved and invested while maintaining a lifestyle far removed from the image many people associate with significant wealth.

After his death, a significant portion of his estate was donated to charitable causes, including Brattleboro Memorial Hospital and Brooks Memorial Library.

His story became a powerful example of how financial behavior can matter just as much as income.

The Real Lesson Behind the Ronald Read Investor Story

What makes this story relevant today is how the wealth was accumulated.

Read was reported to have invested in shares of established companies and held investments for long periods rather than constantly buying and selling based on short-term market movements.

His story illustrates an important principle:

Building wealth is not always about finding the next big opportunity. Sometimes it is about consistently making sensible decisions and giving them enough time to work.

A high salary can make investing easier, but income alone does not create financial security.

Saving, investing, controlling expenses, and maintaining a long-term perspective can all play an important role.

Key Takeaways for Indian Investors

1. Start early, even if you start small

Waiting until your income becomes significantly higher may mean missing valuable time for long-term investing and compounding.

Starting with an amount that fits your financial situation can help establish a consistent investing habit.

2. Think long term

Markets can experience periods of volatility, but long-term investing is fundamentally different from trying to predict every short-term movement.

3. Keep expenses under control

Living below your means can create more room for saving and investing.

4. Let time work

Compounding becomes increasingly powerful when investments remain invested for long periods.

For long-term investors, staying invested consistently may be more practical than trying to predict every short-term market movement.

How This Applies to Investors in Delhi NCR

For many families across Delhi NCR, wealth creation can sometimes feel like something reserved for people with very high incomes.

The Ronald Read story offers a different perspective.

A disciplined investment approach, when aligned with long-term financial goals, can help investors work toward building wealth over many years.

A Systematic Investment Plan (SIP) is a method of investing a fixed amount at regular intervals in a mutual fund scheme. The amount and investment approach should depend on an individual’s financial goals, time horizon, and risk tolerance.

The key lesson isn’t that every investor will achieve Ronald Read’s outcome.

It is that starting early, staying consistent, and giving investments sufficient time can make a meaningful difference.

Common Mistakes That Can Disrupt Long-Term Wealth Creation

  • Waiting for a higher salary before starting
  • Frequently changing investments because of market noise
  • Making decisions based purely on short-term market movements
  • Investing without clearly defined financial goals
  • Ignoring risk while focusing only on potential returns

Building Your Own Long-Term Wealth Plan

If you want to apply the principles from the Ronald Read story, start with a simple framework:

  1. Define your financial goals.
  2. Determine how much you can invest regularly.
  3. Choose investment options appropriate for your goals and risk tolerance.
  4. Stay focused on your long-term time horizon.
  5. Review your investments periodically rather than reacting to every market movement.

At GCIC Finserve, we help investors explore investment solutions based on their financial goals, investment horizon, and individual requirements.


The objective isn’t to chase every market opportunity. It is to build a disciplined approach that can remain aligned with your long-term financial journey.

Final Thoughts

The Ronald Read investor story isn’t simply about a million-dollar fortune. It is a story about discipline, patience, controlled spending, and the power of time.

You don’t need to look wealthy to be building wealth.

Sometimes the most important financial decisions are the ones nobody sees.

Want to explore investment solutions for your long-term goals?

Connect with GCIC Finserve.

FAQs

1. Who was Ronald Read?
Ronald Read was a US janitor and gas station attendant whose disciplined saving and long-term investing helped him build an estate reportedly worth around $8 million.

2. What can investors learn from the Ronald Read investor story?
The key lessons are starting early, investing consistently, controlling expenses, and staying focused on long-term goals.

3. Can Indian investors apply the lessons from Ronald Read’s story?
Yes. Indian investors can apply these principles through disciplined saving, suitable investment options, and a long-term approach aligned with their goals and risk tolerance.

4. How can GCIC Finserve help with long-term investment goals?
GCIC Finserve provides investment solutions based on financial goals, investment horizon, and individual requirements, helping investors explore suitable options for their long-term journey.


Disclaimer: Investments are subject to market risks. Past performance or historical examples do not guarantee future results. Please read all scheme-related documents carefully and consider your financial goals, investment horizon, and risk tolerance before investing.

Rupee hits highest level in August against US dollar on fading tariff risks, GST boost

Rupee hits highest level in August

Indian Rupee strengthened to its highest level in August against the US dollar on Tuesday, supported by easing concerns over additional US tariffs and expectations that proposed GST reforms could boost domestic economic growth.

The currency rose to as much as 87.2050 per US dollar, compared with 87.35 in the previous session, before settling at 87.2250. Analysts attributed the gains to renewed optimism following the Trump-Putin meeting and upcoming US-Ukraine talks, which Nomura said may reduce the likelihood of new sanctions or tariffs on India over its Russian oil purchases.

Prime Minister Narendra Modi’s proposed GST rationalisation is also lifting sentiment, with economists saying the measures could boost consumption and offset pressure from weak external demand.

While the rupee advanced, most Asian currencies slipped as US Treasury yields climbed, with the 10-year yield hitting a two-week high on Monday.

Apple leases 2.7 lakh sqft office in Bengaluru in ₹1,000-crore deal

Apple leases 2.7 lakh sqft office in Bengaluru

Apple Bengaluru office expansion has taken a major step forward with the US tech giant signing a 10-year lease for 2.7 lakh sq ft of premium office space at Embassy Zenith on Sankey Road, Vasanth Nagar.

Apple has taken the 5th to 13th floors of the property at a monthly rent of ₹6.31 crore, with the agreement commencing on April 3, 2025, and registered in July. The facility, expected to accommodate over 1,200 employees, has a carpet area of 1.96 lakh sq ft and a chargeable area of 2.69 lakh sq ft. The company has paid a ₹31.57-crore security deposit, ₹1.5 crore in stamp duty, and agreed to a 4.5% annual rent escalation. The property is owned by Mac Charles (India) Ltd, part of the Embassy Group.

This is Apple’s second major office in Bengaluru. In 2021, it leased 1.16 lakh sq ft at Prestige Minsk Square on Cubbon Road for ₹2.43 crore per month, with operations beginning in 2023. The company is also eyeing further expansion within Embassy Zenith.

Apple’s retail footprint is expanding as well. It has leased 8,000 sq ft at Phoenix Mall of Asia in north Bengaluru for its third India store, at an annual rent of ₹2.09 crore. The 10-year lease, signed in November 2024, will take effect from August 2025. Additional space has been secured at Oberoi Sky City Mall in Borivali, Mumbai (12,600 sq ft) and in Batrayanpura, Bengaluru (8,000 sq ft).

The expansion underscores Apple’s growing commitment to India, now a key manufacturing hub for the iPhone. On its Q3 FY25 earnings call, CEO Tim Cook expressed excitement over upcoming store launches and highlighted that most iPhones sold in the US are now made in India. Meanwhile, Foxconn, Apple’s key partner, has started producing the iPhone 17 at its new Devanahalli facility near Bengaluru.