Is Your Investment Portfolio Properly Diversified? 7 Simple Tests for Delhi NCR Investors

is your investment portfolio properly diversified
Seven practical tests to review portfolio diversification and concentration risk.

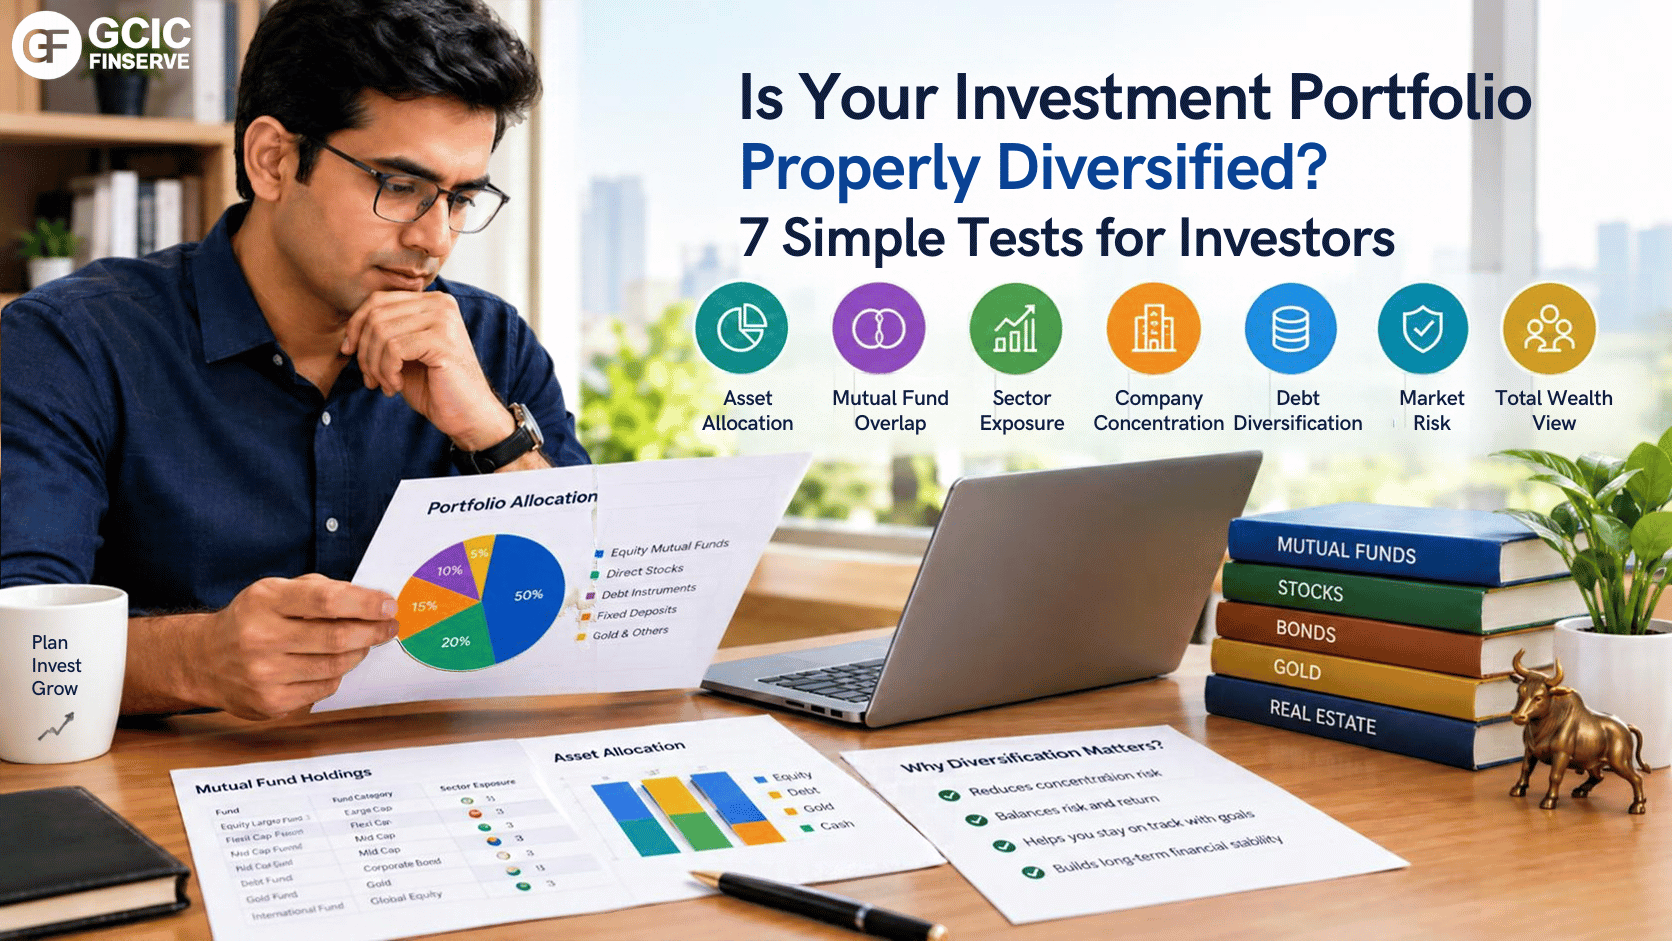
Is your investment portfolio properly diversified, or does it only look that way? Many investors believe they’re diversified because they own several mutual funds, a few stocks, some FDs, and maybe gold. But owning many investments doesn’t automatically mean you’re diversified. You could hold ten mutual funds and still have most of your money in the same companies. You could own several stocks and be heavily exposed to one sector. True diversification isn’t about how many investments you own; it’s about how many different risks your portfolio is exposed to.

What Does Diversification Actually Mean?

Diversification means spreading investments across assets, companies, sectors, and markets so your wealth doesn’t depend too heavily on one outcome. If you hold ten banking stocks, you own ten investments, but one sector downturn could hit most of your money at once. Compare that with ₹20 lakh split between equity, debt, and gold, with the equity spread across sectors. Different sources of risk and return make that portfolio much closer to genuine diversification. So is your investment portfolio properly diversified? Let’s find out.

Test 1: How Is Your Total Wealth Allocated?

Start with asset allocation before looking at individual products. Say you have ₹30 lakh in equity mutual funds, ₹10 lakh in direct stocks, ₹5 lakh in FDs, and ₹5 lakh in gold. That looks like four types of investments, but 80% of the portfolio is in equity. If your mutual funds also hold many of the same companies as your direct stocks, the real equity concentration could be even higher. Whether 80% equity is appropriate depends on your goals, time horizon, and risk capacity, but it’s worth knowing the real number.

Test 2: Are Your Mutual Funds Overlapping?

One of the most common problems in Indian portfolios is owning a large-cap fund, a flexi-cap fund, a multi-cap fund, a large and mid-cap fund, and an index fund, all at once. That sounds diversified, but these funds can hold many of the same large companies. This is called portfolio overlap: different investments with significant exposure to the same underlying securities. Some overlap is normal. The question is whether it’s intentional and reasonable, or whether adding more funds is just adding more complexity.

Test 3: Are You Too Dependent on One Sector?

You may own 30 or 40 different companies, but if nearly two-fifths of your equity sits in financial services, a prolonged downturn in that sector could hit your overall portfolio hard. A diversified portfolio doesn’t need equal exposure to every sector, but large concentrations should be a deliberate choice, not an accident.

Test 4: Are You Overexposed to One Company?

This matters especially for direct-stock investors. Suppose you hold ₹20 lakh in Company A directly and ₹60 lakh across mutual funds. If those funds also hold Company A, your actual exposure is higher than the ₹20 lakh you see in your demat account. When concentration is substantial, look through to the underlying holdings of your funds.

Test 5: Is Your Debt Portfolio Diversified Too?

Diversification isn’t only about equity. Two FDs and two corporate bonds are four investments, but you should still ask: who are the issuers, what’s the credit quality, when do they mature, are they exposed to the same economic risks, and how much of your wealth depends on one institution? Several debt instruments don’t make a diversified portfolio if most of the money rests on a handful of issuers.

Test 6: What Happens If the Market Falls?

One of the simplest tests is to imagine stress. If equity markets fall sharply, how much of your total wealth falls with them? If almost everything you own is linked directly or indirectly to equity, you may have more exposure than you realise. Then ask: what if interest rates rise (important for longer-duration debt), what if the sector I’m heavily in faces a downturn, and what if I need a large amount of money during a correction? These questions reveal risks that a simple list of investments won’t show. Also remember that diversification is about time too: money needed for a child’s education in two years needs more attention to stability and liquidity than money you won’t touch for 15 years.

Test 7: Is Your Total Family Wealth Diversified?

For many Indian families, real estate is a large share of wealth. If your financial portfolio looks diversified but three properties make up 70% of family wealth, you’re still concentrated in real estate. The same applies to business owners: with a ₹10 crore business and ₹2 crore of other investments, family wealth is still heavily dependent on the business, and possibly on one industry for both income and net worth. Investment-portfolio diversification and total-wealth diversification aren’t always the same thing.

Two Portfolios, Same ₹50 Lakh

Portfolio A has a large-cap fund, a flexi-cap fund, an index fund, a mid-cap fund, direct stocks, and an FD. It looks diversified because there are six investments, but the equity portion may overlap heavily. Portfolio B holds diversified equity, debt and FDs, gold, and liquid investments, with fewer products but potentially wider spread across asset classes. Which suits a particular investor depends on goals and risk profile, but the principle holds: more products don’t automatically mean more diversification.

When Does a Portfolio Need Rebalancing?

Even a well-diversified portfolio drifts. Start with 60% equity, 30% debt, and 10% gold, and after a strong equity run it could become 75% equity, 18% debt, and 7% gold. You didn’t choose that extra equity risk; the market did. Rebalancing means bringing the portfolio back toward an allocation that fits your objectives and risk profile. It doesn’t mean selling everything that has done well. Note too that diversification reduces concentration risk but can’t eliminate losses: in a broad global decline, several asset classes can fall together.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we help Delhi NCR investors understand how their mutual fund holdings fit together, including category choices and overlap. Connect with our team to discuss your mutual fund holdings. For official fund category and portfolio disclosure information, refer to AMFI India.

FAQs

Q1. How many mutual funds should I own to be diversified? There’s no fixed number. Adding funds with similar holdings may increase complexity without improving diversification.

Q2. Is owning different mutual fund categories enough? Not necessarily. Different categories can still have overlapping holdings, so actual portfolio exposure matters more than fund names.

Q3. How can I check mutual fund overlap? Compare the underlying holdings of your funds and spot companies and sectors that appear repeatedly. Many portfolio tools offer overlap analysis.

Q4. Can too much diversification be a problem? Yes. Too many investments can make a portfolio hard to monitor, create overlap, and obscure the actual risks.

Q5. Should I rebalance every year? Not necessarily. It depends on how far your allocation has drifted from the intended one, and a periodic review can show when rebalancing may be appropriate.

Final Word

A properly diversified portfolio isn’t the one with the most investments. It’s one where your money is deliberately spread across assets, companies, sectors, and risks to match your goals. The real test: if one company fails, one sector struggles, rates rise, or equity markets fall, how much of your overall wealth is affected? That tells you far more than the number of statements in your drawer.

Disclaimer: This article is for general educational and informational purposes only and should not be construed as investment, financial, or tax advice. There is no single asset allocation or diversification strategy suitable for every investor. Mutual fund and other market-linked investments are subject to market risks, and diversification does not guarantee profits or eliminate losses. Please consider your goals, horizon, liquidity needs, and risk profile, and consult a qualified financial professional where appropriate.
Are Indian Markets Too Expensive Right Now? 5 Honest Answers Every Delhi NCR Investor Should Know

Indian market valuation and investment planning for Delhi NCR investors
Understanding Indian market valuations, investment risks and long-term financial planning.

Are Indian markets too expensive right now? It is a question many investors ask when stock-market valuations appear high or the Nifty 50 is trading near elevated levels.

The concern is understandable. Nobody wants to invest a large amount just before a major market correction. At the same time, waiting indefinitely for markets to become “cheap” can also create its own challenges.

The more useful question is not simply whether Indian markets look expensive. It is whether current valuations are supported by earnings, business growth, economic conditions and your own investment horizon.

For investors in Delhi NCR and elsewhere, understanding this difference can help bring more perspective to market decisions.

What Does “Expensive” Mean in the Stock Market?

When investors describe a market as expensive, they are generally talking about valuation.

One commonly used measure is the Price-to-Earnings (P/E) ratio. It compares a company’s share price with its earnings per share.

For example, if a company earns ₹10 per share and its share price is ₹200, its P/E ratio is 20.

But valuation should not be viewed in isolation.

A company or market trading at a higher valuation may still have the potential to grow its earnings over time. Similarly, a low valuation does not automatically mean that an investment is attractive.

Therefore, when asking, “Are Indian markets too expensive right now?” investors should look beyond a single valuation number and consider earnings growth, economic conditions, business fundamentals, and their own financial objectives.

Investors can also review their broader financial assessment and investment planning before making decisions based on short-term market movements.

1. Are Indian Markets Too Expensive Right Now?

There is no single valuation measure that can conclusively tell investors whether the entire Indian market is “too expensive.”

Indian equities can trade at valuations above or below their historical averages at different points in the market cycle. Valuations can also differ significantly between sectors and individual companies.

For this reason, describing the entire market as either “cheap” or “expensive” can oversimplify a much more complicated situation.

A better approach is to consider questions such as:

  • Are corporate earnings growing?
  • Are current valuations supported by business fundamentals?
  • What are the broader economic conditions?
  • How much volatility can you tolerate?
  • When will you actually need the invested money?

Market valuation is therefore one factor to consider, not a standalone investment decision.

For official market information, investors can refer to NSE India and its publicly available market and research resources.

2. Why Waiting for a Correction Can Be Difficult

Suppose you believe the market is expensive and decide to wait for a correction.

The market may fall eventually. But it may also remain elevated or move higher before any meaningful correction occurs.

This creates a common dilemma.

If markets rise while you remain on the sidelines, you may later feel pressure to invest at an even higher level. If markets fall sharply after you invest, you may question whether waiting would have been better.

The important point is that short-term market movements are difficult to predict consistently.

Even when valuations appear stretched, investors cannot know exactly when a correction will occur or how deep it will be.

That is why investment decisions are generally better considered in the context of financial goals, time horizon, and risk tolerance rather than a single prediction about the next market move.

3. Can a Market Grow Into Its Valuation?

Yes, this can happen.

Consider a simplified example.

A company earns ₹10 per share and trades at ₹200, giving it a P/E of 20.

If the company’s earnings increase to ₹15 per share while its share price remains at ₹200, its P/E would fall to approximately 13.3.

The share price did not fall. Instead, the underlying earnings increased.

Real markets are much more complex because prices reflect expectations about future earnings, interest rates, economic conditions, and investor sentiment.

Nevertheless, the example demonstrates an important point:

Today’s valuation does not by itself determine tomorrow’s market return.

A market that appears expensive today can become more reasonably valued if earnings grow. Equally, valuations can remain elevated or become more stretched if investor expectations rise faster than underlying earnings.

4. What Should Long-Term Investors Focus On?

A short-term market participant may ask:

“What will the market do next?”

A long-term investor may need to ask a different question:

“What am I investing for, and how long can I remain invested?”

Equity markets can experience substantial declines over shorter periods. Investors may therefore experience periods of volatility, sometimes lasting for extended periods.

This is why an investment horizon matters.

Money required for a near-term financial commitment may need to be treated differently from money being invested for a long-term goal.

Instead of trying to predict every market high and low, long-term investors can focus on:

  • Financial goals
  • Investment horizon
  • Risk tolerance
  • Asset allocation
  • Diversification
  • Portfolio suitability
  • Ability to remain invested during market volatility

Historical market performance can provide context, but it does not guarantee future returns.

If you are reviewing your existing investment approach, you can also explore GCIC’s financial assessment to understand the broader factors that may need to be considered.

5. How Regular Investing Can Help Manage Timing Risk

Regular investing can be one way of reducing the pressure associated with trying to identify the “perfect” entry point.

When markets are higher, a fixed investment amount buys fewer units. When prices are lower, the same amount can buy more units.

This does not remove market risk and does not guarantee profits.

However, for investors whose financial goals and risk profile are suitable for regular investing, investing systematically can reduce dependence on making a single large timing decision.

The appropriate approach can vary from one investor to another, particularly when dealing with a significant lump sum.

For general investor education and mutual fund-related information, investors can also refer to AMFI.

What Should You Consider When Markets Look Expensive?

There is no universal answer.

If You Are Already Invested

A higher market valuation by itself may not necessarily mean that an investor should make a wholesale change to their portfolio.

It may be more useful to review whether the existing asset allocation remains aligned with the investor’s financial goals, investment horizon and risk profile.

If You Invest Regularly

Market valuations can be one factor to monitor, but stopping a long-term investment plan solely because markets appear expensive may not be appropriate for every investor.

The decision should be considered in the context of the investor’s objectives and overall financial plan.

If You Have a Large Lump Sum

Investing a large amount at one point exposes the investor to the market conditions prevailing at that time.

Depending on the investor’s circumstances, financial objectives, and risk profile, a phased approach may be considered instead of making a decision based entirely on a market-level valuation.

This is not a universal recommendation. The appropriate approach depends on individual circumstances.

If You Need the Money Soon

This may be the most important question.

If money is required for a near-term financial goal, the discussion should not be limited to whether Indian markets are expensive.

The more fundamental question is whether equity-market exposure is suitable for that particular goal and time horizon.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve Limited, we believe market valuation should be considered as part of a broader investment discussion rather than treated as the only factor.

For investors in Delhi NCR, investment decisions can be evaluated around financial goals, time horizon, risk profile, asset allocation, and the ability to remain invested through different market conditions.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve Limited provides mutual fund distribution services. Investors should evaluate the suitability of any investment based on their own circumstances and available product information.

You can contact GCIC Finserve to learn more about the services available and discuss your financial requirements.

For official market information, investors can refer to NSE India. For general mutual fund investor information, AMFI is another useful official industry resource.

FAQ

1. Are Indian markets too expensive right now?

Indian market valuations can appear elevated when compared with certain historical measures, but there is no single valuation metric that can conclusively determine whether the entire market is “too expensive.” Valuation should be considered alongside earnings, economic conditions, investment horizon and risk.

2. Should I stop my SIP because the market looks expensive?

Valuation alone may not be sufficient to decide whether to stop a long-term investment plan. Financial goals, investment horizon, risk tolerance and overall asset allocation should also be considered.

3. Is it better to wait for a market correction before investing?

A correction may provide lower prices, but there is no reliable way to know when a correction will occur, how large it will be or how long an investor may need to wait. Investment decisions should therefore not depend solely on predicting the next market correction.

4. Can expensive markets become reasonably valued without falling?

Yes. If corporate earnings grow while market prices remain relatively stable, valuation multiples can decline over time. However, future earnings growth is uncertain and should not be treated as a guaranteed outcome.

5. Do Indian markets always go up in the long run?

No. Equity markets can experience significant declines and prolonged periods of volatility. Historical performance should not be interpreted as a guarantee of future returns.

Final Word

Are Indian markets too expensive right now?

The honest answer is that valuation levels deserve attention, but the word “expensive” does not automatically mean “do not invest.”

For a long-term investor, the more useful questions are:

What is the goal?
How long can the money remain invested?
What level of risk can be accepted?
Is the portfolio appropriately diversified and aligned with the investor’s circumstances?

Market cycles will continue to change. Instead of attempting to predict every market high and low, investors can focus on the factors they can actually control: their goals, time horizon, risk tolerance and investment approach.

Disclaimer

This article is for educational purposes only and should not be considered investment advice or a recommendation. Past performance does not guarantee future returns. Investors should consider their financial goals, risk profile and investment horizon before investing. Mutual Fund investments are subject to market risks, read all scheme related documents carefully. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN: 272705).

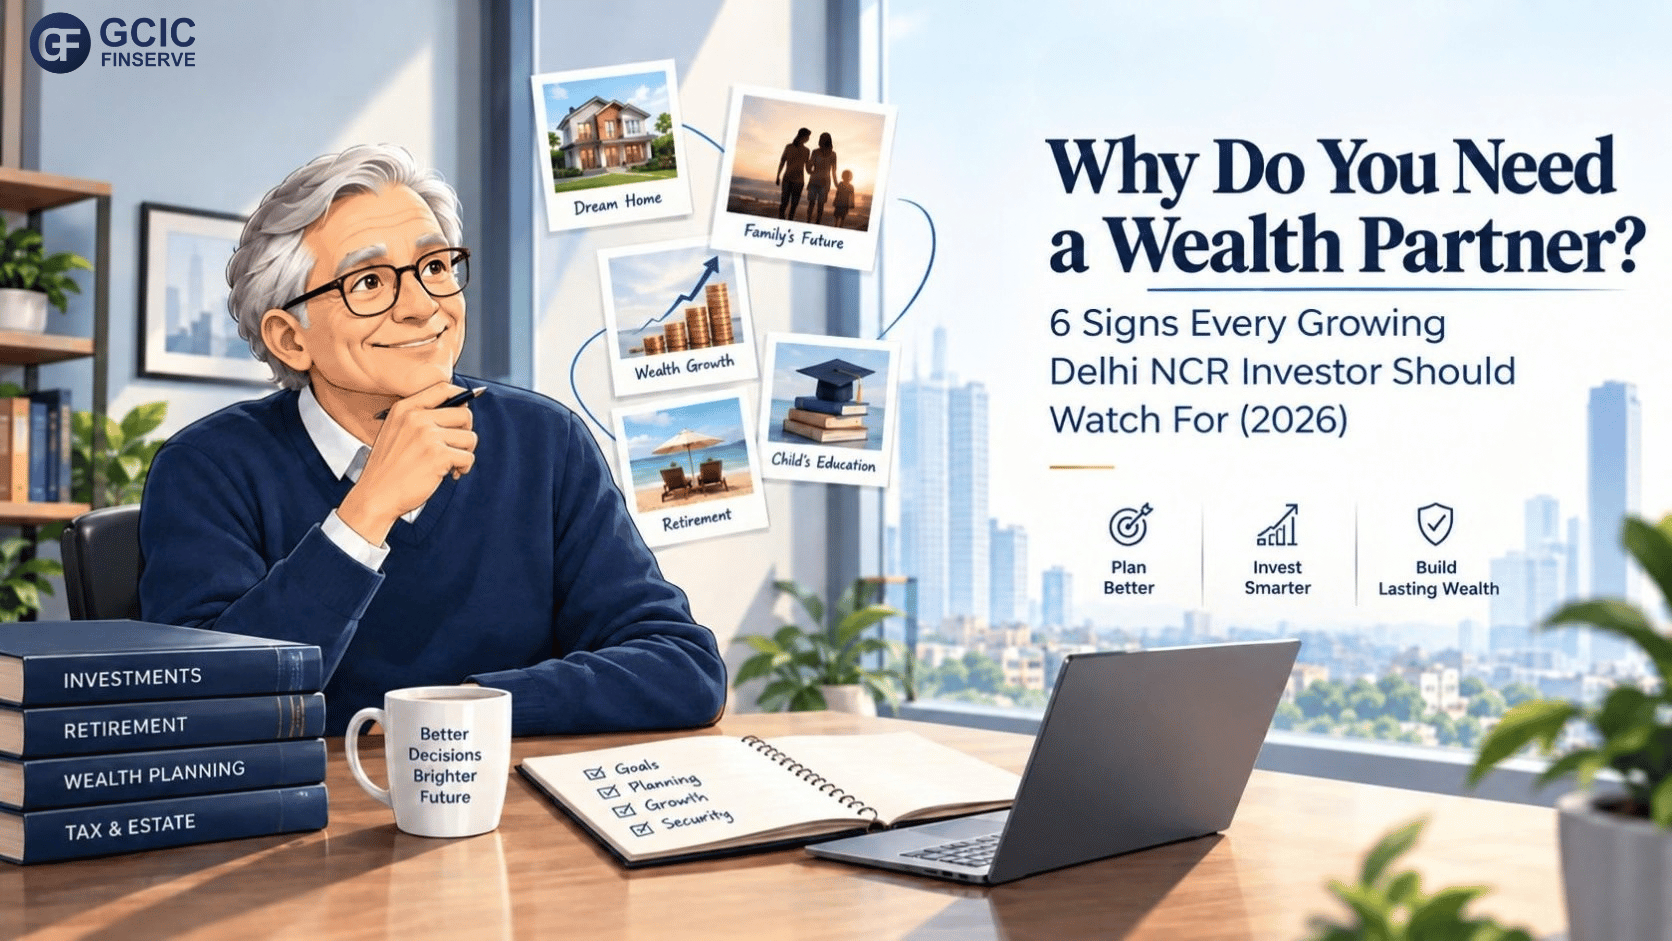
Why Do You Need a Wealth Partner? 6 Signs Every Growing Delhi NCR Investor Should Watch For

Wealth partner helping an investor organize and manage multiple financial goals
A wealth partner can help bring investments, goals, and financial decisions together.

Why do you need a wealth partner? It’s a question that rarely comes up when you’re just starting out—a few SIPs, a bank account, maybe an insurance policy, and time doing the rest of the work. But as income grows across Delhi NCR’s fast-moving professional and business circles, financial lives rarely stay that simple. Money starts sitting across different institutions—a business, property, insurance, and retirement assets—and the question quietly shifts from “where should I invest?” to “how should all of my wealth work together?”

What Does a Wealth Partner Actually Mean?

At its core, the idea behind why you need a wealth partner comes down to one distinction: managing investments versus managing wealth. An investment is one piece of your financial life; understanding how all those pieces fit together—liquidity, risk, goals, asset allocation—is the broader picture.

Choosing a mutual fund answers where to invest ₹10 lakh. A wider conversation also asks, how much of your total wealth should stay liquid? Are you overexposed to one asset class? How should the portfolio evolve as goals get closer?

Why Do You Need a Wealth Partner as Your Finances Grow?

India’s investment landscape has expanded dramatically, which is part of why the wealth-partner conversation matters more today. According to AMFI India, the mutual fund industry’s assets under management grew from ₹15.63 lakh crore in August 2016 to ₹87.08 lakh crore by August 2026, with folios crossing 28.35 crore.

Investors today can choose from mutual funds, PMS, AIFs, SIFs, bonds, FDs, REITs, and InvITs—more choice, but not necessarily easier decisions.

The real challenge isn’t accessing investments anymore; it’s deciding which ones actually deserve a place in your financial life.

From Products to a Portfolio

Consider someone holding ten different mutual funds. Each may look reasonable individually, but that alone doesn’t confirm the portfolio makes sense—there could be significant overlap, too much exposure to one segment, or insufficient liquidity.

This is exactly where the question of why you need a wealth partner starts to matter: someone who looks beyond individual products and asks what the portfolio as a whole is actually trying to achieve.

From Investments to Decisions

Markets rise and fall, interest rates shift, and personal circumstances change. The hard part usually isn’t knowing what happened—it’s deciding what to do about it.

Should you rebalance? Deploy a cash surplus now or gradually? Move money just because something else recently performed better?

A structured process around these decisions—rather than reacting to headlines—is one of the clearest reasons investors consider professional financial support as their financial life becomes more layered.

What Areas Does This Kind of Support Cover?

The exact scope varies, but typically spans portfolio planning, asset allocation, goal planning, portfolio reviews, identifying concentration or overlap, risk and liquidity management, and rebalancing.

As financial circumstances become more complex, family wealth and succession considerations may also become relevant. Tax, legal, and estate matters usually require separate specialist professionals—coordination across these areas can still be an important part of the broader financial picture.

6 Signs You Might Need a Wealth Partner

  1. Your financial situation has become hard to track on your own—multiple institutions, products, or accounts.
  2. Your investable surplus has grown significantly and now needs a clearer structure.
  3. You have both business and personal wealth that rarely get looked at together.
  4. You’re approaching a major goal—retirement, a child’s education, or a large purchase.
  5. You’re unsure whether your portfolio is genuinely diversified or just spread across many products.
  6. You find yourself making investment decisions reactively, based on headlines rather than a plan.

The real question isn’t “How much money do I have?”—it”‘s “How much financial complexity am I comfortable managing myself?”

You Don’t Need One Just Because You Have Money

This distinction matters.

If your finances are straightforward and you have the time, interest, and discipline to manage everything yourself, doing it independently can work perfectly well.

The need typically emerges from complexity, not net worth alone. Someone with modest wealth but several overlapping goals may value structured support more than someone financially sophisticated with a simple, well-understood portfolio.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705) and APMI-registered PMS Distributor (APRN-08140), we help Delhi NCR investors and families understand their mutual fund and PMS investment options and how these may fit within their broader financial goals and circumstances.

The appropriate approach depends on individual objectives, risk profile, investment horizon, and financial situation.

Connect with our team to discuss your investment requirements and available options.

FAQs

Q1. Is a wealth partner the same as a mutual fund distributor?

Not necessarily. A mutual fund distributor primarily facilitates and services mutual fund investments, while “wealth partner” is a broader term. The exact services and regulatory permissions depend on the specific entity and its registrations.

Q2. Is a wealth partner only for high-net-worth individuals?

No. The need depends more on the complexity of your finances than your net worth alone. Someone with modest wealth but several goals may value structured support just as much.

Q3. Does working with a wealth partner mean giving up control of my investments?

Not necessarily. The structure depends on the services involved. Investors can retain decision-making authority while using professional support for research, planning, and review.

Q4. Can a wealth partner guarantee better investment returns?

No. Returns can never be guaranteed. The value of professional support can lie in portfolio construction, risk management, goal alignment, and disciplined decision-making—not guaranteed return maximization.

Q5. When should I start thinking about this kind of support?

There’s no fixed number. A useful trigger is increasing complexity: more assets, more goals, or more decisions than you’re comfortable managing alone.

Final Word

Why do you need a wealth partner? Ultimately, it comes down to one shift: from making money work to making all of your money work together.

As your financial life across Delhi NCR grows—more assets, more goals, more decisions—the value isn’t necessarily in finding the next best investment alone, but in keeping every piece of your financial picture aligned with what you actually want it to achieve.


Disclaimer: This article is intended for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a solicitation to invest in any particular financial product. Investment decisions should be based on individual financial circumstances, objectives, risk profile, and investment horizon. Past performance is not indicative of future results. Please independently evaluate products and, where appropriate, seek advice from suitably qualified and regulated professionals.