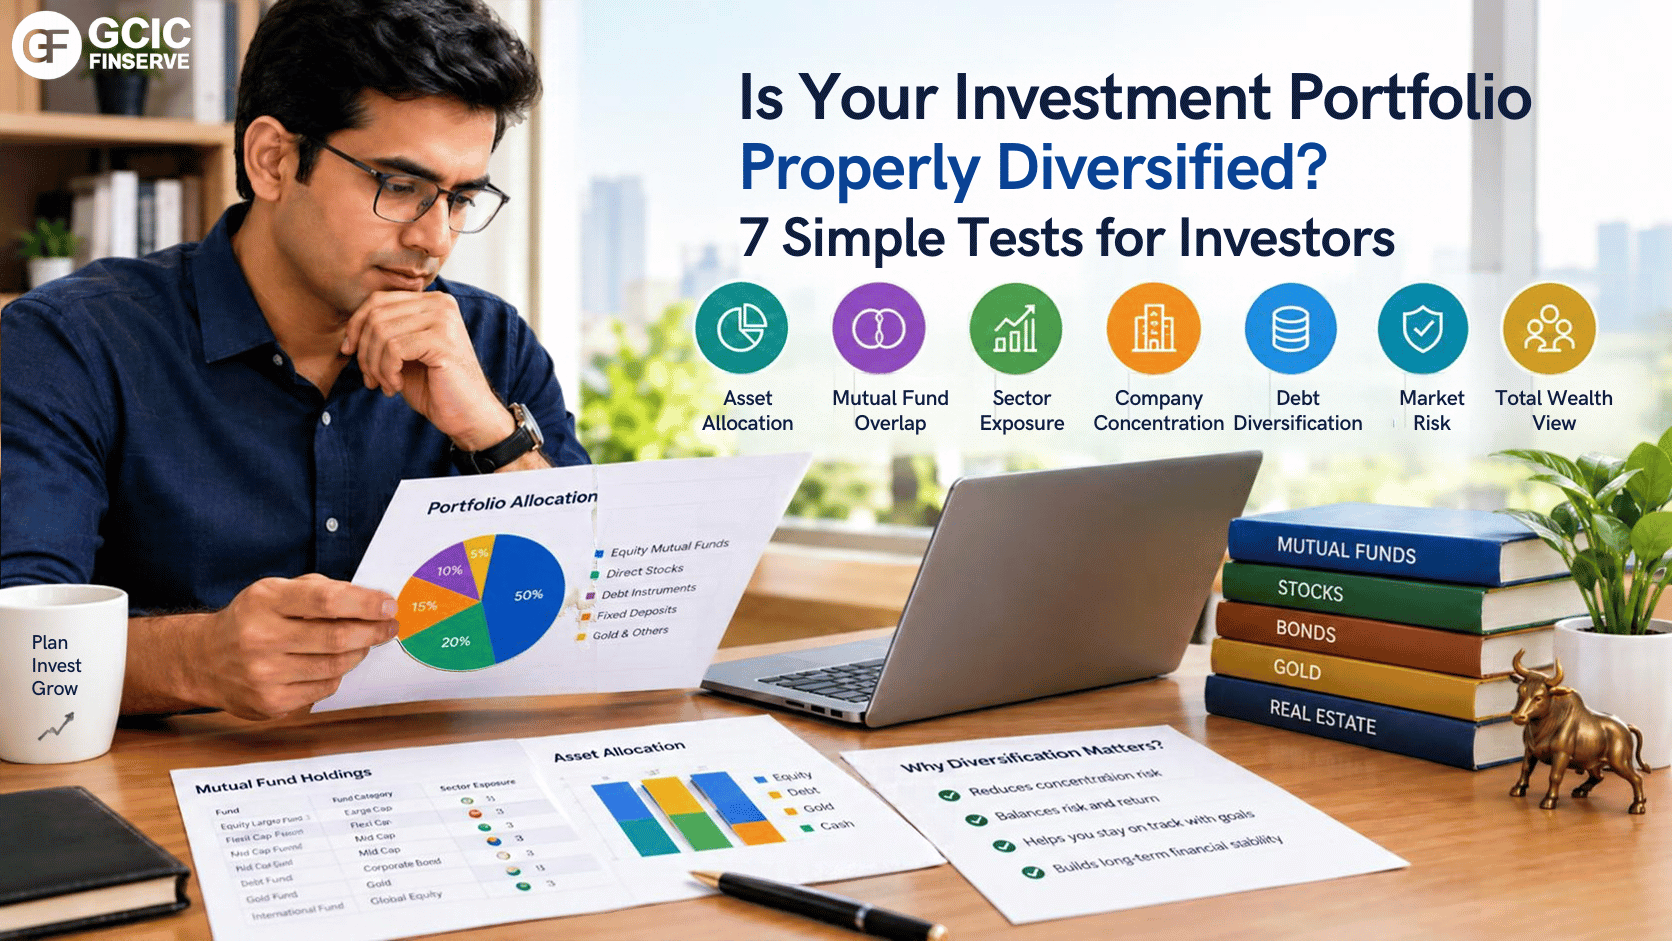
Is your investment portfolio properly diversified, or does it only look that way? Many investors believe they’re diversified because they own several mutual funds, a few stocks, some FDs, and maybe gold. But owning many investments doesn’t automatically mean you’re diversified. You could hold ten mutual funds and still have most of your money in the same companies. You could own several stocks and be heavily exposed to one sector. True diversification isn’t about how many investments you own; it’s about how many different risks your portfolio is exposed to.
What Does Diversification Actually Mean?
Diversification means spreading investments across assets, companies, sectors, and markets so your wealth doesn’t depend too heavily on one outcome. If you hold ten banking stocks, you own ten investments, but one sector downturn could hit most of your money at once. Compare that with ₹20 lakh split between equity, debt, and gold, with the equity spread across sectors. Different sources of risk and return make that portfolio much closer to genuine diversification. So is your investment portfolio properly diversified? Let’s find out.
Test 1: How Is Your Total Wealth Allocated?
Start with asset allocation before looking at individual products. Say you have ₹30 lakh in equity mutual funds, ₹10 lakh in direct stocks, ₹5 lakh in FDs, and ₹5 lakh in gold. That looks like four types of investments, but 80% of the portfolio is in equity. If your mutual funds also hold many of the same companies as your direct stocks, the real equity concentration could be even higher. Whether 80% equity is appropriate depends on your goals, time horizon, and risk capacity, but it’s worth knowing the real number.
Test 2: Are Your Mutual Funds Overlapping?
One of the most common problems in Indian portfolios is owning a large-cap fund, a flexi-cap fund, a multi-cap fund, a large and mid-cap fund, and an index fund, all at once. That sounds diversified, but these funds can hold many of the same large companies. This is called portfolio overlap: different investments with significant exposure to the same underlying securities. Some overlap is normal. The question is whether it’s intentional and reasonable, or whether adding more funds is just adding more complexity.
Test 3: Are You Too Dependent on One Sector?
You may own 30 or 40 different companies, but if nearly two-fifths of your equity sits in financial services, a prolonged downturn in that sector could hit your overall portfolio hard. A diversified portfolio doesn’t need equal exposure to every sector, but large concentrations should be a deliberate choice, not an accident.
Test 4: Are You Overexposed to One Company?
This matters especially for direct-stock investors. Suppose you hold ₹20 lakh in Company A directly and ₹60 lakh across mutual funds. If those funds also hold Company A, your actual exposure is higher than the ₹20 lakh you see in your demat account. When concentration is substantial, look through to the underlying holdings of your funds.
Test 5: Is Your Debt Portfolio Diversified Too?
Diversification isn’t only about equity. Two FDs and two corporate bonds are four investments, but you should still ask: who are the issuers, what’s the credit quality, when do they mature, are they exposed to the same economic risks, and how much of your wealth depends on one institution? Several debt instruments don’t make a diversified portfolio if most of the money rests on a handful of issuers.
Test 6: What Happens If the Market Falls?
One of the simplest tests is to imagine stress. If equity markets fall sharply, how much of your total wealth falls with them? If almost everything you own is linked directly or indirectly to equity, you may have more exposure than you realise. Then ask: what if interest rates rise (important for longer-duration debt), what if the sector I’m heavily in faces a downturn, and what if I need a large amount of money during a correction? These questions reveal risks that a simple list of investments won’t show. Also remember that diversification is about time too: money needed for a child’s education in two years needs more attention to stability and liquidity than money you won’t touch for 15 years.
Test 7: Is Your Total Family Wealth Diversified?
For many Indian families, real estate is a large share of wealth. If your financial portfolio looks diversified but three properties make up 70% of family wealth, you’re still concentrated in real estate. The same applies to business owners: with a ₹10 crore business and ₹2 crore of other investments, family wealth is still heavily dependent on the business, and possibly on one industry for both income and net worth. Investment-portfolio diversification and total-wealth diversification aren’t always the same thing.
Two Portfolios, Same ₹50 Lakh
Portfolio A has a large-cap fund, a flexi-cap fund, an index fund, a mid-cap fund, direct stocks, and an FD. It looks diversified because there are six investments, but the equity portion may overlap heavily. Portfolio B holds diversified equity, debt and FDs, gold, and liquid investments, with fewer products but potentially wider spread across asset classes. Which suits a particular investor depends on goals and risk profile, but the principle holds: more products don’t automatically mean more diversification.
When Does a Portfolio Need Rebalancing?
Even a well-diversified portfolio drifts. Start with 60% equity, 30% debt, and 10% gold, and after a strong equity run it could become 75% equity, 18% debt, and 7% gold. You didn’t choose that extra equity risk; the market did. Rebalancing means bringing the portfolio back toward an allocation that fits your objectives and risk profile. It doesn’t mean selling everything that has done well. Note too that diversification reduces concentration risk but can’t eliminate losses: in a broad global decline, several asset classes can fall together.
GCIC Finserve’s Perspective for Delhi NCR Investors
At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we help Delhi NCR investors understand how their mutual fund holdings fit together, including category choices and overlap. Connect with our team to discuss your mutual fund holdings. For official fund category and portfolio disclosure information, refer to AMFI India.
FAQs
Q1. How many mutual funds should I own to be diversified? There’s no fixed number. Adding funds with similar holdings may increase complexity without improving diversification.
Q2. Is owning different mutual fund categories enough? Not necessarily. Different categories can still have overlapping holdings, so actual portfolio exposure matters more than fund names.
Q3. How can I check mutual fund overlap? Compare the underlying holdings of your funds and spot companies and sectors that appear repeatedly. Many portfolio tools offer overlap analysis.
Q4. Can too much diversification be a problem? Yes. Too many investments can make a portfolio hard to monitor, create overlap, and obscure the actual risks.
Q5. Should I rebalance every year? Not necessarily. It depends on how far your allocation has drifted from the intended one, and a periodic review can show when rebalancing may be appropriate.
Final Word
A properly diversified portfolio isn’t the one with the most investments. It’s one where your money is deliberately spread across assets, companies, sectors, and risks to match your goals. The real test: if one company fails, one sector struggles, rates rise, or equity markets fall, how much of your overall wealth is affected? That tells you far more than the number of statements in your drawer.
Disclaimer: This article is for general educational and informational purposes only and should not be construed as investment, financial, or tax advice. There is no single asset allocation or diversification strategy suitable for every investor. Mutual fund and other market-linked investments are subject to market risks, and diversification does not guarantee profits or eliminate losses. Please consider your goals, horizon, liquidity needs, and risk profile, and consult a qualified financial professional where appropriate.