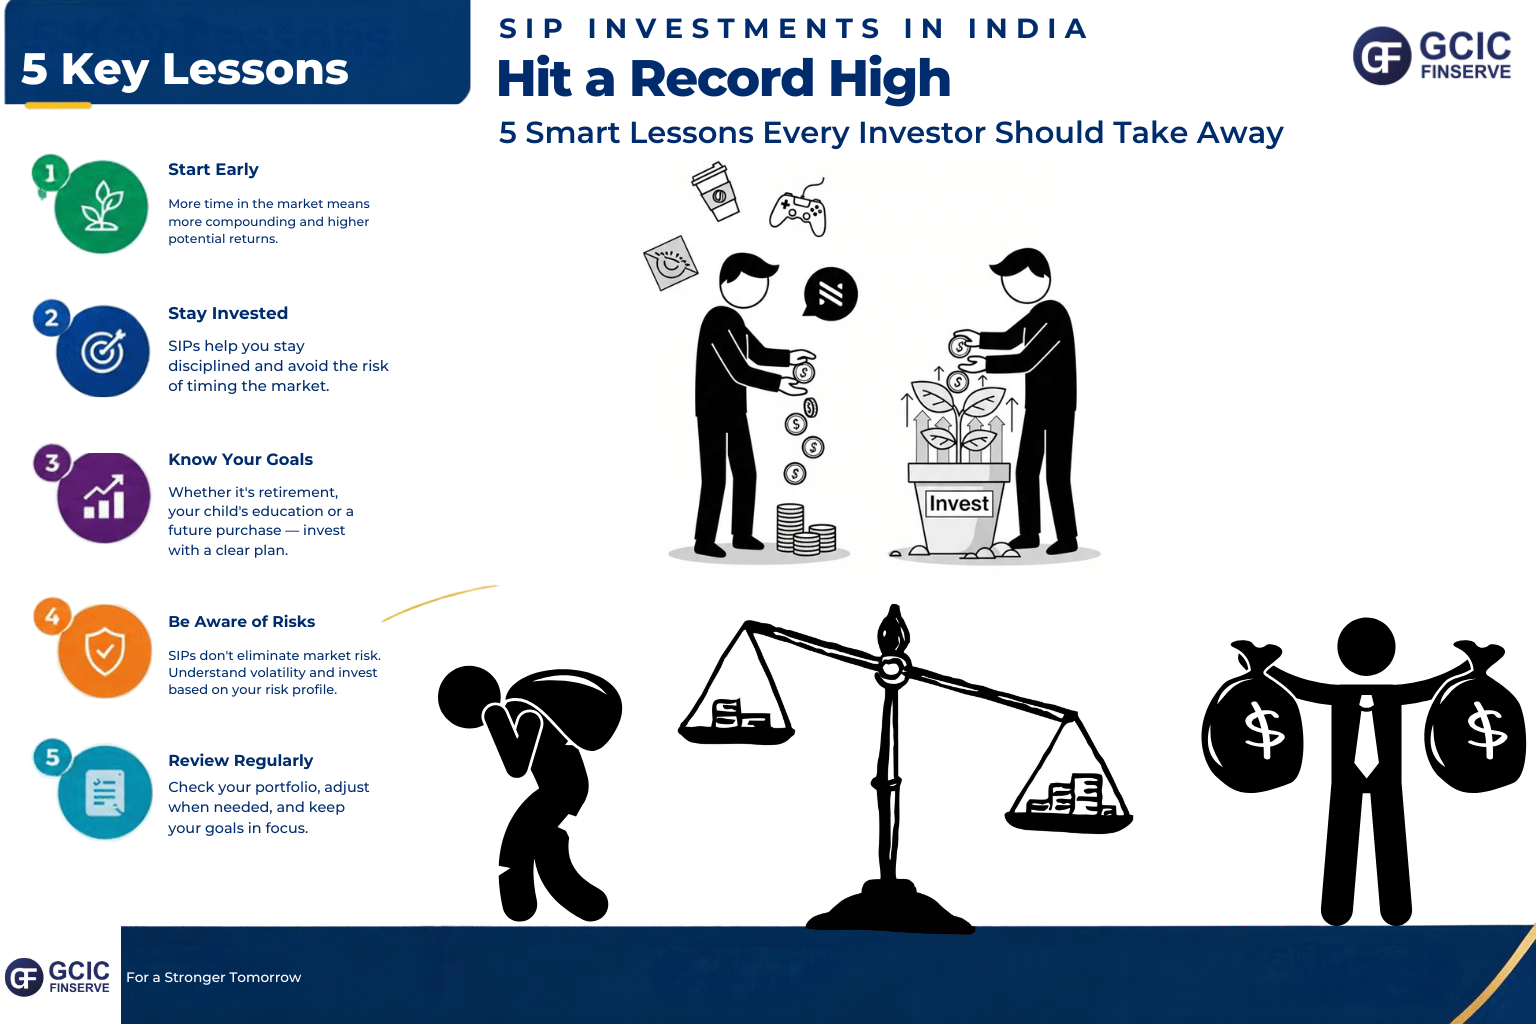
SIP Investments in India Hit a Record High: 5 Smart Lessons Every Delhi NCR Investor Should Take Away

SIP investments in India hit a record high with ₹32,297 crore monthly contribution in August 2026
India’s monthly SIP contribution reached a record ₹32,297 crore in August 2026, according to AMFI data.

SIP investments in India hit a record high of ₹32,297 crore in August 2026—the highest monthly SIP contribution ever recorded by AMFI. Ten years earlier, in August 2016, that number was just ₹3,497 crore. That’s a more than nine-fold jump in a decade. But behind this headline number is a much more interesting story for Delhi NCR investors: how Indians are quietly changing the way they think about money and what the cost of waiting to invest actually looks like.

Just How Big Is India’s SIP Boom?

The scale becomes clear when you place the numbers side by side. Monthly SIP contributions rose from ₹3,497 crore in August 2016 to ₹32,297 crore in August 2026. Outstanding SIP accounts reached 10.75 crore, with 10.02 crore actually contributing that month, and SIP assets under management touched ₹18.62 lakh crore. AMFI also recorded 66.40 lakh new SIP registrations in August alone, against 53.82 lakh SIPs that were discontinued or completed—a net addition of roughly 12.58 lakh accounts in just one month. SIP investments in India hitting a record high comes as part of a much larger increase in SIP participation over the past decade. 

The Bigger Mutual Fund Story Behind the Numbers

SIPs are just one part of a much larger transformation. India’s overall mutual fund industry AUM stood at ₹87.08 lakh crore at the end of August 2026, up roughly six-fold from ₹15.63 lakh crore in August 2016. Mutual fund folios have grown from 10.86 crore in August 2021 to 28.35 crore in August 2026—more than a two-and-a-half-fold increase in just five years, with roughly 21.62 crore of those folios in equity, hybrid, and solution-oriented schemes. For Delhi NCR households, this points to something bigger than a passing trend: organized, systematic investing is becoming the norm rather than the exception.

Why Has the SIP Become So Popular?

The appeal is part mathematics, part psychology. Ask someone to invest ₹12 lakh in one go, and it immediately raises hard questions—where will the money come from, is the market at the right level, and what if it falls right after? Ask instead, “Can you invest ₹10,000 a month?” and the decision suddenly feels manageable. According to AMFI, a SIP, is simply a method of investing a fixed amount periodically in a mutual fund scheme, helping investors stay disciplined without trying to time the market. It’s worth remembering: a SIP is a method of investing, not an investment product in itself—the underlying mutual fund is what actually carries the risk and return.

The Real FOMO Isn’t About Missing the Next Rally

The common fear is “the market went up; I should have invested earlier.” But that’s not the FOMO that matters most. Consider two people who both could have started investing ₹10,000 a month five years ago—one did, one kept waiting for the “right time.” Five years later, the person who started has something the other person can never buy back: five years of investment time. You can increase your SIP amount later, change your strategy later, or even recover from a bad investment choice later—but you cannot recover lost time.

What Does Starting Early Actually Do?

Here’s a simple illustration. Investing ₹10,000 every month for 20 years means a total contribution of ₹24 lakh, which at an illustrative 12% annualized return could grow to approximately ₹99 lakh. Wait five years, and investing the same ₹10,000 monthly for only 15 years brings the total contribution down to ₹18 lakh, with an illustrative corpus of around ₹50 lakh. (These are hypothetical illustrations, not guaranteed returns—actual outcomes depend on market performance, fund selection, costs, and taxes.) The investor who waited contributed just ₹6 lakh less, yet the eventual illustrative gap is far larger—because those extra five years of compounding matter more than the headline contribution amount.

The Other Side of the SIP Story

Record SIP contributions shouldn’t push anyone into investing blindly. When your colleague has an SIP, your friend has three mutual funds, and headlines talk about ₹32,297 crore flowing in every month, it’s easy to feel like you’re “behind”—but that’s FOMO, not a strategy. The fact that millions of Delhi NCR residents (and Indians nationwide) are investing through SIPs doesn’t tell you what to invest in, how much risk to take, or which mutual fund category actually suits your goal. It’s also worth remembering that an SIP doesn’t remove market risk—if you’re invested in equity mutual funds, your value can still fall when markets fall. A SIP simply means you keep investing on schedule; it doesn’t eliminate volatility.

3 Questions to Ask Before Starting a SIP

Before jumping in because “SIP investments in India hit a record high” made headlines, ask yourself:

  1. What am I actually investing for? Retirement, a child’s education, or a future purchase can each call for a different approach.
  2. How long can I realistically stay invested? Your time horizon should match the volatility you’re willing to sit through.
  3. How much can I invest without disrupting my monthly budget? A sustainable SIP beats an aggressive one you can’t maintain past a few months.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we see the SIP boom as a genuine shift in household financial behavior—but record flows should never replace a plan built around your own goals and risk profile. If you have a long-term goal and keep postponing simply because the timing never feels perfect, it’s worth understanding what that delay is actually costing you in lost compounding time. Connect with our team to understand which mutual fund categories might suit your goals. For the latest official SIP and mutual fund industry data, refer to AMFI India’s official reports.

FAQs

Q1. Are SIP investments in India really at a record high?

Yes—AMFI reported ₹32,297 crore in monthly SIP contributions in August 2026, the highest in its published series.

Q2. Does a record SIP contribution mean the stock market will rise? No. SIP flows reflect investor participation, not a reliable signal of future market direction.

Q3. Is it too late to start a SIP now that contributions are at record highs? 

There’s no universal answer—it depends on your goals, horizon, and risk tolerance. But waiting indefinitely for a “perfect” entry point can mean losing valuable compounding time.

Q4. Does starting a SIP early guarantee higher returns? 

No. Starting earlier gives your investment more time to potentially compound, but actual returns still depend on market performance and the underlying fund.

Final Word

SIP investments in India hitting a record high isn’t a signal to rush in—it’s a signal that Indian investors, including many across Delhi NCR, are increasingly treating investing as a recurring habit rather than a one-time event. You don’t need to feel FOMO because someone else started before you. But if investing genuinely fits your goals, understand what indefinite postponement is costing you. The market will offer many entry points over your lifetime—time is the one entry point you can’t revisit.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. The illustrations used are hypothetical. Please assess your own financial circumstances and, where appropriate, consult a qualified financial professional before investing. Data source: Association of Mutual Funds in India (AMFI), August 2026.
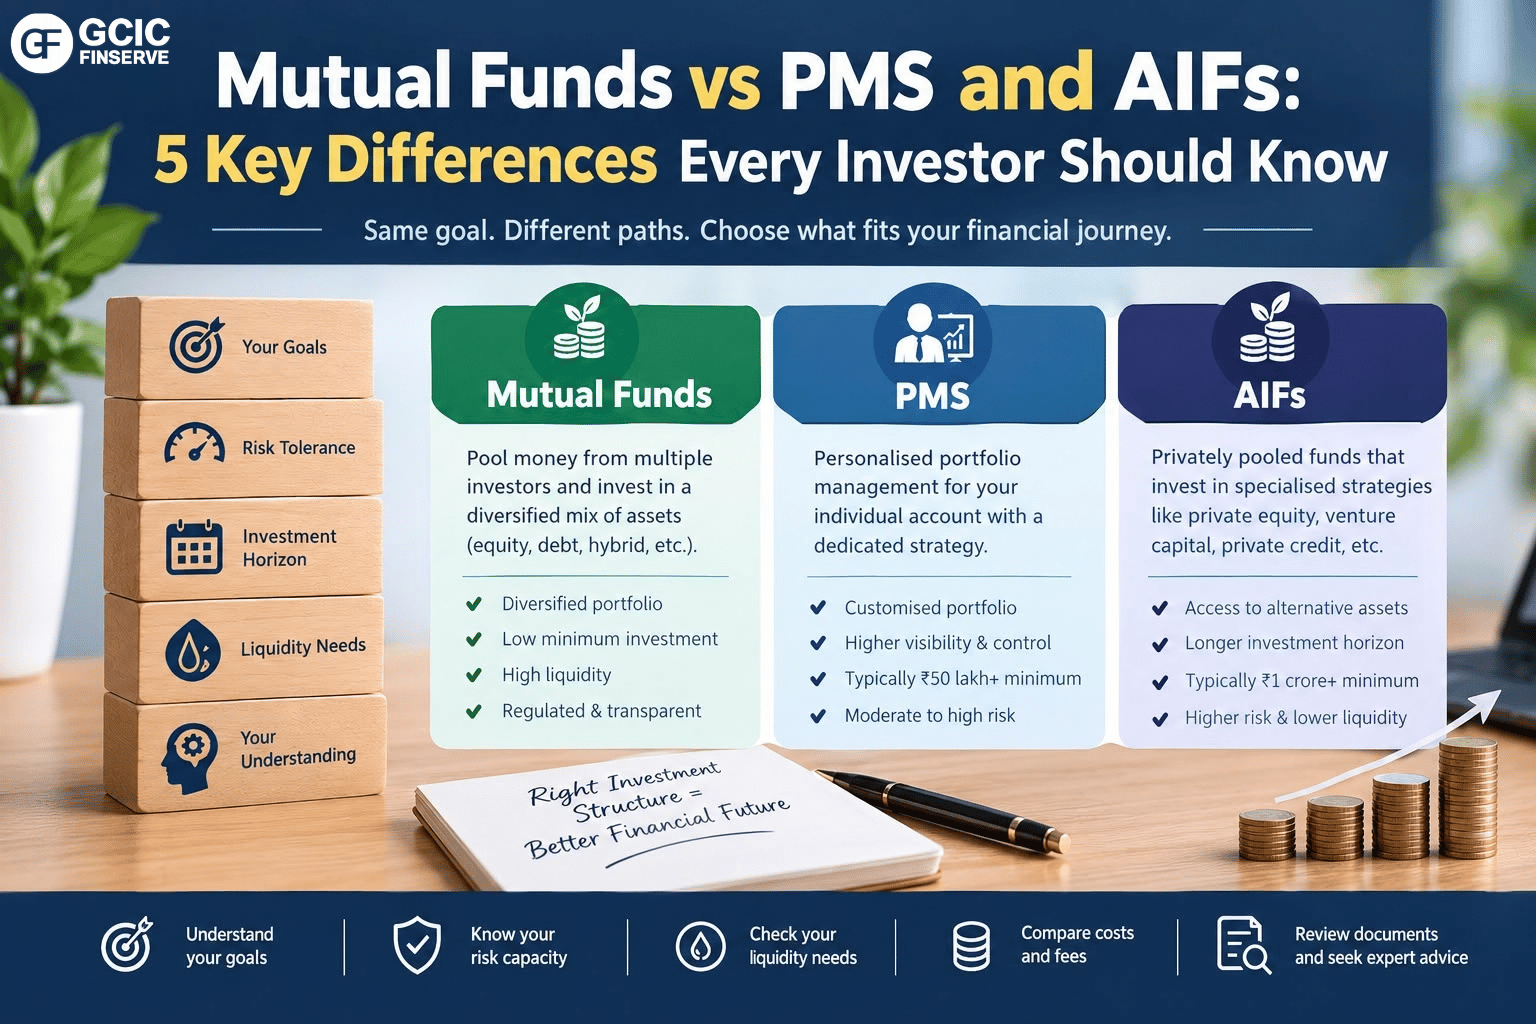
Mutual Funds vs PMS and AIFs: 5 Key Differences Every Investor Should Know

Mutual funds vs PMS and AIFs: key investment differences
Mutual Funds vs PMS and AIFs – understand the key differences in investment structure, customisation, risk, liquidity and costs.

As an investment portfolio grows, many investors begin comparing mutual funds vs PMS and AIFs. Mutual funds, Portfolio Management Services (PMS), and Alternative Investment Funds (AIFs) offer different ways to invest, manage risk, and access financial opportunities.

However, a more specialized investment structure is not automatically better. The right choice depends on your financial goals, risk tolerance, investment horizon, liquidity requirements, and level of understanding.

Three Investment Structures Explained Simply

Mutual Funds

A mutual fund pools money from multiple investors. The fund manager invests this money according to the scheme’s stated objective.

Mutual funds may invest in equity, debt, hybrid instruments, and other permitted securities. Investors own units of the scheme rather than directly owning every security in the portfolio.

Portfolio Management Services (PMS)

PMS involves managing investments in an investor’s individual account according to an agreed strategy.

Depending on the arrangement, PMS may provide greater portfolio visibility and customization. However, the strategy, costs, concentration, and risks vary between providers.

Alternative Investment Funds (AIFs)

AIFs are privately pooled investment vehicles that follow specific investment strategies. Depending on the category and mandate, an AIF may invest in private equity, venture capital, private credit, or other permitted investments.

AIFs can involve longer investment horizons, limited liquidity, and specialised risks.

Mutual Funds vs PMS and AIFs: 5 Key Differences

1. Ownership and Investment Structure

In a mutual fund, investors own units of a common scheme.

In PMS, the underlying securities are generally held in the investor’s individual account, subject to the service arrangement.

In an AIF, investors participate in a pooled investment structure and follow the fund’s defined strategy.

The ownership structure affects transparency, control, reporting, and how investments are managed.

2. Portfolio Customisation

Mutual funds generally follow one investment strategy for all investors in the scheme.

PMS can offer greater customisation because the portfolio is managed for an individual investor. However, the degree of customisation depends on the specific PMS strategy and agreement.

AIF investments usually follow a common strategy defined in the fund’s documents rather than being individually customised for every investor.

More customisation does not necessarily mean lower risk. A concentrated portfolio may increase exposure to specific companies, sectors, or investment themes.

3. Investment Opportunities

Mutual funds provide access to various permitted asset classes, including equity, debt, and hybrid investments.

PMS strategies may focus on listed equities, debt, or other permitted securities, depending on the portfolio manager’s mandate.

AIFs may provide access to specialised opportunities such as:

  • Private equity
  • Venture capital
  • Private credit
  • Specialised investment strategies
  • Other permitted alternative investments

The availability of these opportunities depends on the fund’s category, mandate, and regulatory framework.

4. Liquidity and Investment Horizon

Liquidity refers to how easily an investment can be converted into cash.

Mutual funds generally offer relatively convenient purchase and redemption mechanisms, although the applicable rules vary by scheme.

PMS liquidity depends on the securities held and the investment strategy.

AIFs may have lock-in periods, limited exit opportunities, or longer investment commitments, particularly when they invest in private or less-liquid assets.

Before investing, understand:

  • Lock-in period
  • Exit conditions
  • Redemption process
  • Possible exit charges
  • Expected investment duration

5. Minimum Investment, Costs and Risks

Mutual funds are available across a wide range of investment amounts, depending on the scheme.

For PMS, the general regulatory minimum investment requirement is ₹50 lakh, subject to applicable regulations and exceptions.

For AIFs, the general minimum investment requirement is ₹1 crore, with specific exceptions, including provisions applicable to accredited investors. Always verify the current regulatory requirements before investing.

Costs also differ between these structures. Investors should review:

  • Management fees
  • Expense ratios
  • Performance-linked fees
  • Exit charges
  • Other applicable expenses

Higher fees or greater complexity do not guarantee better investment performance.

When Mutual Funds May Be Suitable

Mutual funds may be suitable for investors looking for diversified exposure through a professionally managed structure.

They can be considered for goals such as:

  • Long-term wealth creation
  • Retirement planning
  • Children’s education
  • Systematic investing
  • Asset allocation

The suitability of a mutual fund depends on its investment objective, risk level, costs, and alignment with the investor’s goals.

A growing portfolio does not automatically require an investor to shift away from mutual funds.

When PMS May Be Considered

PMS may be considered by investors who require a more personalised investment approach and understand the associated risks and costs.

Potential features may include:

  • Individual portfolio management
  • Greater visibility of holdings
  • Strategy-based customisation
  • Direct ownership of underlying securities

However, PMS portfolios may be more concentrated and can experience significant fluctuations. Investors should carefully evaluate the portfolio manager, strategy, fees, risk management process, and track record.

Past performance does not guarantee future results.

When an AIF May Be Suitable

AIFs may be considered by eligible investors seeking exposure to specialised investment strategies or asset classes.

Depending on the AIF category, investments may involve private companies, venture capital, private credit, or other alternative assets.

Before investing, assess:

  • Investment strategy
  • Fund category
  • Lock-in period
  • Liquidity risks
  • Capital commitment
  • Fees and expenses
  • Risk disclosures
  • Exit and distribution terms

An AIF should be selected based on its specific investment purpose rather than its exclusive or sophisticated image.

Is PMS or an AIF Automatically Better Than a Mutual Fund?

No investment structure guarantees superior returns.

A mutual fund, PMS strategy, or AIF may perform differently depending on market conditions, investment decisions, costs, and portfolio construction.

Instead of asking which product is more sophisticated, consider:

What specific purpose will this investment serve in my portfolio?

The investment structure should match your financial goals, risk capacity, liquidity needs, and investment knowledge.

5 Questions to Ask Before Investing

Before moving money from mutual funds into PMS or AIFs, ask yourself:

  1. What financial goal am I trying to achieve?
  2. What additional benefit does this investment provide?
  3. How much liquidity am I giving up?
  4. Do I understand all costs and risks?
  5. Am I choosing the strategy or simply following recent returns?

A detailed review can help you understand whether the proposed investment fits your overall financial plan.

GCIC Finserve’s Perspective

At GCIC Finserve, we help investors understand different investment structures based on their financial goals, risk profile, and liquidity requirements.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), AMFI-registered SIF Distributor, and PMS Distributor (APRN-08140), our team helps investors evaluate the role of mutual funds, PMS, and AIFs within their overall investment strategy.

Before making an investment decision, review the relevant product documents and understand the risks, fees, and applicable eligibility requirements.

Contact GCIC Finserve to discuss your investment requirements.

Frequently Asked Questions

Q1. Is PMS better than mutual funds?

Not automatically. PMS may offer greater customization, but it can involve different costs, concentration levels, and risks. Suitability depends on the investor’s requirements.

Q2. What is the minimum investment for PMS in India?

The general minimum investment requirement for PMS is ₹50 lakh, subject to applicable regulations and exceptions.

Q3. What is the minimum investment for AIFs?

The general minimum investment requirement for AIFs is ₹1 crore. Certain exceptions may apply, including provisions for accredited investors. Confirm the current rules before investing.

Q4. Can I invest in mutual funds, PMS, and AIFs together?

Yes, an investor may use different investment structures where appropriate. Each investment should have a clearly defined purpose and fit the overall portfolio strategy.

Q5. Should high-net-worth investors automatically move to PMS or AIFs?

No. A larger portfolio does not automatically make a complex investment product suitable. Goals, risk tolerance, liquidity, costs, and investment knowledge should be evaluated first.

Final Word

The comparison of mutual funds vs PMS and AIFs is not about choosing the most sophisticated product. It is about understanding how each structure works and whether it supports your financial goals.

Mutual funds, PMS, and AIFs have different features, costs, risks, and liquidity conditions. Evaluate each option carefully, review the relevant documents, and make decisions based on your individual circumstances.

Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Investments in mutual funds, PMS, and AIFs are subject to market and other risks. Please review all relevant product and scheme documents and consult an appropriately registered professional before investing.

Top 10 Mutual Funds to Invest in 2026 | Where & How to Invest

Top 10 mutual funds to invest in 2026
Top 10 mutual funds to consider in 2026 based on investment goals, risk profile and time horizon.

Choosing the right mutual fund can be a useful way to work toward your long-term financial goals. The top 10 mutual funds to invest in 2026 can vary depending on an investor’s financial objectives, risk appetite, and investment horizon. Instead of selecting a fund only because it has delivered high recent returns, investors should consider consistency, portfolio quality, costs, and suitability.

For investors looking for mutual fund investment in Delhi NCR, the same principles apply. Whether you are based in South Delhi, Gurgaon, Noida, or Ghaziabad, understanding your investment goals and risk tolerance can help you make more informed decisions.

Top 10 Mutual Funds to Invest in 2026

There is no single mutual fund that is suitable for every investor. Different mutual fund categories serve different investment objectives. The following categories can help investors research potential options for 2026:

1. Flexi Cap Funds

Flexi cap funds invest across large-cap, mid-cap and small-cap companies. Their flexible investment approach can provide diversified equity exposure and may suit investors with a long-term investment horizon.

2. Large Cap Funds

Large cap funds primarily invest in established companies with relatively large market capitalization. They may be considered by investors looking for equity exposure with a focus on well-established businesses.

3. Mid-Cap Funds

Mid-cap funds invest in medium-sized companies. These companies can offer attractive growth opportunities, although mid-cap investments can experience higher market volatility.

4. Small Cap Funds

Small cap funds invest primarily in smaller companies. They can offer significant long-term growth potential but generally carry higher volatility and risk. Investors should have a suitable time horizon before considering this category.

5. Index Funds

Index funds aim to replicate the performance of a particular market index. They generally follow a passive investment strategy and can be considered by investors seeking diversified market exposure.

6. ELSS Funds

Equity-linked savings schemes, commonly known as ELSS funds, invest primarily in equities and may provide tax-saving benefits subject to applicable tax laws. They may be considered by investors who want to invest in equities while also planning their taxes under applicable tax rules.

7. Aggressive Hybrid Funds

Aggressive hybrid funds combine equity and debt investments within a single portfolio. They may suit investors who want equity-oriented growth potential along with some allocation to fixed-income assets.

8. Balanced Advantage Funds

Balanced advantage funds dynamically manage their allocation between equity and debt according to the fund’s investment strategy. This approach can provide investors with a diversified asset-allocation framework.

9. Debt Funds

Debt funds primarily invest in fixed-income securities. Depending on the category, they may be considered for different investment horizons and income or capital-preservation objectives.

10. Multi Cap Funds

Multi cap funds invest across large-cap, mid-cap, and small-cap companies. This provides exposure to different segments of the equity market and can be suitable for investors seeking broad equity diversification.

How to Choose the Right Mutual Fund in 2026

When researching the top 10 mutual funds to invest in 2026, investors should look beyond short-term returns. A fund’s historical consistency, portfolio diversification, expense ratio, investment strategy, and risk level are important factors to evaluate.

Your investment horizon should also influence your decision. Equity-oriented mutual funds are generally more suitable when investors have a longer time horizon and can tolerate market fluctuations. For shorter-term goals, investors should carefully consider liquidity and the level of risk involved.

It is also important to understand that past performance does not guarantee future returns. Mutual fund investments are subject to market risks, and investors should review the scheme’s documents and objectives before investing.

SIP or Lump Sum: Which Is Better?

A Systematic Investment Plan, or SIP, allows investors to invest a fixed amount at regular intervals. SIPs can encourage disciplined investing and are commonly used for long-term financial goals.

A lump-sum investment involves investing a larger amount at one time. This approach may be suitable when an investor has a significant amount of capital available for investment.

The better approach depends on your financial situation, investment objectives, cash flow, and risk tolerance. Investors can also use a combination of approaches depending on their circumstances.

Mutual Fund Investment in Delhi NCR

Investors searching for mutual funds in Delhi NCR can explore equity, debt, hybrid, index, and other mutual fund categories based on their needs . Investors in South Delhi, Gurgaon, Noida, and Ghaziabad should consider their financial goals and risk profile before selecting an investment.

GCIC Finserve helps investors understand different investment options and evaluate solutions based on their financial objectives, investment horizon, and risk profile.


Conclusion

The best 10 mutual funds for 2026 can help you begin looking at different fund types. Still, the right choice depends on what you want from your money, how many ups and downs you can handle, and how long you plan to stay invested.  

You should not pick a fund only because it did well recently. Look closely at how the fund invests, what it holds, the fees, the risk level, and if it fits your needs. This makes your decision more grounded.  

If you are in Delhi NCR, having a clear plan can also help your mutual fund choices match your bigger long-term money goals.

FAQ

What are the top 10 mutual funds to invest in 2026?

The top 10 mutual funds to invest in 2026 can differ according to an investor’s financial goals and risk profile. Investors should compare fund categories, consistency, portfolio quality, costs, and investment horizon before investing.

Is SIP a good way to invest in mutual funds?

SIP can be a convenient way to invest regularly and develop disciplined investing habits. Its suitability depends on an individual’s income, financial goals, and investment strategy.

Are mutual funds safe for beginners?

Mutual funds are market-linked investments and therefore involve investment risk. Beginners should understand the risks, investment objective, and time horizon of a fund before investing.

How can I invest in mutual funds in Delhi NCR?

Investors in Delhi NCR can research suitable mutual fund categories and seek guidance from a qualified financial professional. GCIC Finserve can help investors explore investment solutions based on their individual financial requirements.


Disclaimer: Investments in the securities market are subject to market risks. Mutual fund investments are subject to market risks and may involve market volatility and limited liquidity. Investment terms, fees, and eligibility are subject to applicable regulations and scheme documents. This article is for educational purposes only and should not be considered investment advice. Please read the relevant scheme documents carefully before investing.

Real Estate vs Mutual Funds: Which Is Better for Long-Term Investment?

real estate vs mutual funds comparison
Real Estate vs Mutual Funds: Key Investment Differences

Real estate vs mutual funds is a common investment decision for investors looking to build long-term wealth. Both investment options have their own advantages, risks, and suitability depending on an investor’s financial goals, risk tolerance, investment horizon, and liquidity needs.

Real estate involves investing in physical property, while mutual funds provide exposure to professionally managed portfolios of securities.

For investors in Delhi NCR, South Delhi, Noida, Gurugram, and Ghaziabad, this decision can be especially important because property has traditionally been a popular wealth-building option in the region. 

So, which is better? 

There is no single answer. The right choice depends on your financial goals, risk tolerance, investment horizons, and liquidity needs. 

Real Estate vs Mutual Funds: Quick Comparison 

Factor  Real Estate  Mutual Funds 
Initial Investment  Usually high  Can start with smaller amounts 
Liquidity  Generally lower  Generally higher for open-ended funds 
Diversification  Usually limited  Can provide diversification 
Management  Investor manages the property.  Professionally managed 
Maintenance  Required  No physical maintenance 
Investment Flexibility  Lower  Higher 
Risk  Market & property-specific  Market-linked 
Regular Investing  Difficult  SIP available 


Why Do People Invest in Real Estate?
 

Real estate has a strong appeal because it is a physical asset. Investors can use the property, rent it out, or hold it for potential appreciation. 

Property can also provide rental income. However, buying real estate usually requires substantial capital. Investors may also have to consider stamp duty, registration, maintenance, property taxes, loan costs, and other expenses. 

Another important factor is liquidity. Selling a property can take time, especially when you need to sell at a specific price. 

Why Are Mutual Funds Becoming Popular? 

A major benefit of mutual funds is flexibility. 

Instead of investing a large amount in one physical asset, investors can choose schemes that provide exposure to a portfolio of securities. This can help with diversification and allows investors to participate in financial markets without directly managing individual securities. 

Mutual funds also make regular investing easier through Systematic Investment Plans (SIPs). An investor can invest a fixed amount periodically rather than waiting to accumulate a large amount for a property purchase. 

However, mutual funds are market-linked investments. Their value can rise or fall depending on market conditions, and returns are not guaranteed. 

Mutual Funds vs Property: Which Offers More Flexibility? 

If flexibility is important to you, mutual funds can have an advantage. 

An investor can generally start with a relatively smaller amount, increase investments over time, and, depending on the scheme, redeem investments when required. 

Real estate is less flexible because a property cannot usually be bought or sold in small portions. The transaction can also involve significant costs and paperwork. 

This makes mutual funds a practical option for investors who want to build wealth gradually while maintaining greater investment flexibility. 

Which Is Better for Long-Term Investment? 

For long-term investors, both real estate and mutual funds can have a role in a diversified financial plan. 

Real estate may suit someone who wants a physical asset and has sufficient capital. Mutual funds may suit investors looking for diversification, professional management, and the ability to invest systematically. 

The important point is not to choose an investment only because it generated good returns in the past. 

Instead, consider: 

  • Your financial goals 
  • Investment horizon 
  • Risk tolerance 
  • Liquidity requirements 
  • Existing investments 
  • Available capital 

What About Investors in Delhi NCR? 

For people searching for long-term investment options in Delhi NCR, property may seem like the obvious choice. But investing all your money into one property can concentrate your wealth in a single asset and location. 

Mutual funds can provide another route to diversification and systematic investing. 

At GCIC Finserve, investors can explore mutual fund solutions based on their financial objectives rather than following a one-size-fits-all approach. 

Final Verdict: Real Estate or Mutual Funds? 

So, real estate vs mutual funds—which is better? 

The answer depends on the investor’s goals, risk profile, and financial situation. 

If you prefer physical assets and have substantial capital, real estate may suit your requirements. If you prefer flexibility, diversification, and systematic investing, mutual funds may be worth considering. 

For many investors, the smarter approach may not be choosing only one. A properly planned portfolio can include different asset classes according to individual financial goals and risk appetite. 


FAQ 

1. Is real estate better than mutual funds?

Not necessarily. Real estate and mutual funds have different characteristics. The better option depends on your financial goals, risk tolerance, investment horizons, and liquidity requirements.

2. Which is better, property or mutual funds?

Property may appeal to investors who prefer physical assets, while mutual funds can offer greater flexibility and diversification. Your personal financial situation should determine the choice.

3. Are mutual funds good for long-term investment?

Mutual funds can be suitable for long-term investing, depending on the type of fund and the investor’s goals and risk profile. Equity-oriented funds, for example, are generally subject to market fluctuations.

4. Can I invest in mutual funds instead of buying property?

Yes. Mutual funds can be an alternative way to invest for long-term financial goals without purchasing physical property. They also allow investors to start with comparatively smaller amounts and invest through SIPs.

5. Are mutual funds safer than real estate?

Neither is automatically safe. Mutual funds carry market-related risks, while real estate involves property-market, liquidity, legal, financing, and location-related risks. Risk depends on the specific investment.

6. Why are mutual funds popular among investors?

Mutual funds can offer diversification, professional management, flexibility, and systematic investment options such as SIPs. These features make them accessible to a wide range of investors.

Disclaimer: Mutual fund investments are subject to market risks. Past performance does not guarantee future returns. Real estate investments also involve market, liquidity, legal, financing, and other risks. Investors should evaluate their financial goals, risk profile, and investment horizon before making investment decisions. This article is for educational purposes only and should not be considered investment advice.

Index Funds vs Actively Managed Funds: Who Wins?

Index Funds vs Actively Managed Funds

When it comes to investing in mutual funds, one of the most common debates among investors is Index Funds vs Actively Managed Funds. Both have their unique strengths and weaknesses, and understanding their differences can help you make smarter investment decisions. Let’s dive into a detailed index funds vs active funds comparison and find out who really wins.

What Are Index Funds?

Index funds are passive investment funds that track a specific market index—such as the Nifty 50 or Sensex in India. The fund’s portfolio mirrors the composition of that index, meaning it invests in the same stocks and proportions as the index itself.

This approach eliminates the need for active stock picking by fund managers, making index funds simple, transparent, and low-cost.

What Are Actively Managed Funds?

Actively managed mutual funds are overseen by professional fund managers who make decisions on which stocks to buy, sell, or hold. The goal is to outperform a specific benchmark index through in-depth research, market timing, and strategic selection.

These funds come with higher costs because of fund management fees, research expenses, and active trading, but they aim to deliver higher returns than the market.

Index Funds vs Actively Managed Funds Performance

Historically, index funds vs actively managed funds performance has been mixed. In developed markets like the U.S., index funds have consistently outperformed most active funds over the long term.

In India, the trend is shifting. Over the last few years, many actively managed large-cap funds have struggled to beat their benchmarks, making passive investing vs active investing in India a growing discussion among investors.

That said, active funds still have an edge in mid-cap and small-cap categories, where skilled managers can exploit market inefficiencies.

Pros and Cons of Index Funds

Pros:

  • ✅ Low cost: No active management means lower expense ratios.

  • ✅ Consistent returns: Matches market performance without overtrading.

  • ✅ Simple to understand: Ideal for long-term investors seeking steady growth.

Cons:

  • ❌ No chance to beat the market: Returns are limited to the index’s performance.

  • ❌ Lack of flexibility: Cannot adjust holdings during market volatility.

  • ❌ Tracking error risk: Minor deviations from the benchmark can occur.

Actively Managed Mutual Funds Advantages

Actively managed funds can offer several potential benefits, especially when managed by experienced professionals.

Advantages include:

  • ✅ Opportunity to outperform: Skilled managers can beat benchmarks with smart stock selection.

  • ✅ Dynamic strategy: Managers can adjust the portfolio based on market conditions.

  • ✅ Better for niche sectors: Active funds can focus on specific themes or sectors where deep research pays off.

However, these benefits come with higher expense ratios and no guarantee of outperformance.

Index Fund Returns vs Active Fund Returns

When comparing index fund returns vs active fund returns, long-term trends show that active funds may outperform in short bursts, especially during market volatility. However, index funds often deliver steady and reliable returns over the long term because of lower costs and minimal human error.

Low-Cost Index Funds vs Active Mutual Funds

One of the biggest advantages of index funds is cost-efficiency.
While active mutual funds may charge expense ratios between 1.5% to 2%, low-cost index funds often charge as little as 0.1% to 0.5%.

Over decades, this difference can significantly impact your total returns, making index funds a powerful choice for long-term wealth creation.

Which Is Better: Index Fund or Active Fund?

The answer depends on your investment style and goals.
If you prefer a low-cost, long-term, and hands-off approach, index funds may be the right choice.
If you’re willing to take slightly higher risks for potentially higher returns, actively managed funds could suit you better.

In today’s evolving market, many investors prefer a balanced strategy — investing in both index and active funds to diversify their portfolios.

Should I Invest in Index Funds or Active Funds?

Ask yourself these key questions:

  • Do you believe in long-term market growth and cost efficiency? → Go for index funds.

  • Do you prefer professional management and have a higher risk appetite? → Choose active funds.

Ultimately, the best investment depends on your financial goals, risk tolerance, and investment horizon.

Final Thoughts

In the debate of Index Funds vs Actively Managed Funds, there’s no one-size-fits-all answer.
However, as passive investing vs active investing in India gains traction, investors are increasingly favoring index funds for their simplicity, transparency, and low costs.

Still, actively managed mutual funds will continue to play an important role for those seeking alpha (market-beating returns) and professional management.

The smartest move? Combine both to create a diversified portfolio that balances growth, risk, and stability.

How to Invest in Mutual Funds During Market Volatility

How to Invest in Mutual Funds

Investing in mutual funds during market volatility can feel challenging, especially when markets experience sharp ups and downs. However, volatility is a normal part of investing and can also create opportunities for disciplined long-term investors. If you are wondering how to approach mutual funds during market volatility, this guide explains practical strategies to manage risk and stay focused on your financial goals.

Understanding Market Volatility and Mutual Funds

Volatility simply means frequent price fluctuations in the market. These movements can be triggered by global events, economic changes, policy decisions, or investor sentiment. For mutual fund investors, this can feel unsettling—but history shows that markets tend to recover over time, rewarding patient investors. That’s why building a long-term mutual fund strategy during market volatility is more important than trying to time the market.

Mutual Fund Investment Strategies in Volatile Markets

Here are some proven mutual fund investment strategies in volatile markets:

  1. Stick to SIPs (Systematic Investment Plans)
    A mutual fund SIP investment in volatile markets allows you to invest fixed amounts regularly. This helps you buy more units when prices are low and fewer when prices are high, averaging out your cost over time.

  2. Diversify Your Portfolio
    Spread your investments across equity, debt, and hybrid funds. This reduces risk, as not all asset classes move in the same direction during market turbulence.

  3. Focus on Quality Funds
    Choose funds with strong track records, experienced fund managers, and consistent performance. Quality funds tend to recover faster after downturns.

  4. Avoid Panic Selling
    Selling during dips locks in losses. Instead, focus on your goals and remember that volatility is temporary.

Best Mutual Funds for Market Volatility

If you are exploring the best mutual funds for market volatility, here are a few categories to consider:

  • Large-Cap Equity Funds – These invest in established companies with relatively stable earnings.

  • Balanced or Hybrid Funds – A mix of equity and debt to balance growth and safety.

  • Dynamic Asset Allocation Funds – Actively adjust allocations between equity and debt based on market conditions.

  • Debt Funds – For investors seeking stability and lower risk during turbulent times.

Safe Mutual Funds During Market Crash

While no investment is entirely risk-free, some categories are considered safe mutual funds during a market crash:

  • Liquid Funds

  • Overnight Funds

  • Short-Term Debt Funds

These provide stability and liquidity while reducing exposure to equity volatility.

Mutual Fund Risk Management in Volatile Markets

Risk management is crucial when investing in mutual funds when markets are unstable. A few tips include:

  • Rebalance your portfolio regularly to maintain your desired asset allocation.

  • Keep an emergency fund so you don’t withdraw investments prematurely.

  • Avoid overexposure to highly volatile sectors or thematic funds.

Should I Invest in Mutual Funds During Market Volatility?

A common question investors ask is: “Should I invest in mutual funds during market volatility?” The answer is yes—if you have a long-term perspective. Market volatility is often short-term noise, but mutual funds are designed to build wealth over years. In fact, entering during market dips often provides the potential for higher returns when markets recover.

Long-Term Mutual Fund Strategy During Market Volatility

The golden rule is: time in the market is more important than timing the market. A long-term mutual fund strategy during market volatility may include:

  • Continuing SIPs consistently.

  • Adding to investments during major corrections (if financially possible).

  • Reviewing your financial goals rather than reacting to short-term market swings.

Final Thoughts

Volatility is a natural part of investing and should not deter you from wealth creation. By following smart mutual fund investment strategies in volatile markets, staying disciplined with SIPs, and choosing the best mutual funds for market volatility, you can turn instability into an advantage. Remember, patience and consistency are your strongest allies.

How to Invest in Mutual Funds

Getting started with mutual fund investing is simpler with GCIC Finserv. Contact us now

The Power of Compounding in SIPs Explained – GCIC Finserve

Power of Compounding

The power of compounding in SIP can play an important role in long-term wealth creation. Compounding means that the returns generated on your investments can themselves contribute to future growth when you remain invested over time. Through regular Systematic Investment Plan (SIP) investments, investors can build wealth gradually while maintaining investment discipline.

How Compounding Works in SIP

To understand how compounding works in SIP, let’s take a simple example. Suppose you invest ₹5,000 every month in a mutual fund SIP. Each installment earns returns, and over time, those returns are reinvested, generating additional returns. This cycle of earning “returns on returns” is what compounding means. The longer you stay invested, the more powerful the effect becomes.

SIP Compounding Benefits

Here are the major SIP compounding benefits you can enjoy:

  1. Wealth Accumulation – Even small monthly investments grow into a large corpus.

  2. Affordability – You don’t need a lump sum; disciplined monthly investing works better in the long run.

  3. Reduced Market Risk – SIPs average out market fluctuations while compounding amplifies growth.

  4. Goal-Oriented Growth – Whether it’s retirement, education, or wealth creation, compounding supports your financial goals.

SIP Returns with Compounding

When we look at SIP returns with compounding, the difference between short-term and long-term investment becomes clear. In the short term (3–5 years), your returns may not seem very large. But over 10–20 years, compounding accelerates, and the wealth created often surpasses expectations. This is why many financial experts stress the importance of compounding in SIP for long-term financial planning.

Long Term SIP Compounding Power

The long-term SIP compounding power lies in patience and consistency. The earlier you start, the greater your advantage. For example, if you start investing at 25 instead of 35, even with the same monthly investment, your corpus at retirement could be significantly larger simply due to compounding working longer.

SIP Investment Compounding Formula

The SIP investment compounding formula is often calculated using the future value formula:

FV = P × [(1 + r/n)^(nt) – 1] × (1 + r/n) ÷ (r/n)

Where:

  • FV = Future Value of SIP

  • P = Amount invested every installment

  • r = Expected annual return rate

  • n = Number of compounding periods per year

  • t = Total investment duration (in years)

This formula helps investors estimate how SIP grows with compounding over time.

Mutual Fund SIP Compounding Benefits

When you invest in mutual funds via SIP, you unlock mutual fund SIP compounding benefits like professional fund management, diversification, and inflation-beating returns. Unlike fixed deposits or recurring deposits, mutual funds typically deliver higher growth potential, which magnifies when compounding comes into play.

Why the Importance of Compounding in SIP Cannot Be Ignored

The real importance of compounding in SIP lies in its ability to convert time into money. With consistent investments and patience, compounding ensures that your money works harder for you every single year. Missing even a few years of compounding can make a huge difference to your final wealth corpus.

Final Thoughts

Compounding in SIP explained in the simplest way is this: the longer you stay invested, the greater your returns. SIPs combined with the magic of compounding can turn modest monthly savings into a substantial financial cushion. So, start early, stay invested, and let time and compounding create wealth for you.

How to Invest in Mutual Funds

Getting started with mutual fund investing is simpler with GCIC Finserv. Contact us now

Understanding NAV in Mutual Funds: A Simple Guide

what is NAV in Mutual Funds

NAV in Mutual Funds is one of the most important concepts to understand when you start investing in mutual funds. If you are a beginner, you may have come across the term NAV and wondered what it means and how it affects your investment.

What is NAV in Mutual Funds?

NAV stands for Net Asset Value. In simple terms, it is the price of a single unit of a mutual fund scheme. Just like shares of a company have a market price, mutual fund units are valued at their NAV.

So, mutual fund NAV explained simply: It tells you how much one unit of a fund is worth at the end of a trading day.

NAV Meaning in Mutual Funds

The NAV meaning in mutual funds can be understood as:

In other words, it represents the per-unit value of the fund’s holdings after subtracting liabilities.

How NAV is Calculated in Mutual Funds

Fund houses calculate NAV every business day. Here’s a step-by-step NAV calculation example in mutual funds:

  1. Suppose a mutual fund owns stocks worth ₹100 crore and bonds worth ₹50 crore.

  2. It also has ₹5 crore cash and liabilities of ₹2 crore.

  3. Total assets = ₹100 + ₹50 + ₹5 = ₹155 crore.

  4. Net assets = ₹155 – ₹2 = ₹153 crore.

  5. If the fund has 10 crore units, then NAV = ₹153 ÷ 10 = ₹15.30 per unit.

This is how daily NAV in mutual funds India is calculated and published.

NAV vs Market Price in Mutual Funds

Many investors confuse NAV vs market price in mutual funds. Unlike stocks, mutual fund units do not trade on an exchange with fluctuating market prices. Their value is always based on the NAV declared at the end of each day.


Does NAV Affect Mutual Fund Returns?

A common doubt is: does NAV affect mutual fund returns? The answer is no. A fund with a low NAV doesn’t mean it will generate higher returns, and a fund with high NAV doesn’t mean it is expensive. Returns depend on how the underlying assets (stocks, bonds, etc.) perform—not on the NAV itself.

Importance of NAV in Mutual Fund Investment

The importance of NAV in mutual fund investment lies in:

  • Determining the number of units you get when you invest.

  • Helping you track your investment’s growth over time.

  • Ensuring transparency in how fund houses value their schemes.

But remember, when choosing a fund, don’t look only at the NAV—focus on the fund’s performance, portfolio quality, and consistency.

Final Thoughts

Understanding what is NAV in mutual funds is essential, but it’s only one part of your investment journey. Think of NAV as the entry price of your fund unit, not as a measure of performance. A fund with an NAV of ₹10 can give better returns than a fund with an NAV of ₹100, depending on its portfolio.

So, the next time you see the daily NAV of mutual funds in India, you’ll know exactly what it means—and why it should not be the only factor guiding your investment choices.

How to Invest in Mutual Funds

Getting started with mutual fund investing is simpler with GCIC Finserv. Contact us now

Equity, Debt, or Hybrid? How to Choose the Right Mutual Fund for Your Goals

How to Choose the Right Mutual Fund

Mutual Fund Selection is an important step when you want to invest in mutual funds based on your financial goals. With equity, debt and hybrid mutual funds offering different levels of risk and potential returns, choosing the right option can feel overwhelming.

Understanding the Three Main Types of Mutual Funds

1. Equity Mutual Funds

Equity mutual funds invest primarily in shares of companies.

  • Who are they for? Investors with long-term goals, such as wealth creation, retirement planning, or funding a child’s education.

  • Pros: Potential for high returns over time, tax benefits if held for over one year, and a hedge against inflation.

  • Cons: Higher risk due to market volatility, making them less suitable for short-term investments.

2. Debt Mutual Funds

Debt mutual funds invest in bonds, government securities, and other fixed-income instruments.

  • Who are they for? Conservative investors seeking stable income, capital preservation, or short-term parking of funds.

  • Pros: Lower risk than equity, predictable returns, and better liquidity compared to fixed deposits.

  • Cons: Returns are generally lower than equities, and they may still face interest rate or credit risk.

3. Hybrid Mutual Funds

Hybrid mutual funds invest in a mix of equity and debt instruments.

  • Who are they for? Investors who want a balanced approach—some growth potential without taking on full equity risk.

  • Pros: Diversification reduces risk, automatic rebalancing between equity and debt, and suitability for medium-term goals.

  • Cons: Returns are moderate, and performance can vary depending on market conditions.

How to Match Funds with Your Investment Goals

When choosing between these funds, align them with your personal investment goals:

  1. Short-Term Goals (up to 3 years):
    Debt mutual funds are more appropriate as they offer safety and predictable income.
    Examples: Building an emergency fund, saving for a vacation, or meeting upcoming expenses.

  2. Medium-Term Goals (3–5 years):
    Hybrid mutual funds strike a balance between growth and stability.
    Examples: Down payment for a house, funding a wedding, or building a safety corpus.

  3. Long-Term Goals (5+ years):
    Equity mutual funds are ideal for wealth creation, as they have the potential to outperform other assets over time.
    Examples: Retirement planning, children’s education, or building a financial legacy.

Key Factors for Effective Mutual Fund Selection

  1. Risk Appetite: Understand whether you are conservative, moderate, or aggressive.

  2. Time Horizon: Longer durations allow you to absorb short-term market fluctuations.

  3. Financial Goals: Be clear about whether you need growth, income, or a mix of both.

  4. Fund Performance & Costs: Look at the track record, expense ratio, and portfolio composition before investing.

  5. Tax Efficiency: Consider how capital gains tax impacts your overall returns.

Final Thoughts

Choosing between equity mutual funds, debt mutual funds, or hybrid mutual funds isn’t about finding the “best” fund in isolation—it’s about finding the right fit for your investment goals. By aligning your choices with your risk tolerance, time horizon, and financial objectives, you can make smarter decisions and stay on track to build long-term wealth.

Successful investing begins with informed mutual fund selection. Take the time to evaluate your needs carefully, and if necessary, consult a financial advisor to craft a plan that works for you.

How to Invest in Mutual Funds

Getting started with mutual fund investing is simpler with GCIC Finserv. Contact us now