Medical Emergency Preparedness in Delhi NCR: 7 Smart Tips for 2026

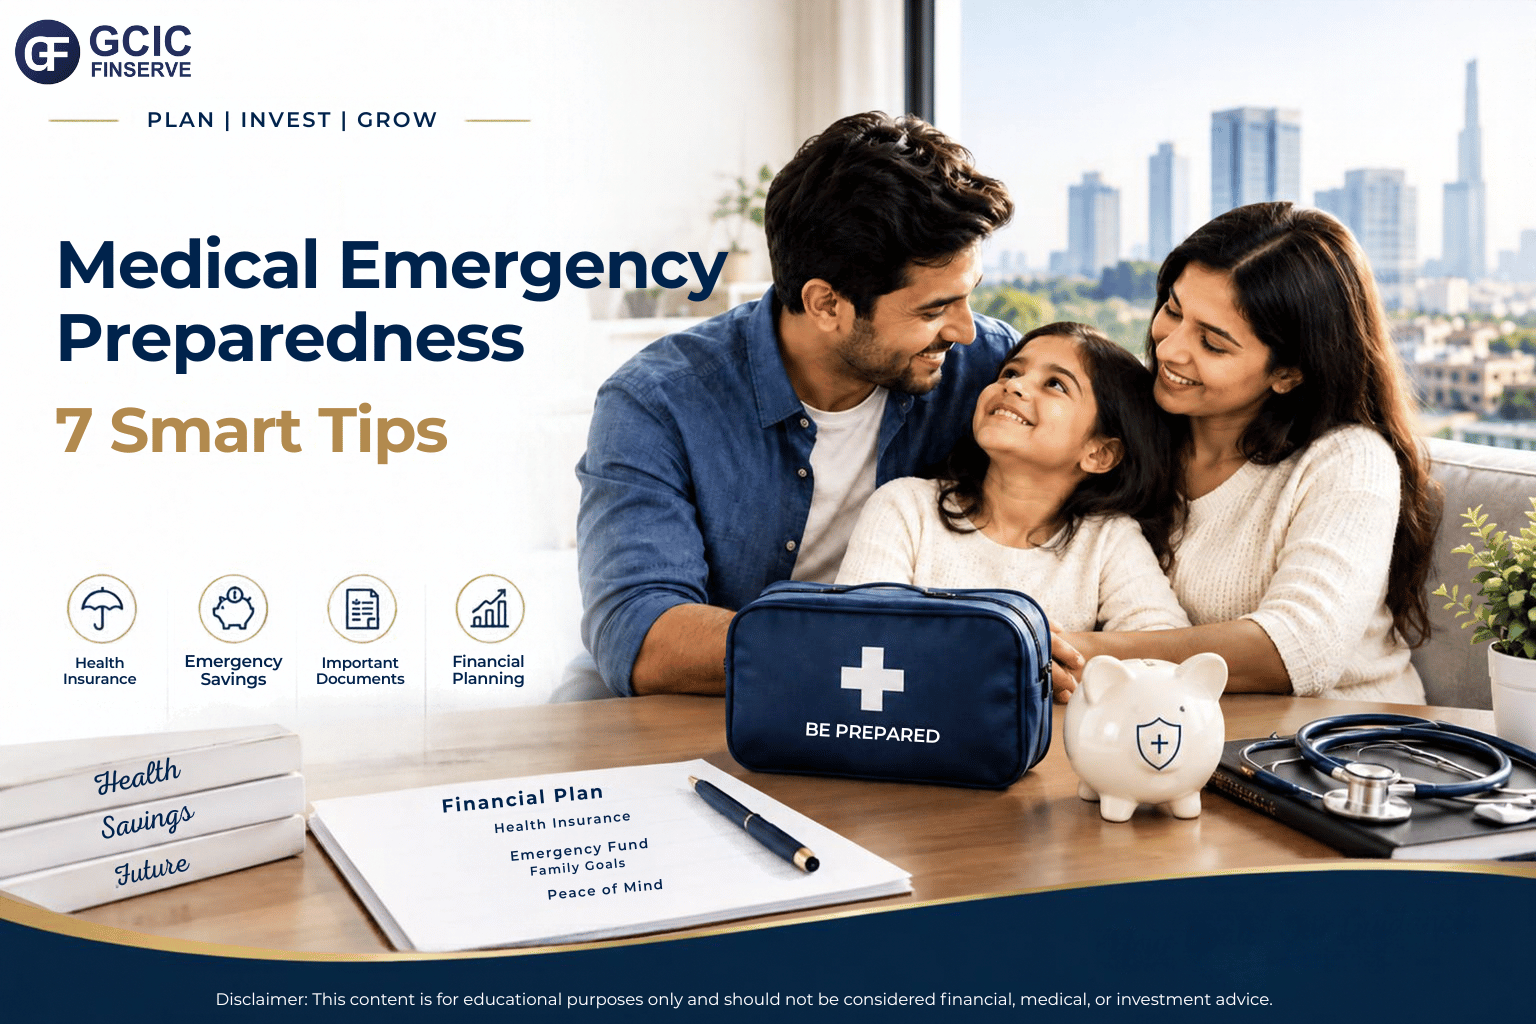
Medical emergency preparedness for Delhi NCR families with health insurance and emergency savings
Medical emergency preparedness helps families plan for unexpected healthcare expenses and protect their financial future.

Medical emergency preparedness is something many families think about only when an unexpected health situation occurs. A sudden hospital visit, surgery, or extended treatment can bring emotional stress along with significant financial expenses.

For families living in South Delhi, Gurugram, Noida, Ghaziabad, and other parts of Delhi NCR, having a basic financial preparedness plan can help them manage unexpected healthcare costs without unnecessarily disturbing money reserved for important goals.

The purpose is not to predict when an emergency will happen. It is to understand your health insurance, maintain accessible savings, and keep important documents organized.

Why Medical Emergency Preparedness Matters in Delhi NCR

Medical expenses can vary depending on the treatment, hospital, room category, medicines, diagnostic tests, and duration of hospitalization.

A medical emergency may involve more than the hospital bill. Families could also face expenses related to medicines after discharge, travel, temporary loss of income, and other household responsibilities.

This is why medical emergency preparedness should be considered as part of your overall financial planning.

The objective is simple:

Be prepared for unexpected expenses while protecting your family’s financial priorities.

The Financial Impact of a Medical Emergency

Imagine receiving an unexpected call from a hospital late at night.

Your immediate priority is the health of your family member. At the same time, you may need to arrange money, understand the estimated treatment cost, and check what your health insurance policy covers.

Without accessible funds, a family may need to borrow money or withdraw long-term investments at an inconvenient time.

Health insurance can help with eligible expenses, but coverage depends on the policy’s terms, conditions, exclusions, limits, and waiting periods.

Therefore, insurance and emergency savings can serve different purposes in a family’s financial preparedness plan.

7 Smart Steps for Medical Emergency Preparedness

1. Maintain a Separate Emergency Fund

Consider keeping a portion of your money in an easily accessible emergency reserve.

A commonly considered starting point is three to six months of essential household expenses. However, the appropriate amount depends on your income stability, family responsibilities, existing insurance and financial commitments.

The important factor is accessibility.

Emergency money should be suitable for short-term needs and should not depend entirely on selling long-term investments at short notice.

2. Review Your Health Insurance Regularly

Having health insurance is important, but purchasing a policy once and never reviewing it may not be sufficient.

Review your policy periodically and understand:

  • Sum insured
  • Waiting periods
  • Room-rent conditions
  • Exclusions
  • Co-payment requirements
  • Network hospitals
  • Claim conditions
  • Renewal terms

If your family size, income, or healthcare requirements change, reassess whether your existing coverage remains suitable.

You can explore health insurance planning in Delhi NCR to understand the factors involved in selecting insurance coverage.

Always read the policy wording carefully before making a decision.

3. Understand Where Your Emergency Money Is Kept

Emergency funds should be accessible when required.

Different financial products have different levels of liquidity, risk, withdrawal conditions, and taxation. Before using any financial product for emergency reserves, understand how quickly you can access the money and what conditions may apply.

Emergency money should prioritize accessibility and suitability over chasing higher returns.

The right option depends on your personal circumstances and financial requirements.

4. Keep Short-Term Needs Separate From Long-Term Investments

Money required for immediate expenses and money intended for long-term goals serve different purposes.

For example, investments planned for retirement or a child’s education may have a longer time horizon. Selling these investments suddenly during an emergency could affect the original financial objective.

Maintaining a separate emergency reserve may reduce the need to disturb long-term investments when an unexpected expense arises.

You can also review your mutual fund investment resources to understand available tools and investment information.

5. Keep Important Documents Accessible

During an emergency, searching for policy documents or account information can add unnecessary stress.

Keep important information organized, including:

  • Health insurance policy details
  • Policy number
  • Insurer contact information
  • Health card details
  • Nominee information
  • Important investment records
  • Bank account information
  • Emergency contact details

Family members should also know where these documents are stored and how to access them when necessary.

Avoid sharing sensitive financial or identity documents through unsecured channels.

6. Understand Expenses That Insurance May Not Cover

Health insurance does not necessarily cover every medical expense.

Depending on the policy, certain expenses may be subject to exclusions, limits, deductibles, co-payments, waiting periods, or other conditions.

For this reason, maintaining accessible savings alongside health insurance may help families manage expenses that arise during or after treatment.

For official insurance information and regulatory resources, you can visit the Insurance Regulatory and Development Authority of India (IRDAI).

Understand your policy before you need to use it.

7. Review Your Emergency Preparedness Every Year

Your financial circumstances can change over time.

A new child, change in income, home loan, increased family responsibilities, or a different health insurance requirement may affect your preparedness needs.

Set aside time at least once a year to review:

Emergency savings → Health insurance → Important documents → Short-term liquidity

You can also review your financial plan after a major life event, such as marriage, childbirth, job change, or retirement.

Regular reviews can help you identify gaps before they become urgent.

How GCIC Finserve Supports Investor Awareness

GCIC Finserve Limited helps investors understand financial products and available investment options, including mutual funds, fixed deposits, and other applicable solutions, subject to product features, eligibility, and relevant terms.

As an AMFI-registered mutual fund distributor, GCIC Finserve focuses on investor awareness and helping investors understand available options and associated risks.

For health insurance and other financial products, individuals should carefully review the relevant product documents, coverage conditions, exclusions, and applicable terms before making a decision.

You can learn more about GCIC Finserve and explore the available financial services.

Understand your options. Know the risks. Make informed decisions.

FAQs

Q1. What is medical emergency preparedness?

Medical emergency preparedness means maintaining accessible savings, understanding health insurance coverage, and organizing important financial documents so that an unexpected medical situation can be managed more effectively.

Q2. Is health insurance enough for a medical emergency?

Health insurance can help cover eligible medical expenses, subject to the policy’s terms, conditions, exclusions, and limits. An emergency reserve may also help with expenses that are not covered by the policy.

Q3. How much should I keep in an emergency fund?

A commonly considered starting point is three to six months of essential expenses. The appropriate amount depends on income stability, family responsibilities, existing savings, and financial commitments.

Q4. Should emergency money be invested?

Emergency money should prioritize accessibility and suitability for short-term needs. Before selecting a financial product, understand its risks, liquidity, withdrawal process, applicable charges, and taxation.

Q5. How often should I review my health insurance?

Review your health insurance at least annually and whenever there is a significant change in your family, income, or healthcare requirements. Always check the current policy terms.

Q6. Does health insurance cover every hospital expense?

Not necessarily. Coverage depends on the policy’s terms, exclusions, limits, waiting periods, and other conditions. Read the policy documents carefully and confirm the applicable coverage with the insurer.

Final Thoughts

A medical emergency cannot always be predicted, but families can prepare for its potential financial impact.

Maintaining accessible emergency savings, understanding health insurance coverage, organizing important documents, and separating short-term needs from long-term investments can support better financial preparedness.

You cannot predict tomorrow. But you can prepare for it.

Disclaimer

Insurance products are subject to policy terms, conditions, exclusions, waiting periods, and other applicable provisions. Mutual fund investments are subject to market risks, including the potential loss of capital, liquidity risk, and market volatility. Please read all relevant policy and scheme-related documents carefully before making a financial decision. This article is provided for general educational and informational purposes only and should not be considered insurance, financial, investment, legal, or tax advice.
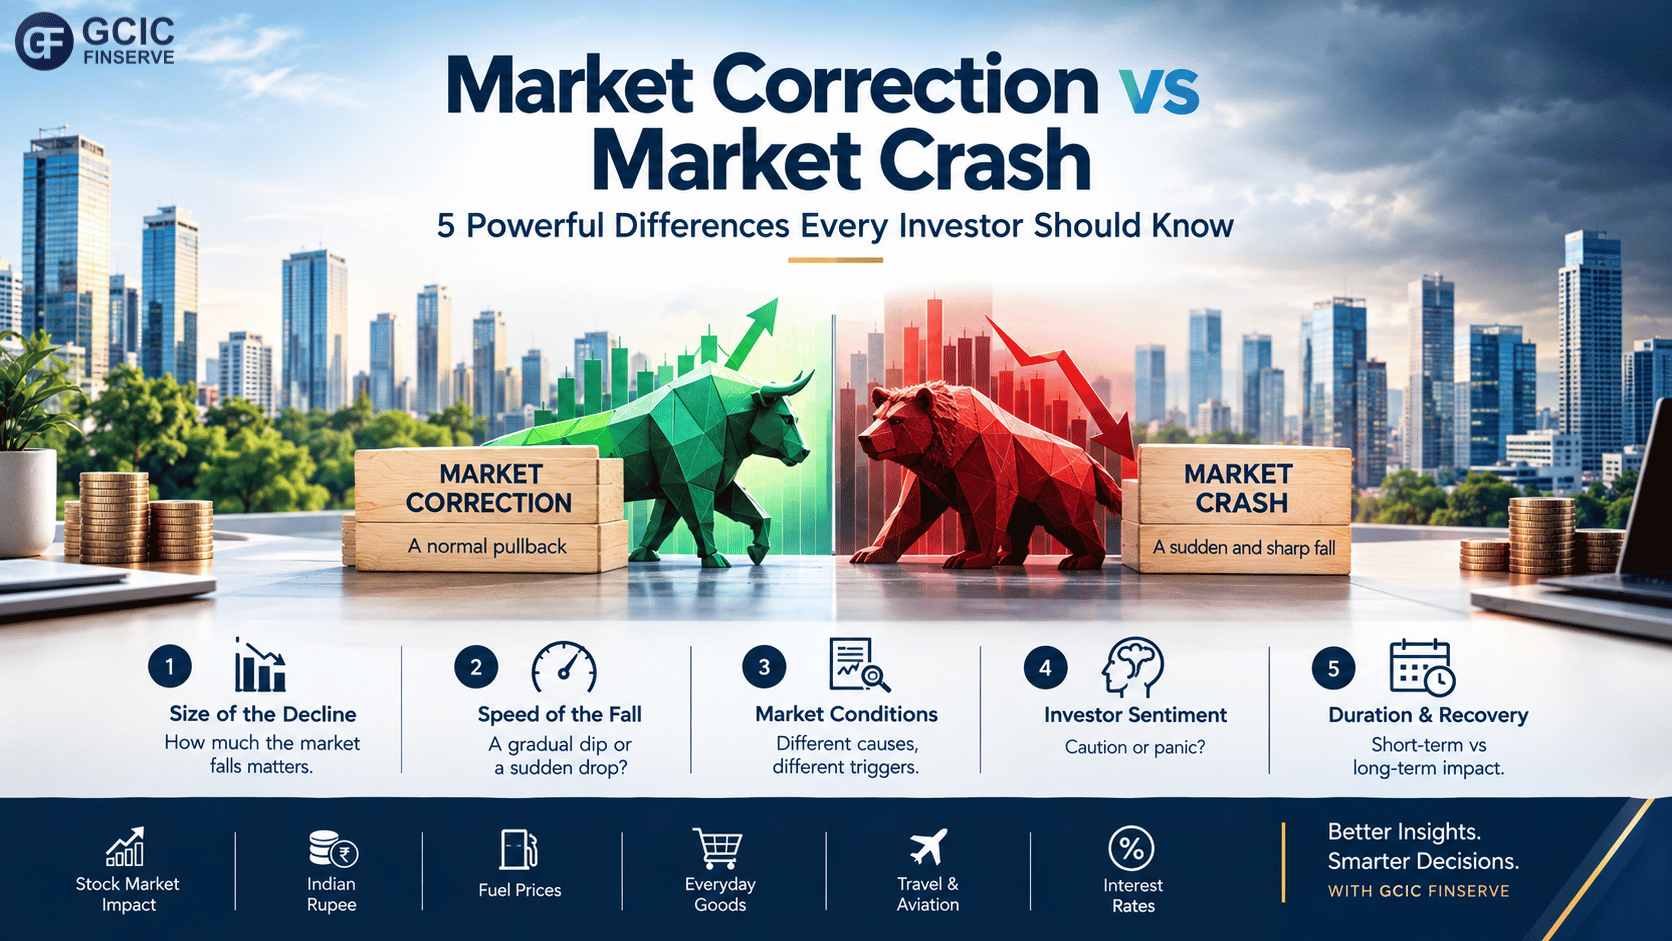
Market Correction vs Market Crash: 5 Powerful Differences Every Investor Should Know

market correction vs market crash explained for Indian investors
Market correction vs market crash: understanding the key differences can help investors navigate market volatility.

Market correction vs market crash—these terms are often used interchangeably whenever the Sensex or Nifty falls, but they describe different types of market movements. A correction generally refers to a decline from a recent peak, while a crash usually describes a sudden and severe fall over a short period.

For investors in Delhi, Gurugram, Noida, and the wider Delhi NCR region, understanding this difference can provide useful context when markets become volatile. Instead of reacting to headlines alone, it helps to look at the size, speed, underlying reasons, and potential impact of the decline.

What Is a Market Correction?

A market correction is a meaningful decline in the value of a stock market index after a period of growth.

NISM educational material describes a correction as a decline of 10% to 19.9% from a recent peak, while a decline of 20% or more is commonly used to describe bear-market territory. These are widely used market conventions rather than universal rules for every market situation.

For example, if the Nifty falls from 25,000 to 22,500, that represents a 10% decline.

A correction can happen for many reasons, including:

  • Profit booking after a strong rally
  • High market valuations
  • Changes in interest-rate expectations
  • Global economic uncertainty
  • Geopolitical developments
  • Changes in corporate earnings expectations
  • Foreign investor selling

A correction does not automatically mean that the long-term outlook for the economy or every company has changed.

What Is a Bear Market?

A bear market is generally a decline of 20% or more from a recent market peak.

NISM uses the 20% threshold when describing bear territory in its educational material.

However, the percentage alone does not explain why the market is falling.

A prolonged bear market can occur alongside concerns about economic growth, corporate earnings, liquidity, valuations, or investor confidence. Therefore, investors should look beyond the percentage decline and understand what is driving the market.

Market Correction vs Market Crash: 5 Key Differences

1. Size of the Decline

The first difference in the market correction vs market crash discussion is the extent of the fall.

A correction is commonly associated with a decline of 10%–19.9% from a recent peak. A decline of 20% or more is generally considered bear-market territory.

A crash, however, does not have one universally accepted percentage threshold.

This means that simply seeing the market fall does not automatically mean a crash is happening.

2. Speed of the Fall

Speed is one of the most important differences when comparing a market correction vs market crash.

A correction can develop over weeks or months. A crash is generally associated with a sudden and severe decline over a short period.

For example, a 15% decline spread across several months is different from a 15% fall occurring within a few trading sessions.

The speed of a decline can also influence investor behavior because sudden losses may lead to increased uncertainty and rapid selling.

3. Underlying Market Conditions

A correction may occur because markets have become expensive, investors are booking profits, or expectations have become too optimistic.

A crash can be associated with a sudden shock or a sharp deterioration in market confidence.

However, there is no single event that defines every market crash. Each episode has its own causes and circumstances.

This is why market correction vs market crash should not be judged only by the number shown on the index screen.

4. Investor Sentiment

Investor psychology can be another major difference.

During a correction, investors may become cautious while still expecting markets or businesses to recover over time.

During a sudden crash, fear can spread much faster. Investors may rush to reduce exposure, which can contribute to further short-term volatility.

Indian markets also have index-based market-wide circuit breakers at 10%, 15% and 20% movements in the Sensex or Nifty 50. When triggered, these can temporarily halt trading under specified rules.

5. Potential Duration and Recovery

A correction can be relatively short-lived, although there is no fixed recovery period.

A deeper market decline can take considerably longer to recover from. The recovery period depends on factors such as economic conditions, corporate earnings, valuations, liquidity, and investor confidence.

Therefore, in a market correction vs market crash situation, investors should avoid assuming that every fall will recover at the same speed.

A Simple Example

Imagine the Nifty is trading at 25,000.

Correction:
Nifty falls to 22,500—a 10% decline.

Bear-market territory:
Nifty falls to 20,000—a 20% decline from 25,000.

Crash:
The market experiences a sudden and severe decline over a short period because of a major shock.

The important point is that a crash is generally discussed in terms of speed and severity, rather than one fixed percentage.

What Should Investors Consider When Markets Fall?

When markets turn red, the first question is often, “Should I sell?”

A better starting point is to understand your own financial situation.

Consider these questions:

  • Has your financial goal changed?
  • Has your investment horizon changed?
  • Has your risk capacity changed?
  • Has your portfolio allocation become significantly different?
  • Has something fundamentally changed about the investment?
  • Are you reacting to information or simply to short-term market movement?

For investors holding mutual funds, reviewing the actual portfolio and investment objective can be more useful than reacting to an index headline. You can learn more about mutual fund investing through GCIC Finserve’s mutual fund investment solutions.

Similarly, a broader financial review can help investors understand whether their investments remain aligned with their goals. GCIC Finserve’s Financial Assessment & Investment Planning service covers financial goals and investment planning.

The key point in the market correction vs market crash discussion is that the label alone should not determine an investment decision.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, we believe market movements should be understood in the context of an investor’s financial goals, investment horizon, risk profile, and overall portfolio.

For investors across South Delhi, Gurugram, Noida, and the wider Delhi NCR region, understanding why markets are falling can provide useful context before making changes to an investment strategy.

GCIC Finserve is an AMFI-registered Mutual Fund Distributor (ARN-272705).

Investors should consider their individual financial circumstances and investment objectives before making investment decisions.

FAQs

Q1. Is a 10% fall in the market a crash?

Not necessarily. A decline of 10%–19.9% from a recent peak is commonly described as a market correction. A crash does not have one universally accepted percentage definition.

Q2. Is a 20% fall considered a bear market?

A decline of 20% or more from a recent peak is the commonly used threshold for bear-market territory.

Q3. How much does the market need to fall to be called a crash?

There is no universally accepted percentage. A crash is generally associated with a sharp and rapid decline accompanied by significant market stress.

Q4. Should I stop my SIP during a market correction?

A market correction by itself does not automatically mean that an SIP should be stopped. Investors should consider their financial goals, investment horizon, cash-flow situation, and risk profile before making changes to an ongoing investment.

Q5. What is the main difference between a market correction and a crash?

A correction is generally a decline of 10%–19.9% from a recent peak, while a crash usually refers to a sudden and severe market fall. The distinction is not based on one universally accepted crash percentage.

Final Word

A correction is not automatically a crash, and a bear market does not necessarily mean a permanent loss.

Understanding market correction vs market crash can help investors put market declines into perspective. Instead of reacting to every red headline, consider the size and speed of the decline, the reason behind it, your investment horizon, financial goals, and overall portfolio.

For long-term investors, having a clear financial plan can provide a framework for dealing with periods of market volatility.

Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Investors should consider their financial goals, risk profile, and investment horizon and consult an appropriately qualified/registered financial professional where required.

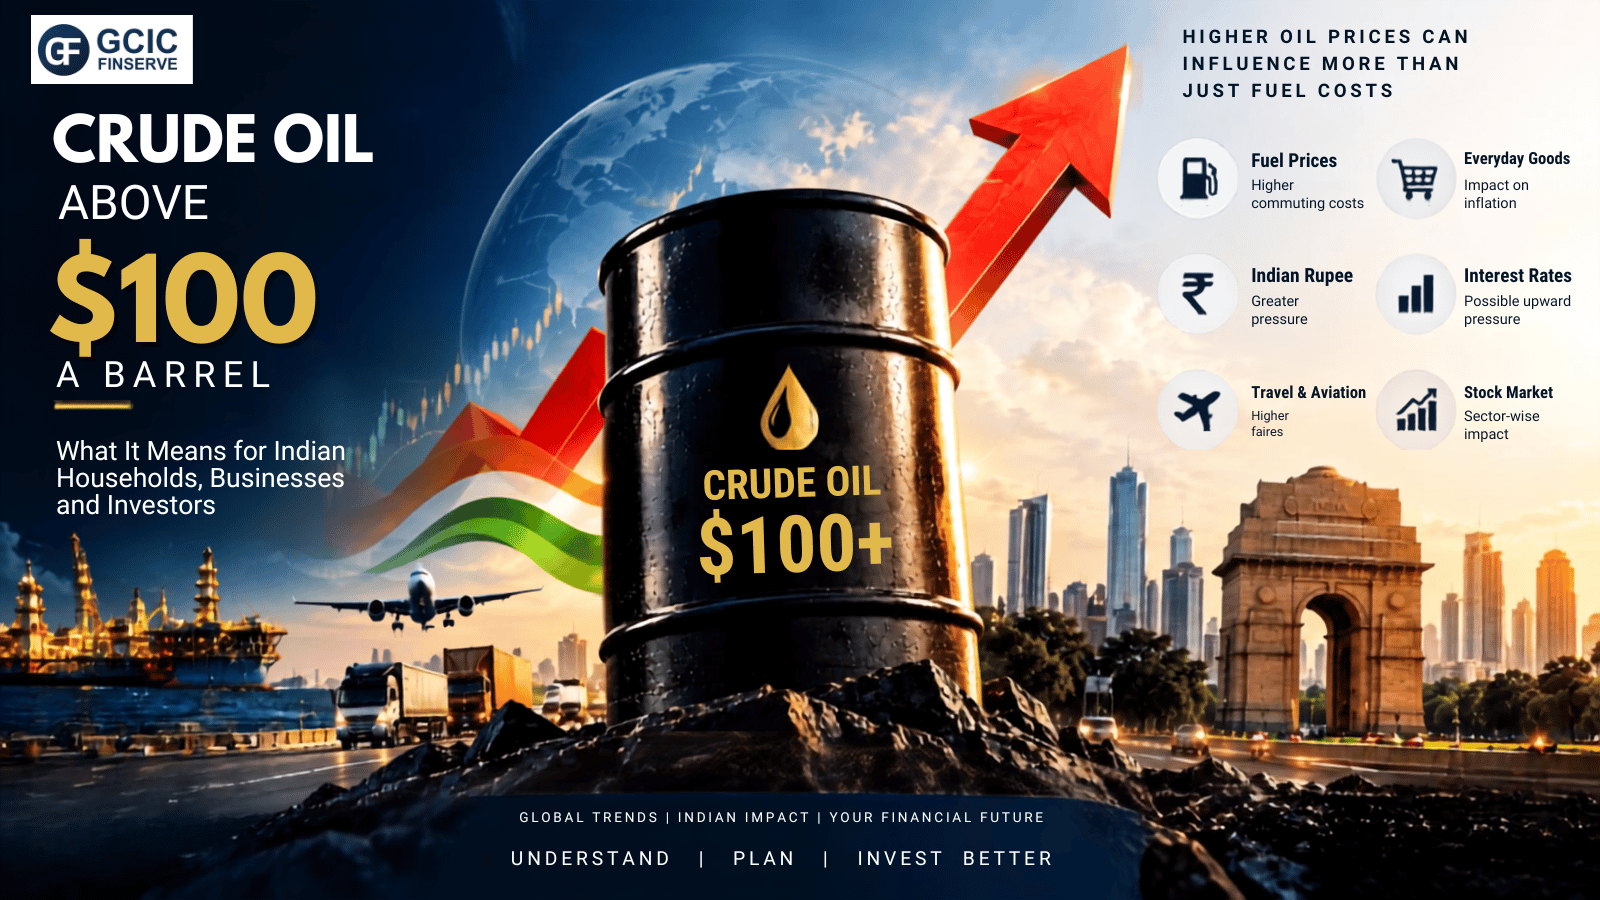
Crude Oil Above $100: 7 Powerful Effects on Indian Investors in 2026

Crude oil above $100 and its impact on Indian investors, inflation, fuel prices and the stock market
Crude oil above $100 can influence fuel costs, inflation, the Indian rupee, interest rates and different market sectors. Understanding these effects can help investors make informed decisions.

Crude oil above $100 a barrel is back in the financial headlines, and investors are once again watching what higher energy prices could mean for inflation, the rupee, interest rates, and the stock market.

For an everyday investor, however, the bigger question isn’t simply where crude oil is trading today. It is how sustained high oil prices can affect your household expenses, businesses, and investments.

Why Crude Oil Above $100 Matters to Indian Households

India relies heavily on imported crude oil. That means a sustained rise in international oil prices can have wider implications for the Indian economy.

When crude remains elevated for an extended period, the effects can travel through fuel costs, transportation, inflation, the rupee, and interest-rate expectations.

However, this does not automatically mean that the stock market will fall.

Markets respond to several factors at the same time, including corporate earnings, interest rates, global economic conditions, currency movements, and investor sentiment.

The important thing is understanding the potential chain reaction when oil prices remain high.

How Crude Oil Above $100 Reaches Your Wallet

Petrol, Diesel, and Daily Commuting

Fuel is one of the most visible connections between crude prices and everyday life.

If international crude prices remain elevated, fuel-related costs can come under pressure. This can affect not only personal vehicle expenses but also taxis, delivery services, and other forms of transportation.

For households across Delhi NCR, even relatively small increases in recurring expenses can add up over time.

Transportation and Everyday Goods

Before a product reaches a store in Gurugram, Noida, South Delhi, or another part of Delhi NCR, it may pass through several stages of transportation.

Higher energy and logistics costs can increase business expenses. Companies may absorb some of these costs or pass a portion on to consumers.

This is one way higher oil prices can contribute to broader inflationary pressure.

Flights and Travel

Airlines are particularly sensitive to fuel costs because aviation fuel is a major operating expense.

If crude oil remains elevated for an extended period, airlines may face higher costs, which can influence profitability and, depending on market conditions, travel prices.

The Inflation and Interest Rate Connection

This is where the crude-oil story becomes particularly important for investors.

Higher oil prices can increase transportation and production costs across different parts of the economy. If businesses pass these costs on to consumers, inflationary pressure can increase.

Persistent inflation can influence expectations around interest rates.

Higher interest rates can affect:

  • Home-loan EMIs
  • Business borrowing costs
  • Consumer spending
  • Corporate investment
  • Bond and fixed-income returns
  • Equity valuations

So the chain can look something like this:

Higher crude prices → higher input costs → inflationary pressure → interest-rate expectations → impact on businesses and markets

The actual outcome can vary depending on the broader economic environment.

Which Sectors Feel Crude Oil Above $100 the Most?

Not every business is affected in the same way.

Some sectors are more directly exposed to higher energy and transportation costs.

Sectors that may face greater pressure

  • Airlines
  • Logistics and transportation
  • Paint companies
  • Certain chemical companies
  • Energy-intensive manufacturers
  • Some automobile-related businesses

At the same time, some companies may have stronger pricing power or other factors that help offset higher costs.

Oil producers can also respond differently to higher crude prices than oil-consuming businesses.

This is why “crude oil above $100 = stock market fall” is too simplistic.

The real question is

Which companies are affected, and how significantly?

What Crude Oil Above $100 Means for Mutual Fund Investors

If you invest through mutual funds rather than directly buying individual stocks, you may wonder why crude oil matters to your portfolio.

The reason is simple: mutual funds may hold companies across sectors such as:

  • Banking
  • Technology
  • Consumer goods
  • Automobiles
  • Energy
  • Manufacturing
  • Infrastructure

Higher oil prices can affect these businesses differently.

Therefore, instead of reacting to a single market headline, investors should look at their actual portfolio, investment horizon, asset allocation and financial goals.

A portfolio review can often provide more useful information than reacting to one day’s movement in crude prices.

The Rupee Angle

Crude oil is traded internationally in US dollars.

When global oil prices rise, India’s import bill can increase. If the rupee is also under pressure against the US dollar, imported oil can become even more expensive in rupee terms.

This can create additional pressure on inflation and India’s external finances.

The broader chain can therefore look like

Crude oil above $100 → higher import costs → currency pressure → inflation concerns → interest-rate expectations → potential impact on businesses and markets

This is not a fixed formula, and several other economic factors influence each stage.

What Should Investors Actually Do?

The first response should be understanding, not panic.

A single headline about crude oil above $100 is rarely a sufficient reason to completely change a long-term investment strategy.

Instead, ask yourself:

  • Has my investment horizon changed?
  • Is my asset allocation still appropriate?
  • Am I overly concentrated in one sector?
  • Have my financial goals changed?
  • Do I have sufficient liquidity for near-term needs?
  • Have the fundamentals of the investments I own changed?

If the answer to these questions is no, reacting purely to an oil-price headline may not improve your investment outcome.

Domestic fuel prices are influenced by multiple factors beyond international crude, including taxes and other components of the pricing structure. For official petroleum-sector data and information, investors can refer to the Petroleum Planning & Analysis Cell (PPAC), Government of India.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, we believe financial information should go beyond explaining what happened in the markets.

Investors also need to understand why it matters to their financial goals.

Whether the headline is about crude oil, interest rates, inflation, or a market correction, a long-term financial plan should be built around your goals, risk profile, investment horizon, and overall financial situation rather than short-term market noise.

If you’re an investor in South Delhi, Gurugram, Noida, or the wider Delhi NCR region, reviewing your portfolio periodically can help you understand whether your investments continue to match your financial objectives.

Connect with GCIC Finserve to discuss your financial planning and investment requirements.

FAQs

1. Does crude oil above $100 mean the Indian stock market will fall?

No. Crude oil is one of many factors that influence the stock market. Earnings, interest rates, global economic conditions, currency movements, and investor sentiment also play important roles.

2. How does crude oil above $100 affect petrol prices in India?

Higher international crude prices can increase input costs, but domestic fuel prices also depend on factors such as taxes, refining costs, and other components. Therefore, the relationship is not necessarily one-to-one.

3. Should I change my mutual fund portfolio because crude oil is above $100?

Not automatically. Review your investment goals, risk profile, asset allocation, and the actual holdings of your funds before making significant changes.

4. Which sectors are most affected by high crude oil prices?

Airlines, logistics, transportation, and some chemical, paint, and manufacturing companies can face greater cost pressure. The impact varies by company and its ability to manage or pass on higher costs.

5. Can high crude oil prices affect the Indian rupee?

Yes. Higher oil prices can increase India’s import bill and demand for US dollars, potentially putting pressure on the rupee, although currency movements depend on many other factors as well. Recent market commentary has linked elevated oil prices with pressure on the rupee.

Final Word

Crude oil above $100 isn’t just a global financial headline.

For Indian households and investors, sustained high oil prices can potentially influence fuel costs, inflation, currency movements, interest-rate expectations, corporate profitability, and market sentiment.

But the objective shouldn’t be to predict every movement in the price of oil.

It should be to understand what actually matters for your financial plan.

Plan your investments around your goals—not around the day’s headline.

Disclaimer

This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Investors should consider their financial goals, risk profile and investment horizon and consult an appropriately qualified/registered financial professional where required.

Why Is the Indian Stock Market Not Going Up? 7 Key Reasons Explained

Indian stock market
Indian stock market
Understanding the key factors influencing the Indian stock market.

The Indian stock market has spent much of the recent period struggling to build sustained upward momentum.

For long-term investors, that can be uncomfortable.

But a market that isn’t moving higher is not necessarily a market that is fundamentally broken.

Markets rarely move because of a single variable. They move when liquidity, earnings, valuations, interest rates, global risk appetite, and investor expectations interact with one another.

In the current market environment, several of those forces are creating pressure on Indian equities.

Here are seven factors investors should understand before making decisions based on the latest market movement.

  1. Crude Oil Has Become a Major Variable Again

For India, oil matters.

India imports the majority of the crude oil it consumes. When crude prices rise sharply, the impact can extend beyond petrol and diesel.

Higher crude prices can put pressure on:

  • India’s import bill
  • The current account
  • The Indian rupee
  • Inflation
  • Corporate input costs
  • Consumer purchasing power

With crude oil moving above the $100-per-barrel level amid heightened geopolitical tensions, investors have begun reassessing the potential inflationary and macroeconomic consequences.

The important point is not simply that “oil is expensive.”

It is whether higher oil prices remain elevated for long enough to affect economic expectations.

2. Foreign Investors Are Selling

Foreign Portfolio Investors (FPIs) remain an important source of liquidity for Indian equities.

When global investors reduce exposure to emerging markets, India can experience selling pressure even when domestic fundamentals remain relatively resilient.

The recent market environment has again highlighted this dynamic.

However, FPI selling should not automatically be interpreted as a verdict on India’s long-term economic prospects.

Foreign capital responds to several variables simultaneously:

Global interest rates → Dollar strength → Emerging-market risk → Valuations → Relative attractiveness

A foreign investor can reduce Indian equity exposure without believing that India’s long-term growth story has disappeared.

3. The Rupee Is Under Pressure

Currency movements are often overlooked by equity investors.

A weaker rupee can increase the domestic cost of imported commodities—particularly crude oil—creating another potential source of inflationary pressure.

It also changes the return profile for foreign investors.

This creates an interconnected chain:

Higher Oil → Higher Import Costs → Rupee Pressure → Inflation Concerns → Rate Expectations → Equity Valuations

Markets are currently pricing these relationships, not simply reacting to an individual headline.

4. Geopolitical Risk Is Increasing the Market’s Risk Premium

Markets dislike uncertainty.

The escalation of geopolitical tensions in the Middle East has introduced another variable into an already complicated macroeconomic environment.

The market does not need to know exactly what happens next to react.

Investors typically begin demanding a greater risk premium when uncertainty rises.

That can result in:

  • Lower equity valuations
  • Increased volatility
  • Rotation toward defensive assets
  • Reduced risk-taking
  • Greater sensitivity to negative news

This is one reason markets can remain subdued even when there is no single domestic economic crisis.

5. Valuations Matter

A strong company can still be an expensive investment.

India’s long-term growth story remains compelling, but investors cannot evaluate equities purely through the lens of economic growth.

The question is also:

How much future growth is already reflected in today’s prices?

When valuations are elevated, markets become more sensitive to disappointments.

If earnings grow slower than expected, interest rates remain higher for longer, or global risk appetite deteriorates, investors may be willing to pay lower multiples for the same earnings.

This is why good fundamentals and weak short-term markets can coexist.

6. Investors Are Waiting for Greater Clarity

Markets are ultimately forward-looking.

Investors are continuously trying to estimate what the next 6–18 months could look like.

At present, several questions remain open:

  • Where will crude oil settle?
  • How persistent will inflation be?
  • What happens to global interest rates?
  • How will the rupee behave?
  • Will foreign capital return?
  • Can corporate earnings meet expectations?

Until some of these variables become clearer, markets can remain range-bound or volatile.

Sometimes the absence of a strong upward catalyst is itself enough to keep markets from moving meaningfully higher.

7. The Market May Simply Be Digesting the Previous Rally

This is perhaps the least dramatic—and often the most overlooked—explanation.

Markets do not move in straight lines.

Periods of strong performance are frequently followed by periods of:

Consolidation → Profit Booking → Rotation → Repricing → Reaccumulation

A sideways market does not necessarily mean that the long-term investment thesis has failed.

It can simply mean that buyers and sellers are temporarily reaching equilibrium.

The market is reassessing expectations.

So, Is Something Fundamentally Wrong With the Indian Stock Market?

Not necessarily.

That distinction matters.

There is a difference between:

The market isn’t going up.

and

The underlying investment thesis has deteriorated.

They are not the same statement.

Markets can remain flat or decline because expectations were too optimistic, valuations were stretched, global liquidity changed, geopolitical risk increased, or investors simply became more cautious.

A weaker market does not automatically mean weaker long-term fundamentals. Investors should distinguish between short-term market sentiment and the underlying fundamentals of the businesses they own.

For a long-term investor, the appropriate response is therefore not to react to every movement in the index.

It is to determine whether your portfolio still makes sense relative to your goals, time horizon and risk capacity.

What Should Investors Do Right Now?

There is no universal answer.

A sensible framework is to ask five questions.

1. Has Your Financial Goal Changed?

If not, a short-term market movement may not require a change in strategy.

2. Has Your Investment Horizon Changed?

Money required in the near term should generally not be exposed to the same level of equity risk as long-term capital.

3. Has the Reason You Invested Changed?

If the underlying thesis has materially deteriorated, that deserves analysis.

4. Has Your Asset Allocation Drifted?

Market movements can cause your portfolio to become more aggressive or defensive than originally intended.

Are You Reacting to Information—or Emotion?

This is perhaps the most important question.

A market decline can create an overwhelming urge to do something.

But sometimes the most rational decision is to review rather than react.

The Bigger Picture for the Indian Stock Market

The Indian market’s current weakness is being shaped by a combination of oil, geopolitics, foreign flows, currency pressure, valuations, and uncertainty.

None of these factors should be viewed in isolation.

More importantly, none of them can reliably tell an investor where the market will be tomorrow.

That is not the objective of investing.

The objective is to construct a portfolio capable of surviving periods when markets do not cooperate with our expectations.

Because wealth is rarely built by predicting every market move.

It is built by having a strategy that can withstand them.

GCIC Perspective

A stagnant market is not necessarily a signal to stop investing.

It is a signal to pay closer attention to what actually drives your portfolio.

Instead of asking:

When will the market go up?

A more useful question may be:

Is my portfolio positioned appropriately for the goals I am investing for?

The first question requires a prediction.

The second requires a plan.

At GCIC Finserve, we believe long-term investing should be guided by financial objectives, appropriate asset allocation, and discipline—not by the latest movement in the market.

Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice, a recommendation, or a solicitation to buy or sell any security or investment product. Mutual fund investments are subject to market risks. Investors should consider their financial objectives, risk profile, and investment horizon and review relevant scheme documents before investing.

Ronald Read Investor Story: The Janitor Who Built an $8 Million Fortune

Ronald Read investor story about a janitor who built an $8 million fortune through disciplined investing
The Ronald Read investor story highlights the power of disciplined investing, patience and long-term wealth creation.

The Ronald Read investor story is a powerful reminder that building substantial wealth isn’t always about earning a high income. Discipline, consistent saving, sensible investing, and time can also play an important role in long-term wealth creation.

Ronald Read worked as a gas station attendant and later worked as a part-time janitor at J.C. Penney in Brattleboro, Vermont. When he passed away in 2014 at age 92, his estate was reportedly worth around $8 million.

What made his story remarkable was not simply the amount of wealth he accumulated, but the quiet and disciplined way in which he built it.

Who Was Ronald Read?

Read came from modest beginnings, served in World War II, and lived a relatively simple life.

Over several decades, he saved and invested while maintaining a lifestyle far removed from the image many people associate with significant wealth.

After his death, a significant portion of his estate was donated to charitable causes, including Brattleboro Memorial Hospital and Brooks Memorial Library.

His story became a powerful example of how financial behavior can matter just as much as income.

The Real Lesson Behind the Ronald Read Investor Story

What makes this story relevant today is how the wealth was accumulated.

Read was reported to have invested in shares of established companies and held investments for long periods rather than constantly buying and selling based on short-term market movements.

His story illustrates an important principle:

Building wealth is not always about finding the next big opportunity. Sometimes it is about consistently making sensible decisions and giving them enough time to work.

A high salary can make investing easier, but income alone does not create financial security.

Saving, investing, controlling expenses, and maintaining a long-term perspective can all play an important role.

Key Takeaways for Indian Investors

1. Start early, even if you start small

Waiting until your income becomes significantly higher may mean missing valuable time for long-term investing and compounding.

Starting with an amount that fits your financial situation can help establish a consistent investing habit.

2. Think long term

Markets can experience periods of volatility, but long-term investing is fundamentally different from trying to predict every short-term movement.

3. Keep expenses under control

Living below your means can create more room for saving and investing.

4. Let time work

Compounding becomes increasingly powerful when investments remain invested for long periods.

For long-term investors, staying invested consistently may be more practical than trying to predict every short-term market movement.

How This Applies to Investors in Delhi NCR

For many families across Delhi NCR, wealth creation can sometimes feel like something reserved for people with very high incomes.

The Ronald Read story offers a different perspective.

A disciplined investment approach, when aligned with long-term financial goals, can help investors work toward building wealth over many years.

A Systematic Investment Plan (SIP) is a method of investing a fixed amount at regular intervals in a mutual fund scheme. The amount and investment approach should depend on an individual’s financial goals, time horizon, and risk tolerance.

The key lesson isn’t that every investor will achieve Ronald Read’s outcome.

It is that starting early, staying consistent, and giving investments sufficient time can make a meaningful difference.

Common Mistakes That Can Disrupt Long-Term Wealth Creation

  • Waiting for a higher salary before starting
  • Frequently changing investments because of market noise
  • Making decisions based purely on short-term market movements
  • Investing without clearly defined financial goals
  • Ignoring risk while focusing only on potential returns

Building Your Own Long-Term Wealth Plan

If you want to apply the principles from the Ronald Read story, start with a simple framework:

  1. Define your financial goals.
  2. Determine how much you can invest regularly.
  3. Choose investment options appropriate for your goals and risk tolerance.
  4. Stay focused on your long-term time horizon.
  5. Review your investments periodically rather than reacting to every market movement.

At GCIC Finserve, we help investors explore investment solutions based on their financial goals, investment horizon, and individual requirements.


The objective isn’t to chase every market opportunity. It is to build a disciplined approach that can remain aligned with your long-term financial journey.

Final Thoughts

The Ronald Read investor story isn’t simply about a million-dollar fortune. It is a story about discipline, patience, controlled spending, and the power of time.

You don’t need to look wealthy to be building wealth.

Sometimes the most important financial decisions are the ones nobody sees.

Want to explore investment solutions for your long-term goals?

Connect with GCIC Finserve.

FAQs

1. Who was Ronald Read?
Ronald Read was a US janitor and gas station attendant whose disciplined saving and long-term investing helped him build an estate reportedly worth around $8 million.

2. What can investors learn from the Ronald Read investor story?
The key lessons are starting early, investing consistently, controlling expenses, and staying focused on long-term goals.

3. Can Indian investors apply the lessons from Ronald Read’s story?
Yes. Indian investors can apply these principles through disciplined saving, suitable investment options, and a long-term approach aligned with their goals and risk tolerance.

4. How can GCIC Finserve help with long-term investment goals?
GCIC Finserve provides investment solutions based on financial goals, investment horizon, and individual requirements, helping investors explore suitable options for their long-term journey.


Disclaimer: Investments are subject to market risks. Past performance or historical examples do not guarantee future results. Please read all scheme-related documents carefully and consider your financial goals, investment horizon, and risk tolerance before investing.

Child Education Financial Planning: A Smart Parent’s Guide 

Child education financial planning
Planning today for your child’s education and a financially secure future

Child education financial planning is one of the most important financial decisions a parent makes—yet most families start too late. Education costs in India can rise significantly over time, which means parents need to account for inflation when estimating their child’s future education expenses.

If you’re a parent in Delhi NCR, where private schooling and college costs are already among the highest in the country, this becomes even more urgent. This guide breaks down exactly how to approach child education financial planning the right way.

Why Child Education Financial Planning Matters

Without a clear plan, most parents end up depending on education loans at the last minute, which adds years of debt burden right when your child is starting their career. Proper child education financial planning helps you:

  • Build a dedicated corpus without disturbing other financial goals
  • Beat education cost inflation instead of scrambling later
  • Avoid high-interest education loans
  • Give your child access to better institutions, including study-abroad options
  • Stay financially secure even during emergencies, through insurance-backed plans

How to Start Child Education Financial Planning

  1. Define the Goal Clearly
    Decide the course, expected year, and current cost. This becomes your baseline for calculating the future cost with inflation factored in.
  2. Use an Education Cost Calculator
    This is the step most parents skip. An education calculator shows you exactly how much a course will cost by the time your child is ready—factoring in inflation—and how much you need to invest monthly to reach that number. At GCIC Finserve, our child education calculator does exactly this in under two minutes, so you get a realistic number instead of guesswork.
  3. Choose the Right Investment Mix
    Depending on your timeline, a mix of SIPs in mutual funds, child ULIPs, or PPF can work well. Longer timelines (10+ years) can handle more equity exposure for better growth; shorter timelines need safer, more stable instruments.
  4. Add Insurance Protection
    A good child education plan should include a waiver-of-premium benefit—meaning if something happens to the parent, the policy continues without further premiums, and the child still receives the full planned amount.
  5. Review and Increase Contributions Yearly
    As your income grows, increase your SIP or premium amount. Even a 10% annual step-up can significantly shorten the gap between your target and actual corpus.

Advantages of Planning Through GCIC Finserve

Many families make the mistake of buying a random insurance or investment product without checking if it actually matches their child’s education timeline and cost target. This is exactly where working with GCIC Finserve makes a difference—here’s what you get:

  • Personalized calculation: We use our education calculator to show your exact required monthly investment, not a generic estimate.
  • Unbiased plan comparison: We compare multiple child education and investment plans from top insurers so you get the best fit, not just the first option.
  • Ongoing review support: Education costs and your income change over time—our advisors help you adjust your plan yearly instead of leaving it untouched for a decade.
  • Local Delhi NCR expertise: We understand regional schooling and college cost trends, so our recommendations are realistic for families here.

Child Education Financial Planning: Common Mistakes to Avoid

  • Starting late, assuming “there’s still time”
  • Ignoring education inflation while calculating the target amount
  • Mixing education savings with general investments with no clear goal
  • Skipping insurance protection within the plan
  • Not using a calculator to validate the numbers

Final Thoughts

Child education financial planning isn’t just about saving money — it’s about giving your child options when the time comes, without financial stress. The earlier you start, the smaller your monthly commitment needs to be. Use a proper calculator, choose the right investment mix, and review your plan every year.

Want a personalized calculation for your child’s education goal? Try our free education calculator or talk to a GCIC Finserve advisor today.

For more on how education inflation is calculated in India, refer to this RBI report on inflation trends.

FAQs

Q1. What is child education financial planning?
It’s the process of saving and investing systematically to build enough funds for your child’s future education costs, including school, college, or study abroad.

Q2. How much should I invest monthly for my child’s education?
It depends on your child’s age, target course, and years left—use an education calculator to get an exact figure.

Q3. Which is better—SIP or child ULIP for education planning?
SIPs offer better growth over the long term, while ULIPs add insurance protection. Many families use a mix of both.

Q4. What happens to the plan if something happens to the parent?
Plans with a waiver-of-premium benefit continue automatically, ensuring your child still receives the full planned amount.

Disclaimer:

Investment and insurance plans are subject to market risks and terms & conditions. Please read all scheme-related documents carefully and consult a financial advisor before investing.

Real Estate vs Mutual Funds: Which Is Better for Long-Term Investment?

real estate vs mutual funds comparison
Real Estate vs Mutual Funds: Key Investment Differences

Real estate vs mutual funds is a common investment decision for investors looking to build long-term wealth. Both investment options have their own advantages, risks, and suitability depending on an investor’s financial goals, risk tolerance, investment horizon, and liquidity needs.

Real estate involves investing in physical property, while mutual funds provide exposure to professionally managed portfolios of securities.

For investors in Delhi NCR, South Delhi, Noida, Gurugram, and Ghaziabad, this decision can be especially important because property has traditionally been a popular wealth-building option in the region. 

So, which is better? 

There is no single answer. The right choice depends on your financial goals, risk tolerance, investment horizons, and liquidity needs. 

Real Estate vs Mutual Funds: Quick Comparison 

Factor  Real Estate  Mutual Funds 
Initial Investment  Usually high  Can start with smaller amounts 
Liquidity  Generally lower  Generally higher for open-ended funds 
Diversification  Usually limited  Can provide diversification 
Management  Investor manages the property.  Professionally managed 
Maintenance  Required  No physical maintenance 
Investment Flexibility  Lower  Higher 
Risk  Market & property-specific  Market-linked 
Regular Investing  Difficult  SIP available 


Why Do People Invest in Real Estate?
 

Real estate has a strong appeal because it is a physical asset. Investors can use the property, rent it out, or hold it for potential appreciation. 

Property can also provide rental income. However, buying real estate usually requires substantial capital. Investors may also have to consider stamp duty, registration, maintenance, property taxes, loan costs, and other expenses. 

Another important factor is liquidity. Selling a property can take time, especially when you need to sell at a specific price. 

Why Are Mutual Funds Becoming Popular? 

A major benefit of mutual funds is flexibility. 

Instead of investing a large amount in one physical asset, investors can choose schemes that provide exposure to a portfolio of securities. This can help with diversification and allows investors to participate in financial markets without directly managing individual securities. 

Mutual funds also make regular investing easier through Systematic Investment Plans (SIPs). An investor can invest a fixed amount periodically rather than waiting to accumulate a large amount for a property purchase. 

However, mutual funds are market-linked investments. Their value can rise or fall depending on market conditions, and returns are not guaranteed. 

Mutual Funds vs Property: Which Offers More Flexibility? 

If flexibility is important to you, mutual funds can have an advantage. 

An investor can generally start with a relatively smaller amount, increase investments over time, and, depending on the scheme, redeem investments when required. 

Real estate is less flexible because a property cannot usually be bought or sold in small portions. The transaction can also involve significant costs and paperwork. 

This makes mutual funds a practical option for investors who want to build wealth gradually while maintaining greater investment flexibility. 

Which Is Better for Long-Term Investment? 

For long-term investors, both real estate and mutual funds can have a role in a diversified financial plan. 

Real estate may suit someone who wants a physical asset and has sufficient capital. Mutual funds may suit investors looking for diversification, professional management, and the ability to invest systematically. 

The important point is not to choose an investment only because it generated good returns in the past. 

Instead, consider: 

  • Your financial goals 
  • Investment horizon 
  • Risk tolerance 
  • Liquidity requirements 
  • Existing investments 
  • Available capital 

What About Investors in Delhi NCR? 

For people searching for long-term investment options in Delhi NCR, property may seem like the obvious choice. But investing all your money into one property can concentrate your wealth in a single asset and location. 

Mutual funds can provide another route to diversification and systematic investing. 

At GCIC Finserve, investors can explore mutual fund solutions based on their financial objectives rather than following a one-size-fits-all approach. 

Final Verdict: Real Estate or Mutual Funds? 

So, real estate vs mutual funds—which is better? 

The answer depends on the investor’s goals, risk profile, and financial situation. 

If you prefer physical assets and have substantial capital, real estate may suit your requirements. If you prefer flexibility, diversification, and systematic investing, mutual funds may be worth considering. 

For many investors, the smarter approach may not be choosing only one. A properly planned portfolio can include different asset classes according to individual financial goals and risk appetite. 


FAQ 

1. Is real estate better than mutual funds?

Not necessarily. Real estate and mutual funds have different characteristics. The better option depends on your financial goals, risk tolerance, investment horizons, and liquidity requirements.

2. Which is better, property or mutual funds?

Property may appeal to investors who prefer physical assets, while mutual funds can offer greater flexibility and diversification. Your personal financial situation should determine the choice.

3. Are mutual funds good for long-term investment?

Mutual funds can be suitable for long-term investing, depending on the type of fund and the investor’s goals and risk profile. Equity-oriented funds, for example, are generally subject to market fluctuations.

4. Can I invest in mutual funds instead of buying property?

Yes. Mutual funds can be an alternative way to invest for long-term financial goals without purchasing physical property. They also allow investors to start with comparatively smaller amounts and invest through SIPs.

5. Are mutual funds safer than real estate?

Neither is automatically safe. Mutual funds carry market-related risks, while real estate involves property-market, liquidity, legal, financing, and location-related risks. Risk depends on the specific investment.

6. Why are mutual funds popular among investors?

Mutual funds can offer diversification, professional management, flexibility, and systematic investment options such as SIPs. These features make them accessible to a wide range of investors.

Disclaimer: Mutual fund investments are subject to market risks. Past performance does not guarantee future returns. Real estate investments also involve market, liquidity, legal, financing, and other risks. Investors should evaluate their financial goals, risk profile, and investment horizon before making investment decisions. This article is for educational purposes only and should not be considered investment advice.

Rupee hits highest level in August against US dollar on fading tariff risks, GST boost

Rupee hits highest level in August

Indian Rupee strengthened to its highest level in August against the US dollar on Tuesday, supported by easing concerns over additional US tariffs and expectations that proposed GST reforms could boost domestic economic growth.

The currency rose to as much as 87.2050 per US dollar, compared with 87.35 in the previous session, before settling at 87.2250. Analysts attributed the gains to renewed optimism following the Trump-Putin meeting and upcoming US-Ukraine talks, which Nomura said may reduce the likelihood of new sanctions or tariffs on India over its Russian oil purchases.

Prime Minister Narendra Modi’s proposed GST rationalisation is also lifting sentiment, with economists saying the measures could boost consumption and offset pressure from weak external demand.

While the rupee advanced, most Asian currencies slipped as US Treasury yields climbed, with the 10-year yield hitting a two-week high on Monday.

Bajaj Finance, Axis Bank, HDFC Bank Rally Up to 6% on S&P Upgrade and GST Reform Hopes

GST Reform

Bajaj Finance shares rallied sharply in early trade on Monday, gaining as much as 6% alongside Axis Bank and HDFC Bank as investor sentiment improved following S&P Global’s credit-rating upgrades and expectations of GST reforms.

At 10:10 a.m., the Nifty Bank index climbed over 1.3% to around 56,035, while the Nifty Financial Services index gained nearly 2% to trade near 26,810. Bajaj Finance, Axis Bank, and HDFC Bank were among the top gainers, supported by strong buying across the financial sector.

S&P Upgrade Lifts Sentiment

S&P Global on Aug. 15 upgraded its long-term issuer credit ratings for seven major Indian banks — including SBI, ICICI Bank, HDFC Bank, Axis Bank, Kotak Mahindra Bank, Union Bank of India, and Indian Bank — and three finance companies: Bajaj Finance, Tata Capital, and L&T Finance. The rating agency cited India’s robust economic momentum, improved asset quality, and strong profitability outlook for the financial sector.

“We expect India’s banks to maintain adequate asset quality, good profitability, and enhanced capitalization over the next 12-24 months despite some pockets of stress,” S&P said, adding that overall credit risk has declined. The move comes just a day after S&P upgraded India’s sovereign credit rating, providing a further boost to investor sentiment.

Motilal Oswal Financial Services noted that the upgrade could reduce borrowing costs for Indian financial firms accessing overseas markets. Companies such as Bajaj Finance could see a 15–20 basis point reduction in external commercial borrowing rates, while stronger foreign portfolio investment flows may support the rupee and bond yields.

GST Reform Expectations Add Fuel

Investor enthusiasm was also buoyed by Prime Minister Narendra Modi’s Independence Day hint at a new round of GST reforms, potentially to be unveiled around Diwali. The government is reportedly considering a simplified two-slab tax structure — “standard” and “merit” — with special rates limited to a few items.

Analysts believe such reforms could lower the tax burden on consumers purchasing electronics and other durables, spurring demand. This is expected to benefit NBFCs like Bajaj Finance, which finance retail purchases through affordable EMIs.

The dual tailwinds of a global rating upgrade and anticipated tax reforms have positioned India’s financial stocks for continued momentum, analysts say, as foreign and domestic investors alike increase exposure to the sector.

Trump Signals New Tariffs on Steel and Semiconductor Imports

Trump Signals New Tariffs

Trump tariffs on steel and semiconductor imports are set to become a major focus of U.S. trade policy, with President Donald Trump indicating that new duties could be announced in the coming weeks.

“I’ll be setting tariffs next week and the week after on steel and on, I would say, chips,” Trump told reporters aboard Air Force One en route to Alaska for a meeting with Russian President Vladimir Putin. He said the duties would start at lower rates to give companies time to ramp up U.S. production before increasing sharply later—a phased approach he has also proposed for pharmaceutical imports.

“I’m going to have a rate that is going to be lower at the beginning—that gives them a chance to come in and build — and very high after a certain period of time,” Trump said, adding that he expects companies will choose to manufacture in the U.S. rather than face steep tariffs.

Trump has reshaped global trade policy with sweeping duties on imports from nearly all countries, targeting industries including automotive and metals. In February, he raised tariffs on steel and aluminum to 25%, later doubling them to 50% in May to encourage domestic production. It remains unclear if the upcoming announcement will include further hikes on those metals.

Last week, Trump said semiconductor imports would face a 100% tariff unless companies committed to building manufacturing facilities in the United States. His latest comments came alongside news that Apple would invest an additional $100 billion in domestic operations.

Explore More Blogs